
Klarna alternatives
12 products compared · Updated October 31, 2026
The short answer
For US e-commerce merchants, Affirm is the strongest alternative for flexible, longer-term BNPL with no late fees. Afterpay offers a simpler pay-in-4 model with a popular consumer app and in-store support. Sezzle suits small merchants and shoppers who want rewards and credit building. Choose based on your need for longer terms, app engagement, or credit-building features.
Your shortlist, at a glance
Read the comparisons ↓ AffirmNot publishedUS e-commerce merchants who want a flexible BNPL option with longer terms and no late fees for customers.
 AfterpayNot publishedRetailers and shoppers in the U.S. who want a straightforward pay-in-4 option with a popular consumer app and in-store payment support.
 PayPalCustom quoteOnline businesses in the UK that want a single checkout for PayPal, cards, and Pay in 3, plus the option to sell in person with card readers.
 SezzleNot publishedUS shoppers and small merchants who want a simple Pay in 4 model with rewards and credit reporting.
- QQuadpaySee websiteOther
 ZipNot publishedEnterprises and high-growth companies that need to automate procurement workflows from request to payment and manage third-party risk.
- CClearpayNot publishedUS retailers and shoppers who want a straightforward BNPL option with a strong consumer app and in-store availability.
- SSplititNot publishedMerchants and banks that want to offer card-linked installments with high approval rates and no new debt for customers.
 AlboNot publishedMexican founders and small businesses that want a single app for personal finance, payroll cards, and up to 3,000 simultaneous transfers.
 AplazoSee websiteFlexible installment payments for shoppers in Mexico
 AtratoNot publishedMexican retailers that want to offer installment credit to customers without a credit card.
 CredPalSee websiteCredPal is a buy now pay later company in Africa that allows…
About Klarna and its alternatives
Klarna is a payments and marketing platform that lets shoppers pay over time at checkout. It is known for flexible installment options, a consumer app, and performance marketing tools that help retailers grow sales.
When comparing alternatives, weigh pricing structure, geographic coverage, integration complexity, and contract terms. Some providers publish transparent fees, while others require custom quotes. Consider whether you need consumer-facing BNPL, B2B procurement, or card-linked installments.
Explore the alternatives
- Not published
1.Affirm
Best for: US e-commerce merchants who want a flexible BNPL option with longer terms and no late fees for customers.
- Pricing
- Not published
- Category
- E-commerce
Affirm lets shoppers pay over time with no late fees, and merchants pay a fee per transaction. Choose it over Klarna when you want a US-focused BNPL provider with longer-term installment options and transparent upfront costs.
Where it is strong
- No late fees for shoppers
- Flexible payment plans, including longer terms
- Shows total cost upfront to customers
Where it falls short
- Pricing for merchants is not published
- US-focused, so less suited for international expansion
- Pricing:
- Pricing is not published on the site.
- Not published
2.Afterpay
Best for: Retailers and shoppers in the U.S. who want a straightforward pay-in-4 option with a popular consumer app and in-store payment support.
- Pricing
- Not published
- Category
- E-commerce
Afterpay is a buy now pay later service that lets shoppers split purchases into four interest-free payments or longer installment plans. Choose it over Klarna if you want a simpler, app-centric BNPL experience with a strong focus on in-store availability and a large partner brand network.
Where it is strong
- Offers pay-in-4 interest-free payments and longer plans up to 24 months
- No late fees when you pay on time, with reminders and caps on late payments
- Works online and in-store at thousands of partner brands
Where it falls short
- Pricing for merchants is not disclosed publicly
- Eligibility requires U.S. residency and being 18 or older, with possible finance fees on certain loans
- Pricing:
- Pricing is not published on the site.
- Custom quote
3.PayPal
Best for: Online businesses in the UK that want a single checkout for PayPal, cards, and Pay in 3, plus the option to sell in person with card readers.
- Pricing
- Custom quote
- Category
- Finance & Accounting
PayPal is a broad payments platform that handles online checkout, in-person card payments, and peer-to-peer transfers, with built-in buyer and seller protection. Choose it over Klarna when you want one provider for both card processing and pay-later options, especially if you already sell across multiple markets.
Where it is strong
- Reaches up to 400M active accounts worldwide
- Built-in Seller Protection on eligible transactions
- Offers card readers and POS for in-person sales
Where it falls short
- Expanded Checkout puts chargeback handling on you
- Pay in 3 is limited to UK customers
- Pricing:
- In the United Kingdom, standard domestic fees apply for PayPal payments, Pay Later, and card processing. Custom pricing is available for eligible businesses with large volumes or unique models.
- Not published
4.Sezzle
Best for: US shoppers and small merchants who want a simple Pay in 4 model with rewards and credit reporting.
- Pricing
- Not published
- Category
- E-commerce
Sezzle is a buy now, pay later app that splits purchases into four interest-free payments over six weeks. It also includes rewards, credit history building, and a Visa card for use anywhere Visa is accepted. Choose Sezzle over Klarna if you want a US-focused BNPL option with a stronger emphasis on rewards and credit building.
Where it is strong
- Pay in 4 interest-free installments over six weeks
- Build credit history with on-time payments via Sezzle Up
- Earn rewards on purchases and games, redeemable for gift cards
Where it falls short
- Pricing for merchants is not disclosed on the site
- No mention of international availability or multi-currency support
- Pricing:
- Pricing is not published on the site.
- QSee website
5.Quadpay
Other
Splits purchases into four installments, targeting budget-conscious shoppers like Klarna.
- Not published
6.Zip
Best for: Enterprises and high-growth companies that need to automate procurement workflows from request to payment and manage third-party risk.
- Pricing
- Not published
- Category
- Finance & Accounting
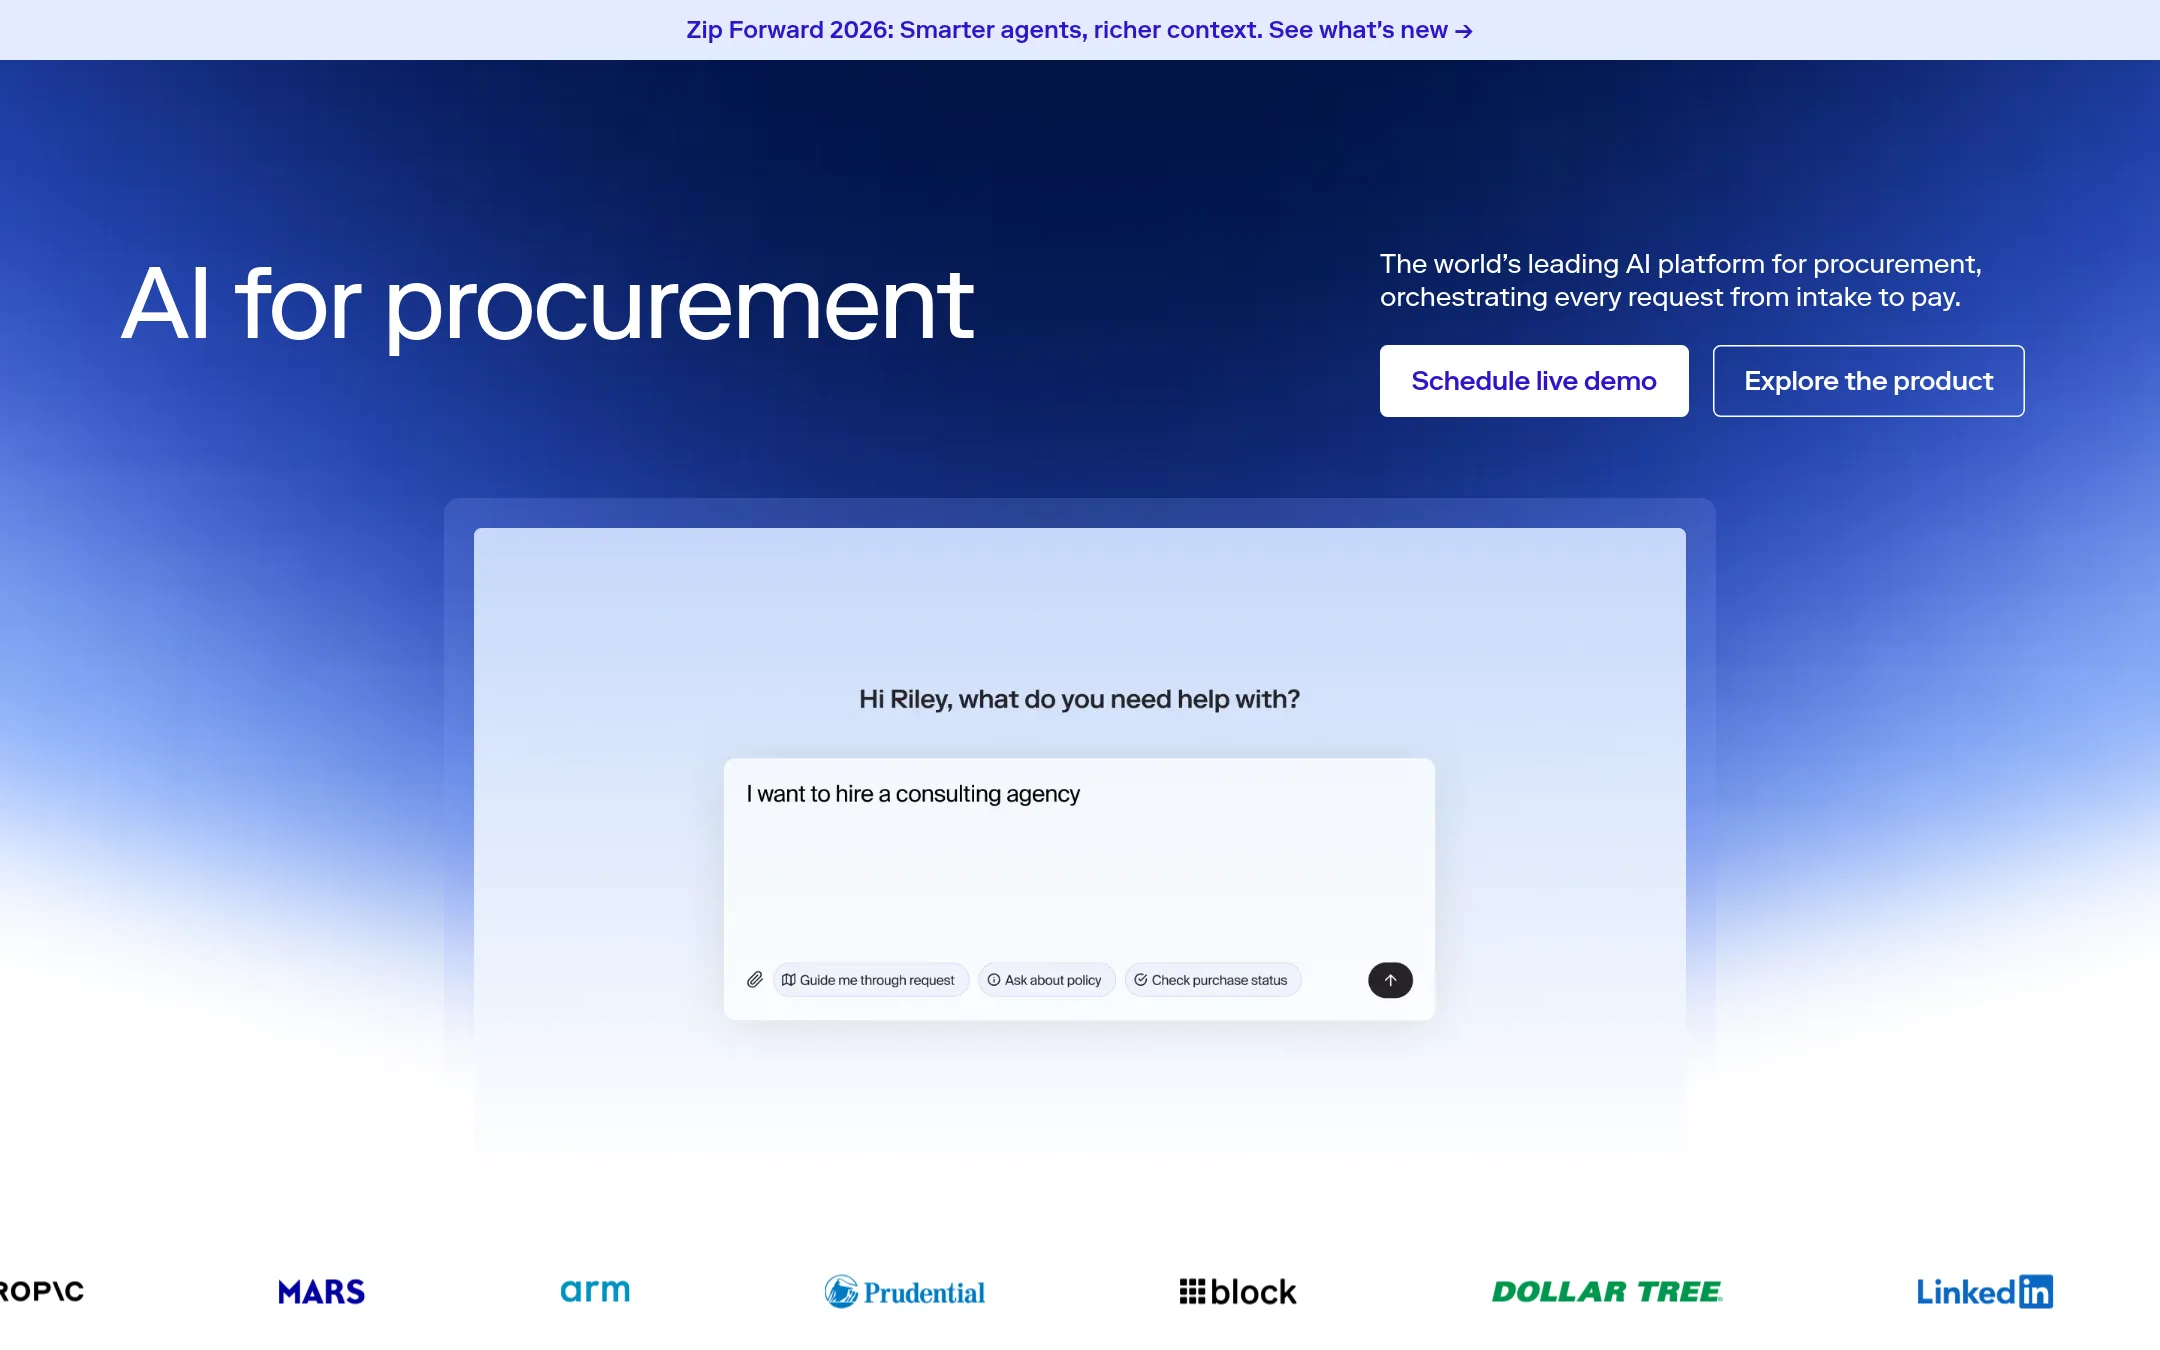
Zip is a procurement orchestration platform that manages the entire intake-to-pay process, including purchasing, invoicing, contracts, and supplier risk. You would choose it over Klarna if you need to control and automate B2B spending across a large organization, not offer consumer financing at checkout.
Where it is strong
- AI-driven intake-to-pay automation reduces manual procurement work
- Includes contract orchestration, sourcing, and supplier onboarding in one platform
- Trusted by large enterprises like OpenAI, Dollar Tree, and T-Mobile
Where it falls short
- No consumer-facing payment options like Klarna's installment plans
- Pricing is not transparent and likely requires a custom quote
- Pricing:
- Pricing is not published on the site.
- CNot published
7.Clearpay
Best for: US retailers and shoppers who want a straightforward BNPL option with a strong consumer app and in-store availability.
- Pricing
- Not published
- Category
- Other
Clearpay is Afterpay's US brand, offering pay-over-time options at checkout including interest-free pay in 4 and longer installment plans. Choose it over Klarna if you want a simpler, app-first BNPL experience with no late fees when you pay on time.
Where it is strong
- No late fees when you pay on time
- Pay in 4 interest-free or over 3, 6, 12, 24 months
- Available online and in-store at partner brands
Where it falls short
- Pricing for merchants is not disclosed publicly
- US-only focus, unlike Klarna's broader global reach
- Pricing:
- Pricing is not published on the site.
- SNot published
8.Splitit
Best for: Merchants and banks that want to offer card-linked installments with high approval rates and no new debt for customers.
- Pricing
- Not published
- Category
- Other
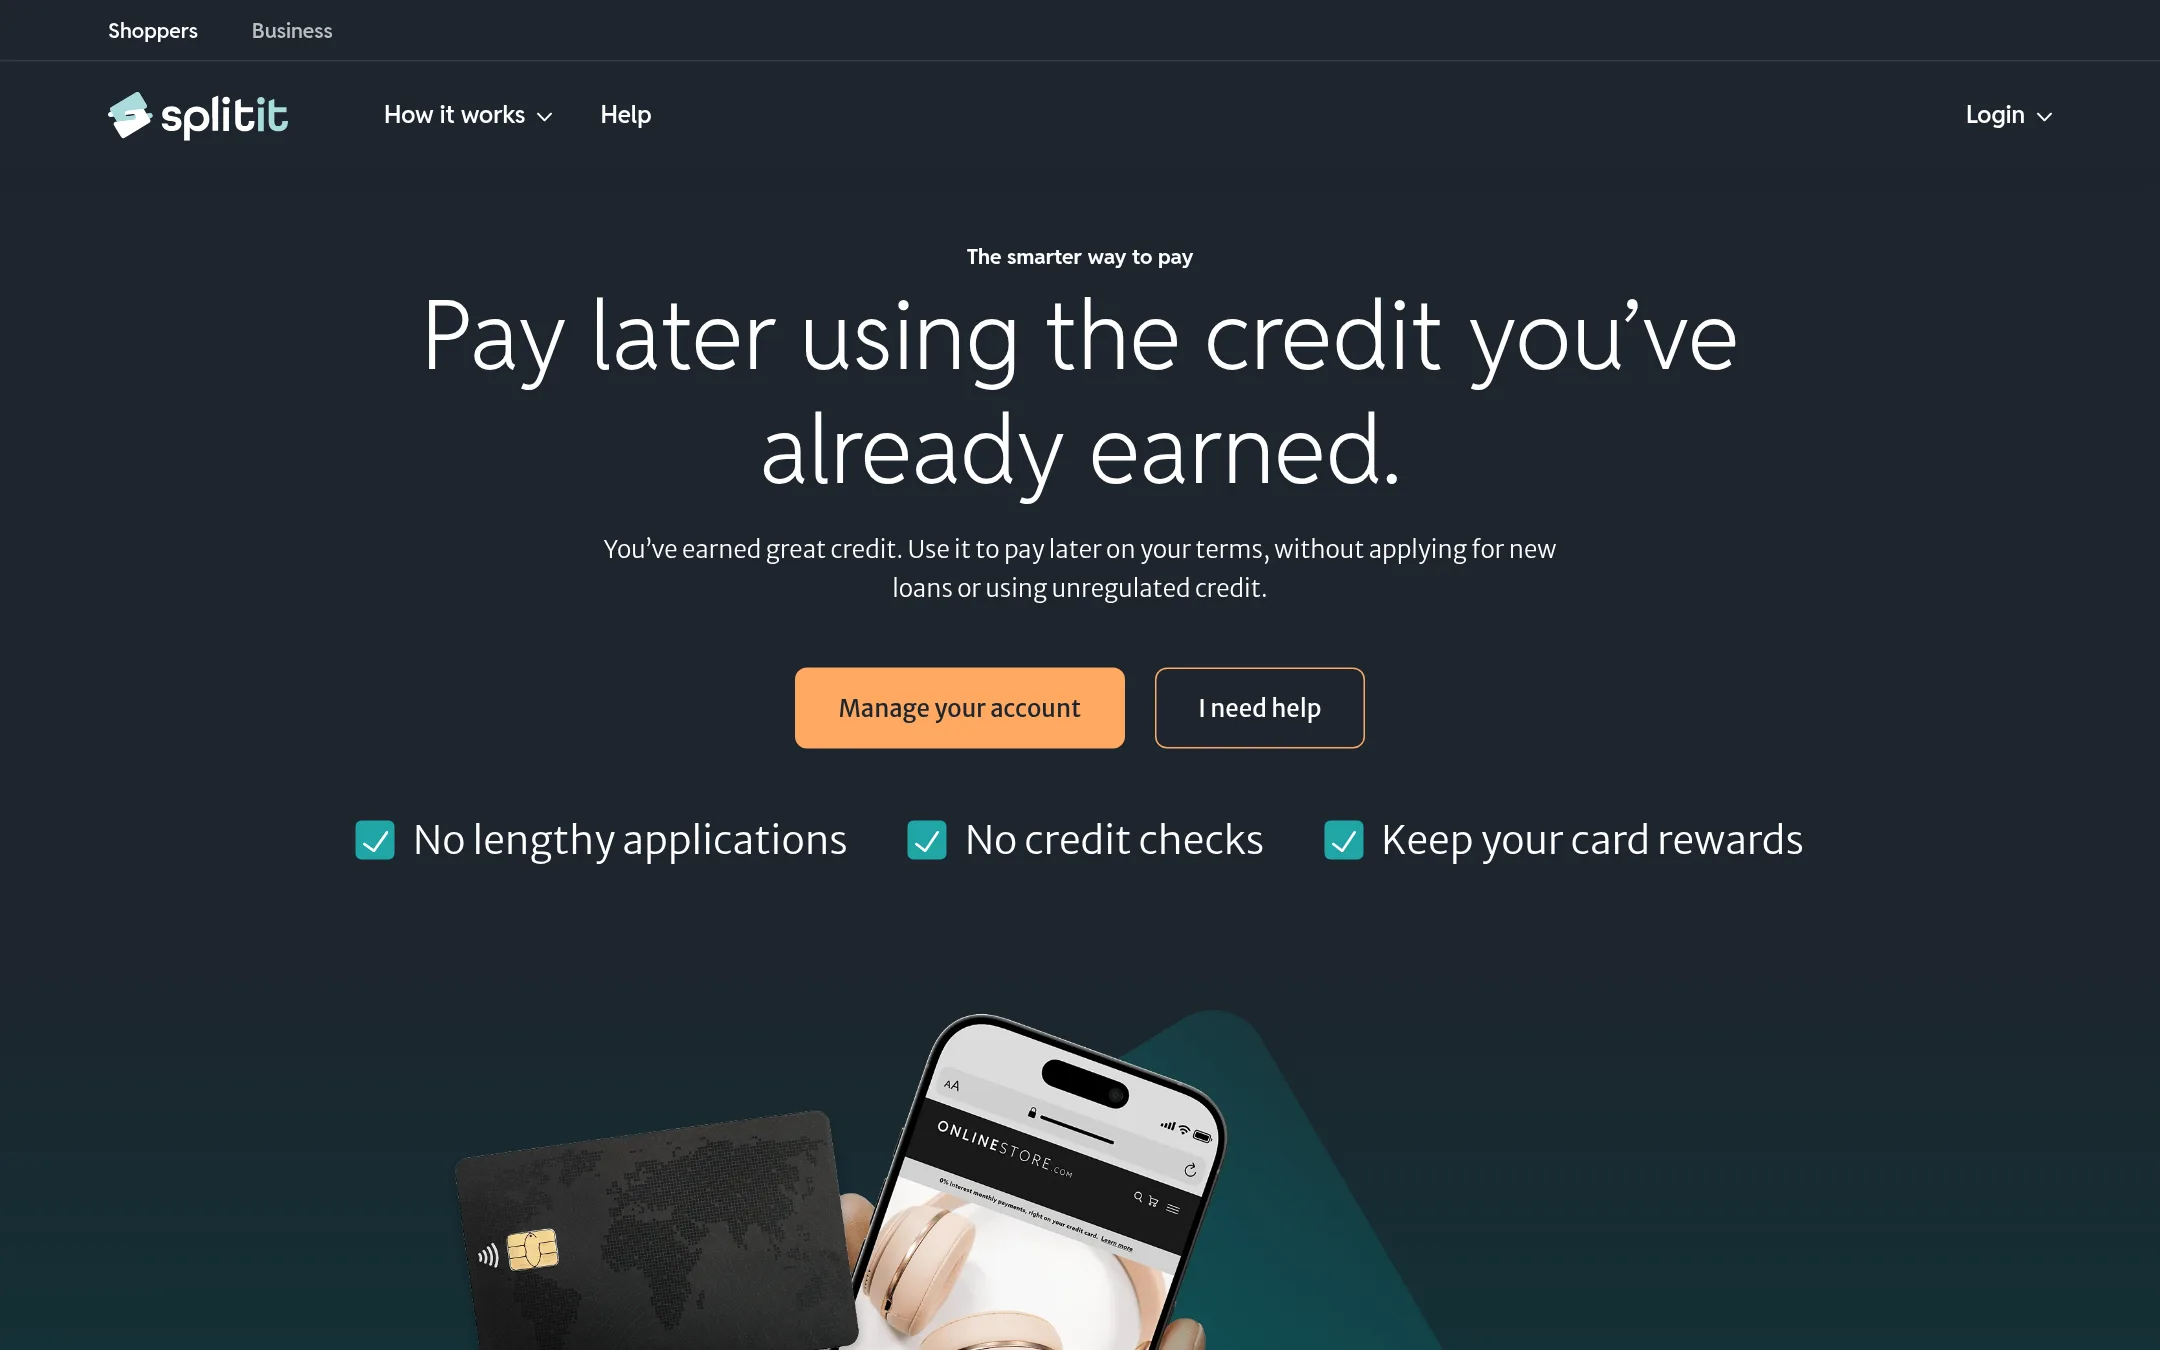
Splitit lets customers pay in installments using their existing credit card, without new loans or credit checks. Choose it over Klarna if you want a white-label solution that keeps your brand at checkout and works with your existing processor.
Where it is strong
- 85%+ approval rates using existing credit
- White-label checkout preserves your brand
- Customers keep card rewards and protections
Where it falls short
- Requires customers to have a credit card
- Digital wallet installments carry a finance charge
- Pricing:
- Pricing is not published on the site.
- Switching from Klarna:
- Moving from Klarna means replacing a BNPL checkout with a card-linked installment flow, which may require integration with your existing processor.
- Not published
9.Albo
Best for: Mexican founders and small businesses that want a single app for personal finance, payroll cards, and up to 3,000 simultaneous transfers.
- Pricing
- Not published
- Category
- Finance & Accounting
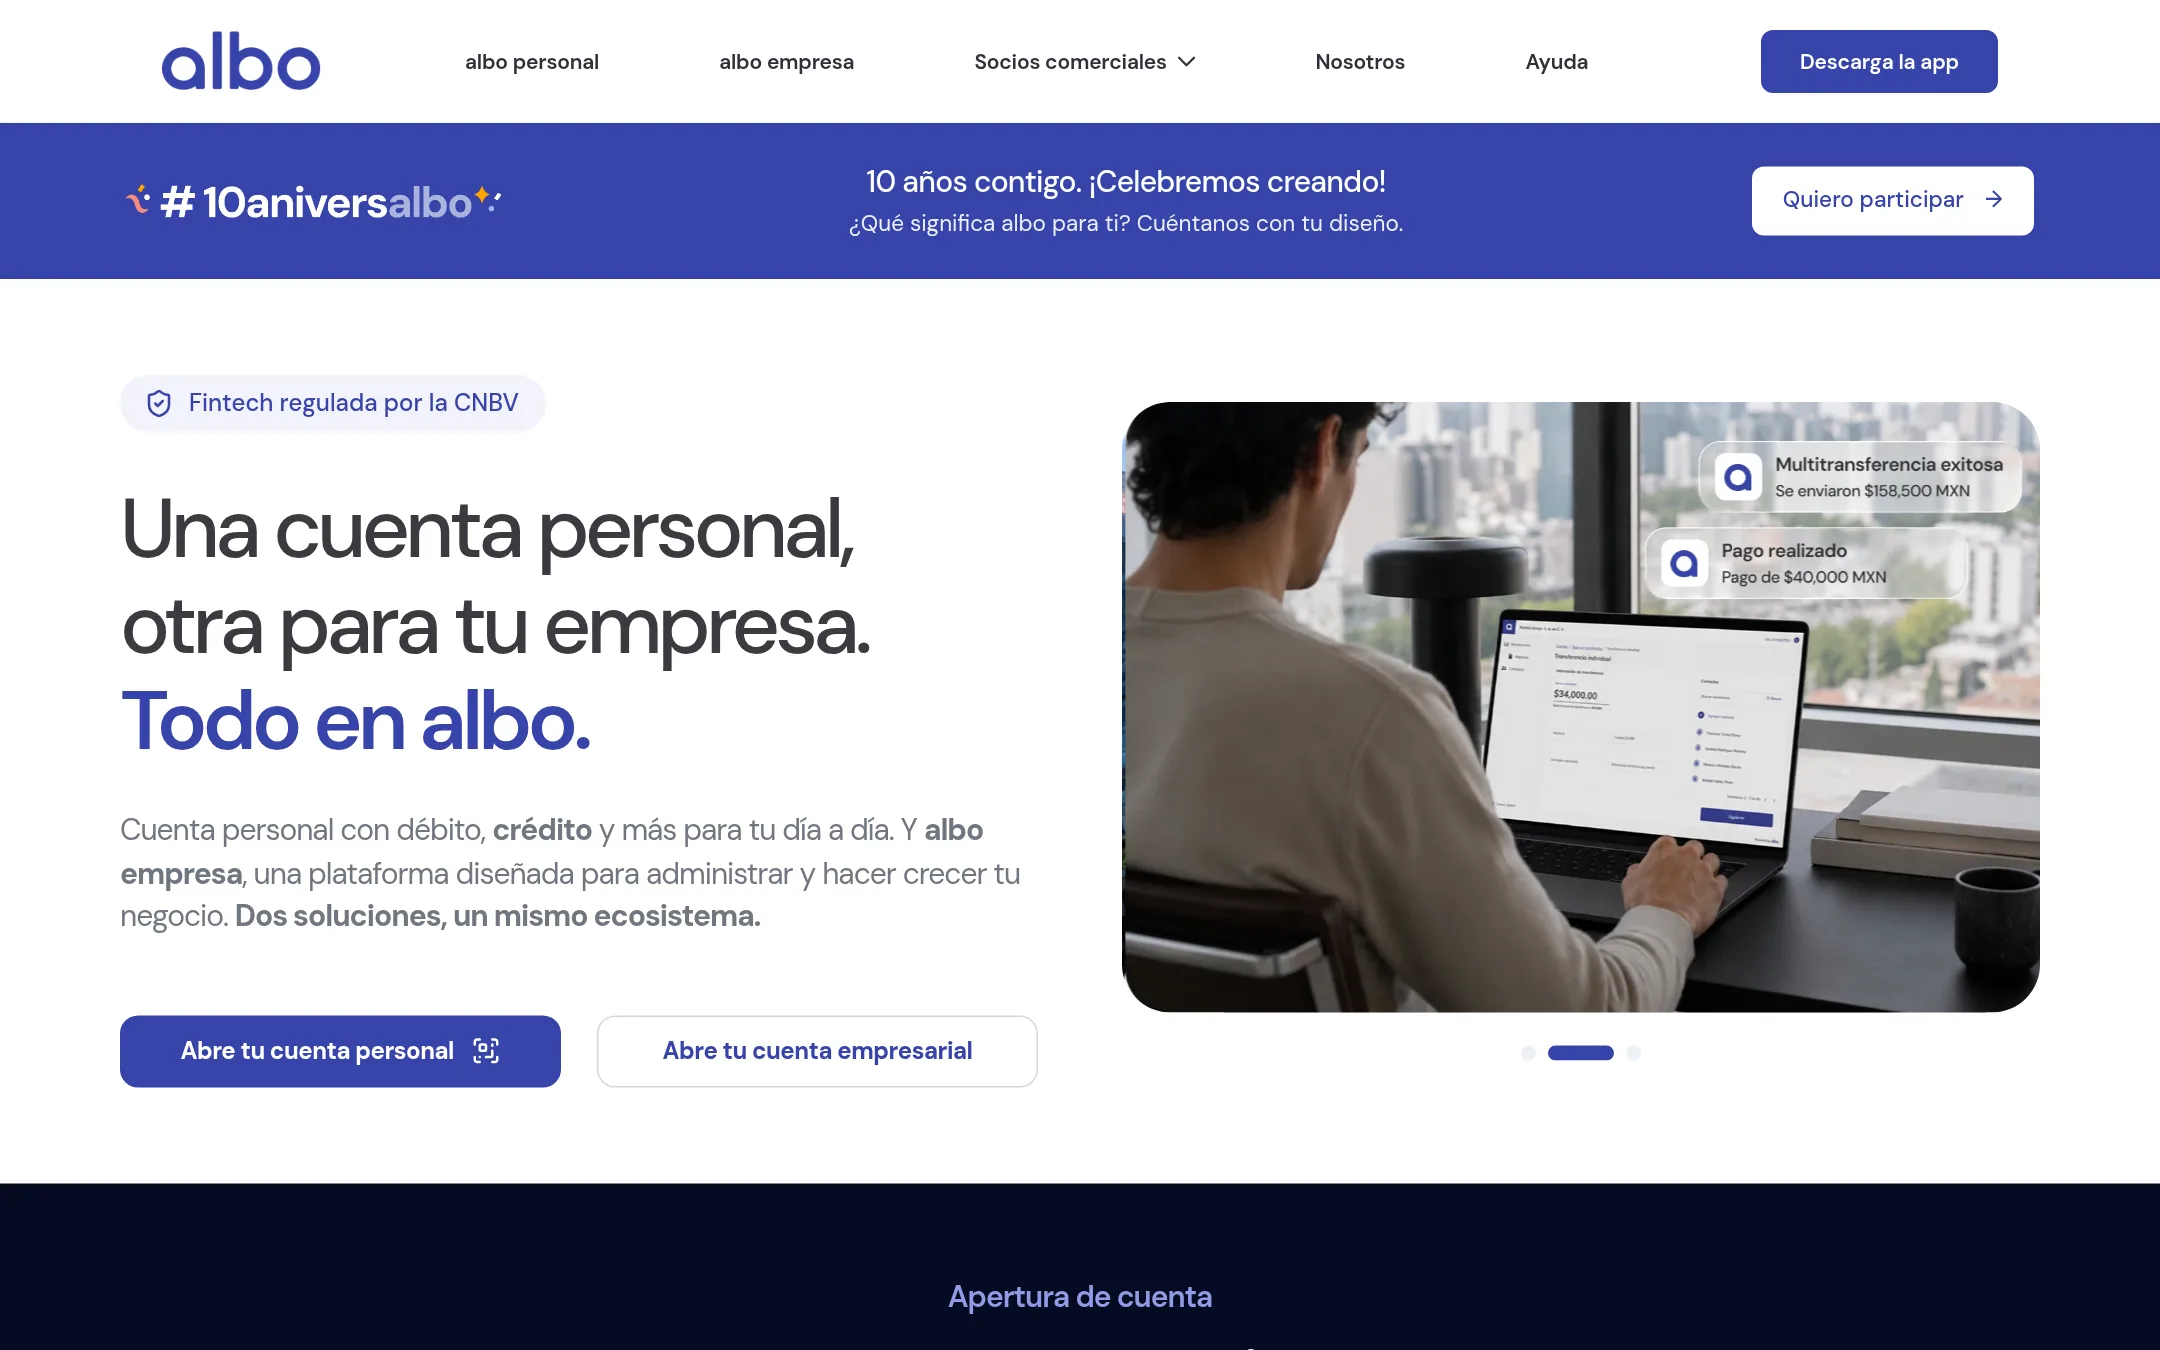
Albo is a Mexican digital banking app that combines personal and business accounts in one place. You would choose it instead of Klarna if you need everyday banking, team cards, and batch payments, not buy-now-pay-later at checkout.
Where it is strong
- Open a personal account in 5 minutes with facial recognition.
- Issue unlimited payroll cards for your team at no cost.
- Make up to 3,000 transactions in one batch without a token.
Where it falls short
- Only available in Mexico, so no global coverage.
- No BNPL or installment payment features like Klarna.
- Pricing:
- Pricing is not published on the site.
- See website
10.Aplazo
E-commerce
Flexible installment payments for shoppers in Mexico
- Not published
11.Atrato
Best for: Mexican retailers that want to offer installment credit to customers without a credit card.
- Pricing
- Not published
- Category
- Finance & Accounting
Atrato is a Mexican fintech that lets shoppers split purchases into installments without a credit card. Choose it over Klarna if you are a merchant in Mexico and want to offer credit to customers who do not have a traditional card.
Where it is strong
- No credit card required for customers
- Regulated by PROFECO in Mexico
- Merchants receive payment quickly
Where it falls short
- Only available in Mexico
- No published pricing or fee structure
- Pricing:
- Pricing is not published on the site.
- See website
12.CredPal
Finance & Accounting
CredPal is a buy now pay later company in Africa that allows…
See more comparisons in E-commerce alternatives.
FAQ
Questions about Klarna alternatives
Which alternative has the most transparent pricing?
None of the listed alternatives publish merchant pricing on their sites. Affirm, Afterpay, Sezzle, and others require you to contact sales for a quote. PayPal mentions custom pricing for eligible businesses with large volumes.
Which alternative is best for international expansion?
PayPal has the broadest global reach, with up to 400M active accounts worldwide. Klarna also has a strong global presence, but among the alternatives, PayPal is the most suitable for multi-market sellers. Affirm, Afterpay, and Sezzle are US-focused.
Can I use these alternatives for in-store payments?
Yes. Afterpay and Clearpay work online and in-store at partner brands. PayPal offers card readers and POS for in-person sales. Sezzle has a Visa card usable anywhere Visa is accepted.
Which alternative has no late fees for customers?
Affirm, Afterpay, Clearpay, and Gerald all advertise no late fees. Sezzle charges no late fees if you pay on time, but may have fees for late payments. Check each provider's terms for specific conditions.
Which alternative is best for B2B procurement?
Zip is the only alternative focused on B2B procurement. It automates intake-to-pay, contract management, and supplier risk. It is not a consumer BNPL option, so choose it if you need to manage organizational spending.
Last updated October 31, 2026.