
Earnin alternatives
12 products compared · Updated November 2, 2026
The short answer
The strongest Earnin alternatives are Dave, Chime, and DailyPay. Dave suits individuals who want up to $500 in quick cash advances without a credit check. Chime suits people who want a fee-free bank account with early direct deposit and overdraft protection. DailyPay suits employers who want to offer on-demand pay as an integrated benefit.
Your shortlist, at a glance
Read the comparisons ↓ DaveNot publishedIndividuals in the US who need quick access to up to $500 between paychecks without a credit check.
 BrigitNot publishedIndividuals who want cash advances plus credit building and overdraft protection in one app
MoneyLion7.5% capped $14.99Individuals who want cash advances plus banking, investing, and credit building in one app.
- CChimeNot publishedIndividuals in the US who want a fee-free bank account with early direct deposit and overdraft protection.
 VaroNot publishedIndividuals who want a free online bank account with built-in cash advances and credit building.
- CCleoNot publishedSupply chain and logistics teams that need to automate EDI/API integrations and manage partner onboarding.
- AAlbertNot publishedIndividuals who want a single app for budgeting, saving, investing, and fraud monitoring, rather than a dedicated earned wage access tool.
- DDailyPayNot publishedEmployers who want to integrate on-demand pay into their existing payroll and HCM systems to improve retention and recruitment.
- PPayActivFree ACH. $2.49+ instaEmployers and workforce platforms in retail, healthcare, logistics, and similar industries that want to embed earned wage access and payroll cards into their existing payroll and HCM systems.
- FFlexWageNot publishedEmployers who want to integrate earned wage access, pay cards, and tip management into their payroll and HR stack.
 CurrentNot publishedPeople who want a mobile bank account with paycheck advances, early pay, and credit building in one place.
 Gerald Technologies, IncNot publishedPeople who need cash advances tied to everyday purchases and want rewards for paying on time
About Earnin and its alternatives
Earnin is an app that gives you access to the pay you have already earned, before payday. It is known for letting you get up to $200 of your upcoming paycheck today, with no mandatory fees or interest, and up to $1,500 per pay period when you connect direct deposit.
When comparing alternatives, weigh the pricing structure, including fees for instant transfers and membership. Consider which regions and banking systems each product supports. Check whether the product integrates with your existing payroll or bank. Look at support options and contract terms, especially for employer-integrated tools.
Explore the alternatives
- Not published
1.Dave
Best for: Individuals in the US who need quick access to up to $500 between paychecks without a credit check.
- Pricing
- Not published
- Category
- Finance & Accounting
Dave gives you access to up to $500 of your paycheck before payday, with no credit check, interest, or late fees. It uses CashAI to analyze your income and spending patterns to determine eligibility. Choose Dave if you want a straightforward cash advance app with a larger maximum than Earnin's $200 daily limit.
Where it is strong
- No credit check or impact on your credit score.
- No interest or late fees on ExtraCash advances.
- Up to $500 in as little as 5 minutes.
Where it falls short
- Requires the mobile app for all services.
- Eligibility is based on proprietary CashAI analysis, not transparent.
- Pricing:
- Pricing is not published on the site.
- Not published
2.Brigit
Best for: Individuals who want cash advances plus credit building and overdraft protection in one app
- Pricing
- Not published
- Category
- Finance & Accounting
Brigit offers cash advances between $25 and $500, plus credit building and overdraft alerts. Choose it over Earnin if you want credit-building tools and identity theft protection alongside early wage access.
Where it is strong
- No credit check for advances
- Credit building while you save
- Overdraft prediction alerts
Where it falls short
- Advance limit is lower than Earnin's
- No mention of instant transfer fees
- Pricing:
- Pricing is not published on the site.
- 7.5% capped $14.99
3.MoneyLion
Best for: Individuals who want cash advances plus banking, investing, and credit building in one app.
- Pricing
- 7.5% capped $14.99
- Category
- Finance & Accounting
MoneyLion is a broader financial app that includes cash advances, banking, investing, and credit building. You would choose it over Earnin if you want more than just early paycheck access and prefer a single app for multiple financial services.
Where it is strong
- Get up to $500 cash advances with Instacash
- Includes banking, investing, and credit building tools
- No mandatory fees for standard Instacash delivery
Where it falls short
- Cash advance fees are higher than Earnin's optional tips
- Credit Builder Plus requires a monthly membership fee
- Pricing:
- Instacash advances cost a standard delivery fee of 7.5% of the advance amount, capped at $14.99, or 9% for external accounts. Optional Turbo delivery is available. Credit Builder Plus membership is $19.99 per month.
- Switching from Earnin:
- Switching from Earnin involves setting up a MoneyLion account and linking your bank, but you can continue using Earnin for lower-cost advances if you prefer.
- CNot published
4.Chime
Best for: Individuals in the US who want a fee-free bank account with early direct deposit and overdraft protection.
- Pricing
- Not published
- Category
- Finance & Accounting
Chime is a full fee-free checking and savings account with early pay access, not just a cash advance app. You'd choose it over Earnin if you want banking, savings, and credit building in one place, plus up to $200 fee-free overdraft.
Where it is strong
- Fee-free checking and savings with no minimum balance
- Early payday access up to two days with direct deposit
- SpotMe overdraft up to $200 with no fees
Where it falls short
- Requires opening a Chime account, not just linking your bank
- Early pay access depends on direct deposit setup
- Pricing:
- Pricing is not published on the site.
- Not published
5.Varo
Best for: Individuals who want a free online bank account with built-in cash advances and credit building.
- Pricing
- Not published
- Category
- Finance & Accounting
Varo is a full online bank that includes cash advances up to $250, early paycheck access, and a line of credit up to $2,000. You would choose Varo instead of Earnin if you want banking services and borrowing options in one app, not just earned wage access.
Where it is strong
- No monthly fees or minimum balance
- Cash advances up to $250, with potential to grow to $700
- Build credit with the Varo Visa Believe Card
Where it falls short
- Cash advance limit is lower than Earnin's $1,500 per pay period
- Requires a Varo bank account to use the advance features
- Pricing:
- Pricing is not published on the site.
- CNot published
6.Cleo
Best for: Supply chain and logistics teams that need to automate EDI/API integrations and manage partner onboarding.
- Pricing
- Not published
- Category
- Other
Cleo is a B2B integration platform for EDI and API transactions, not a consumer finance app. You would choose it instead of Earnin if you run a supply chain or logistics operation and need to automate trading partner onboarding and transaction visibility.
Where it is strong
- AI-assisted mapping and guided setup speed up partner onboarding.
- End-to-end visibility across ERP, TMS, and WMS systems.
- High renewal rate (95%) and strong G2 leader status.
Where it falls short
- No consumer-facing features like earned wage access.
- Requires a demo call. No self-serve signup.
- Pricing:
- Pricing is not published on the site.
- ANot published
7.Albert
Best for: Individuals who want a single app for budgeting, saving, investing, and fraud monitoring, rather than a dedicated earned wage access tool.
- Pricing
- Not published
- Category
- Other
Albert is a broader personal finance app that combines budgeting, saving, investing, and identity protection. You would choose it over Earnin if you want one tool to manage your whole financial life, not just early access to earned wages.
Where it is strong
- Combines budgeting, saving, investing, and identity protection in one app.
- Genius AI assistant can automate transfers, create budgets, and plan travel.
- Offers cash back on spending, early payday, and fee-free ATMs.
Where it falls short
- No dedicated earned wage access feature like Earnin's real-time paycheck advances.
- Pricing for Genius and other premium features is not disclosed on the site.
- Pricing:
- Pricing is not published on the site.
- DNot published
8.DailyPay
Best for: Employers who want to integrate on-demand pay into their existing payroll and HCM systems to improve retention and recruitment.
- Pricing
- Not published
- Category
- Other
DailyPay is an employer-integrated earned wage access platform that lets employees get paid as they work. Choose it over Earnin if you're an employer looking to offer on-demand pay as a benefit, rather than a worker seeking a standalone app.
Where it is strong
- Integrates with existing payroll and HCM systems
- Enterprise-grade security and reliability
- Financial wellness tools for employees
Where it falls short
- Pricing not disclosed publicly
- Requires employer participation, not a consumer app
- Pricing:
- Pricing is not published on the site.
- PFree ACH. $2.49+ insta
9.PayActiv
Best for: Employers and workforce platforms in retail, healthcare, logistics, and similar industries that want to embed earned wage access and payroll cards into their existing payroll and HCM systems.
- Pricing
- Free ACH. $2.49+ insta
- Category
- Other
PayActiv is an earned wage access platform that employers integrate into their payroll systems, letting workers access wages they've already earned. Choose PayActiv over Earnin if you're an employer or workforce platform that wants to offer EWA, payroll cards, and financial wellness tools as a branded benefit, rather than a consumer app employees download individually.
Where it is strong
- Employer-funded model means no cost to employees for standard ACH transfers.
- Offers payroll cards, off-cycle pay, tips and mileage, and financial wellness tools beyond basic EWA.
- Integrates with payroll and HCM providers, so it works alongside existing systems rather than as a standalone app.
Where it falls short
- Instant transfer fees apply unless you meet the qualifying direct deposit threshold.
- Access is tied to your employer's participation, so it's not available to individual users on their own.
- Pricing:
- ACH transfers are free and arrive in 1-3 business days. Instant transfers to a Payactiv Visa Card are free with qualifying direct deposit of $200+ per pay period, otherwise $2.49. Non-Payactiv debit or payroll card transfers cost $3.49. Cash App transfers cost
- FNot published
10.FlexWage
Best for: Employers who want to integrate earned wage access, pay cards, and tip management into their payroll and HR stack.
- Pricing
- Not published
- Category
- Other
FlexWage provides on-demand pay, instant tip deposit on pay cards, and pay card services for employers. Choose it over Earnin if you're an employer looking to offer earned wage access and financial wellness tools to your workforce, rather than an individual app user.
Where it is strong
- Offers multiple pay solutions: on-demand pay, pay cards, and instant tip deposit
- Includes financial wellness tools like Sum180 for employees
- Designed for employer partnerships, not just individual users
Where it falls short
- No public pricing, so you must request a quote
- Requires employer participation, so individual workers can't sign up directly
- Pricing:
- Pricing is not published on the site.
- Not published
11.Current
Best for: People who want a mobile bank account with paycheck advances, early pay, and credit building in one place.
- Pricing
- Not published
- Category
- Finance & Accounting
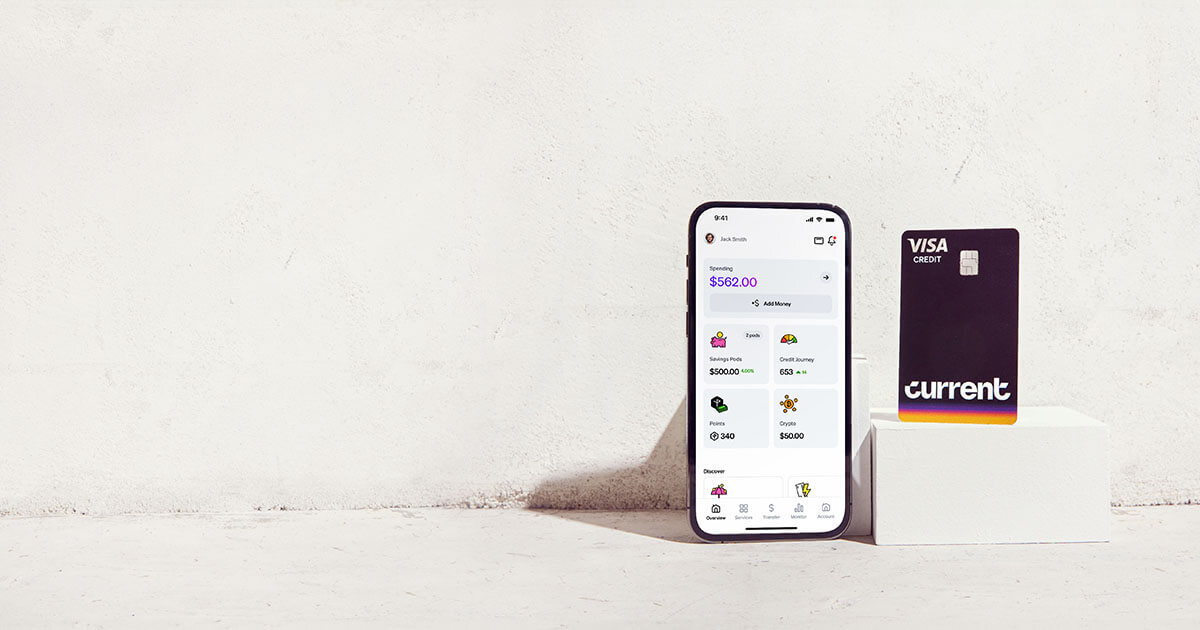
Current is a banking app that offers paycheck advances up to $1,000, early direct deposit, and credit building. You would choose it over Earnin if you want a full banking experience with fee-free overdraft and savings bonuses, not just early wage access.
Where it is strong
- Advances up to $1,000, higher than Earnin's $200 standard
- Fee-free overdraft and 40,000+ fee-free ATMs
- Credit building with potential score increase
Where it falls short
- Paycheck advance eligibility is at Current's discretion
- Some fees apply for ATM, late payment, and foreign transactions
- Pricing:
- Pricing is not published on the site.
- Not published
12.Gerald Technologies, Inc
Best for: People who need cash advances tied to everyday purchases and want rewards for paying on time
- Pricing
- Not published
- Category
- Finance & Accounting
Gerald offers cash advances and Buy Now, Pay Later for household essentials, with no fees or interest. Choose it over Earnin if you want to combine earned wage access with shopping for essentials and earning store rewards.
Where it is strong
- No fees, interest, or late charges on advances and BNPL
- Free bank transfers for cash advances
- Earn store rewards and play games for extra perks
Where it falls short
- Cash advances require using part for purchases on Gerald's store
- Limited to household items and phone plans, not general spending
- Pricing:
- Pricing is not published on the site.
See more comparisons in Finance & Accounting alternatives.
FAQ
Questions about Earnin alternatives
What is the maximum cash advance I can get from these alternatives?
Dave offers up to $500, Current offers up to $1,000, and Varo offers up to $250 that can grow to $700. MoneyLion offers up to $500. Earnin's standard is $200, but it can go up to $1,500 per pay period with direct deposit.
Are there any fees for using these cash advance apps?
Gerald charges no fees, interest, or late charges. Dave has no interest or late fees. MoneyLion charges a standard delivery fee of 7.5% of the advance amount, capped at $14.99, or 9% for external accounts. PayActiv charges $2.49 for instant transfers unless you have qualifying direct deposit, and $3.49 for non-Payactiv debit cards.
Do I need to have a bank account with the provider to use the cash advance feature?
Yes for some. Chime, Varo, and Current require you to open their bank account to use their advance features. Dave and Brigit work as standalone apps that link to your existing bank. DailyPay, PayActiv, and FlexWage require employer participation, so you need your employer to sign up.
Can I use these alternatives if I have bad credit?
Dave and Brigit do not require a credit check. Earnin also does not check credit. Chime, Varo, and Current are bank accounts, so they may check your banking history but not your credit score. MoneyLion does not mention a credit check for Instacash.
Which alternative is best for employers who want to offer earned wage access?
DailyPay and PayActiv are designed for employers. DailyPay integrates with existing payroll and HCM systems. PayActiv offers payroll cards and financial wellness tools. FlexWage also targets employers with on-demand pay and tip management. These are not consumer apps, so individual workers cannot sign up directly.
Last updated November 2, 2026.