Sivo alternatives
8 products compared · Updated October 19, 2026
The short answer
For founders and operators comparing Sivo alternatives, the strongest options are Stripe for broad payment infrastructure, Pipe for embedded financing with vertical SaaS risk models, and Clearco for US DTC ecommerce brands needing fast non-dilutive funding. Stripe suits businesses that need global payments and subscriptions, Pipe fits platforms wanting to embed capital tools, and Clearco is ideal for ecommerce brands with revenue over $100k per month.
Your shortlist, at a glance
Read the comparisons ↓ Stripe2.9% + 30¢Online businesses of any size that need to accept payments globally and manage subscriptions, rather than embed lending into their platform.
 BrexCustom quoteStartups and mid-sized companies that want corporate cards, expense management, and automated accounting in one platform.
 PipeNot publishedVertical SaaS, payment facilitators, and marketplaces that want to embed financing and cash-flow tools with industry-specific risk models.
 AaveNot publishedCrypto-native teams and DeFi builders who want to earn yield or borrow against digital assets without a centralized lending partner.
 LiveRampFrom $20,000/yrEnterprise marketing teams that need identity resolution, data collaboration, and media measurement across many ad destinations.
 ClearcoNot publishedUS-incorporated DTC ecommerce brands with 6+ months of revenue over $100k/month that want fast, non-dilutive funding without collateral requirements.
 Maple FinanceNot publishedInstitutions and non-US investors seeking onchain secured lending and yield products with blockchain-verified transparency.
EarninNot publishedHourly or salaried employees in the US who want to access earned wages before payday without borrowing from a lender.
About Sivo and its alternatives
Sivo is a debt-as-a-service platform that lets companies lend money to their users at scale. It turns pending payouts into instant cash, provides advances against future payments, and offers revolving credit facilities. Sivo supports seven currencies and uses AI for application and account management, with a focus on gig workers, merchants, and creators.
When comparing alternatives, weigh pricing structure, geographic reach, integrations, support, and contract terms. Some products publish transparent pricing while others require sales calls. Consider whether you need embedded lending, spend management, or just payment processing. Check if the product supports your region and integrates with your existing stack.
Explore the alternatives
- 2.9% + 30¢
1.Stripe
Best for: Online businesses of any size that need to accept payments globally and manage subscriptions, rather than embed lending into their platform.
- Pricing
- 2.9% + 30¢
- Category
- Finance & Accounting
Stripe is a broad payments platform that handles card processing, billing, and money movement. Choose it over Sivo when you need a general-purpose financial infrastructure for accepting payments and managing revenue, not a specialized debt-as-a-service product for lending to your users.
Where it is strong
- Processes payments in 135+ currencies and supports 100+ payment methods.
- Handles subscriptions, invoicing, and in-person payments with one platform.
- Offers AI-powered fraud protection and dispute management tools.
Where it falls short
- Does not offer embedded lending or debt facilities like Sivo does.
- Pricing for advanced features like Adaptive Acceptance is custom and not published.
- Pricing:
- Standard pricing is 2.9% + 30¢ per successful transaction for domestic cards, with custom pricing for higher volume.
- Custom quote
2.Brex
Best for: Startups and mid-sized companies that want corporate cards, expense management, and automated accounting in one platform.
- Pricing
- Custom quote
- Category
- Finance & Accounting
Brex is a spend management platform with corporate cards, expense tracking, bill pay, and banking. Choose it over Sivo if your main need is controlling company spending and automating finance operations, not lending capital to your users.
Where it is strong
- Global card acceptance in 210+ countries and local-currency cards in 50+ countries
- AI-powered expense automation and accounting integrations
- Up to 3.92% yield on business account balances
Where it falls short
- No embedded lending or payout advances for your users
- Pricing requires contacting sales. No transparent rates
- Pricing:
- Pricing is not published on the site. Plans are Essentials, Premium, and Enterprise with custom quotes.
- Not published
3.Pipe
Best for: Vertical SaaS, payment facilitators, and marketplaces that want to embed financing and cash-flow tools with industry-specific risk models.
- Pricing
- Not published
- Category
- Finance & Accounting
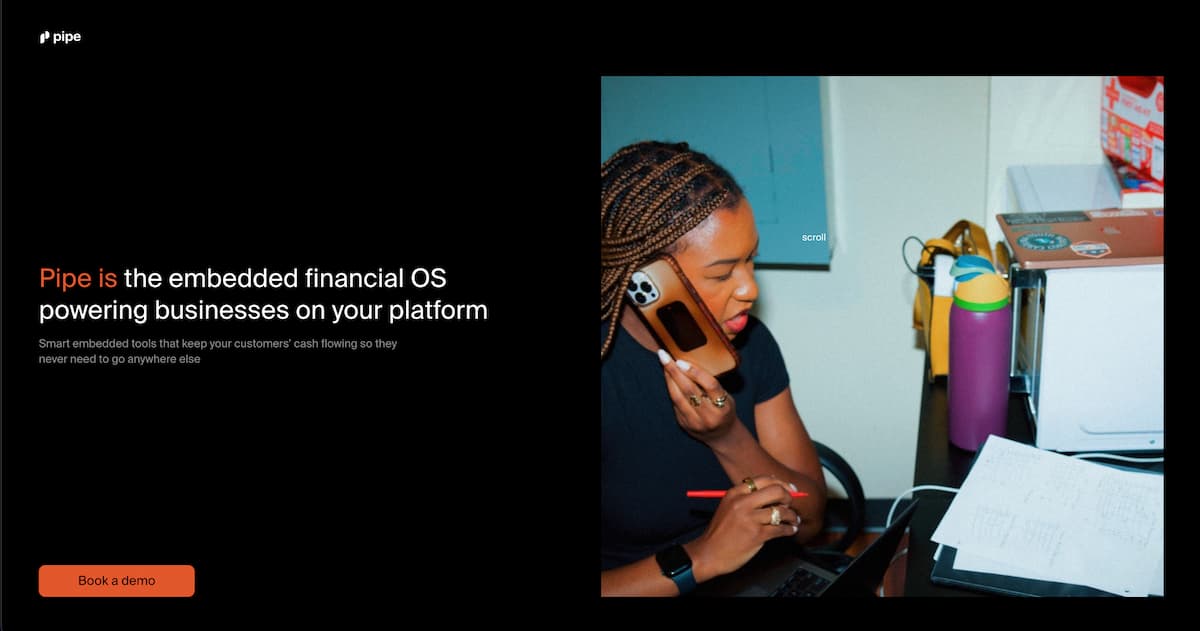
Pipe is an embedded financial OS that lets platforms offer capital and cash-flow tools using their own customer data. Choose it over Sivo when you want a single integration for multiple financial products and a partner-led GTM approach, rather than Sivo's debt-as-a-service focus on lending infrastructure.
Where it is strong
- Single integration for capital and cash-flow tools
- Industry-specific risk models for vertical SaaS and marketplaces
- Strong partner support and GTM assistance
Where it falls short
- Pricing is not transparent
- No mention of instant payouts or AI-based capital access like Sivo
- Pricing:
- Pricing is not published on the site.
- Not published
4.Aave
Best for: Crypto-native teams and DeFi builders who want to earn yield or borrow against digital assets without a centralized lending partner.
- Pricing
- Not published
- Category
- Finance & Accounting
Aave is a decentralized, non-custodial lending protocol where users supply or borrow crypto assets directly through smart contracts. Choose it over Sivo if you want open, onchain liquidity markets with no platform intermediary and are comfortable managing collateral yourself.
Where it is strong
- Non-custodial: you keep control of your assets
- Open protocol with 6+ years of uninterrupted operation
- Large network: $31.6B net deposits and 2.5M+ users
Where it falls short
- Requires overcollateralization, so you must lock up more than you borrow
- No fiat payouts or invoice advances like Sivo offers
- Pricing:
- Pricing is not published on the site.
- From $20,000/yr
5.LiveRamp
Best for: Enterprise marketing teams that need identity resolution, data collaboration, and media measurement across many ad destinations.
- Pricing
- From $20,000/yr
- Category
- Marketing & Sales
LiveRamp is a data collaboration and identity platform for marketing, not a lending or payout infrastructure product. You would choose it instead of Sivo if your problem is connecting customer data across ad platforms and measuring campaign performance, not providing instant capital to your users.
Where it is strong
- Connects to major ad platforms like Disney, Hulu, Pinterest, Snap, Spotify, Netflix, and TikTok.
- Consumption-based pricing scales with usage and unlocks volume discounts.
- Recognized by analysts and partners, including Google Cloud and Snowflake.
Where it falls short
- Pricing starts at $20,000 per year, which is out of reach for small teams.
- Designed for marketing use cases, not lending, payouts, or capital infrastructure.
- Pricing:
- Pricing starts at $20,000 per year for Standard, $150,000 for Premier, and $360,000 for Enterprise, with annual token commitments and add-ons.
- Not published
6.Clearco
Best for: US-incorporated DTC ecommerce brands with 6+ months of revenue over $100k/month that want fast, non-dilutive funding without collateral requirements.
- Pricing
- Not published
- Category
- Finance & Accounting
Clearco provides non-dilutive revenue-based financing for DTC ecommerce brands, with funding up to $10 million and terms up to 12 months. Choose it over Sivo if you run a US-based ecommerce business that needs working capital for inventory or marketing without giving up equity or dealing with platform-level lending infrastructure.
Where it is strong
- No collateral or all-asset lien required
- Rolling funding capacity replenishes as you pay
- Application reviewed in as little as 24 hours
Where it falls short
- Only for US-incorporated DTC brands with $100k+ monthly revenue
- Pricing details not disclosed publicly
- Pricing:
- Pricing is not published on the site.
- Not published
7.Maple Finance
Best for: Institutions and non-US investors seeking onchain secured lending and yield products with blockchain-verified transparency.
- Pricing
- Not published
- Category
- Finance & Accounting
Maple Finance is an onchain asset management platform for digital asset lending and yield, not a payout or working capital tool. Choose it instead of Sivo if you are an institution or global investor looking for overcollateralized crypto loans and yield, not embedded payout advances for gig workers or merchants.
Where it is strong
- Full transparency for loans and collateral, verifiable on the blockchain.
- Institutional-grade risk management with overcollateralized loans.
- Global client support and solutions for both institutions and individuals.
Where it falls short
- Focused on crypto lending, not payout advances or embedded capital for platforms.
- Yield products are open to non-US investors only, limiting geographic reach.
- Pricing:
- Pricing is not published on the site.
- Not published
8.Earnin
Best for: Hourly or salaried employees in the US who want to access earned wages before payday without borrowing from a lender.
- Pricing
- Not published
- Category
- Finance & Accounting
EarnIn is a consumer app that gives workers early access to wages they've already earned, up to $200 per day or $1,500 per pay period. Choose it instead of Sivo if you're an individual employee who wants faster access to your own paycheck, not a platform looking to embed lending infrastructure.
Where it is strong
- No mandatory fees or interest charges for standard transfers
- Access up to $200 of earned wages per day, or $1,500 per pay period with direct deposit
- Instant transfers available for a small fee
Where it falls short
- Designed for individuals, not for platforms to embed into their own products
- Limited to earned wage access, not revolving credit facilities or invoice advances
- Pricing:
- Pricing is not published on the site.
See more comparisons in Finance & Accounting alternatives.
FAQ
Questions about Sivo alternatives
What is the main difference between Sivo and Stripe?
Sivo focuses on embedded lending and debt facilities, while Stripe is a broad payments platform. Choose Stripe if you need to accept payments globally and manage subscriptions, not if you want to lend to your users.
Which alternative is best for a startup that needs corporate cards and expense management?
Brex is designed for startups and mid-sized companies needing corporate cards, expense tracking, and bill pay. It does not offer embedded lending, so it suits spend management rather than capital provision.
Can I use Pipe if I run a vertical SaaS platform?
Yes, Pipe is built for vertical SaaS, payment facilitators, and marketplaces. It offers industry-specific risk models and a single integration for capital and cash-flow tools, with partner-led GTM support.
What are the eligibility requirements for Clearco?
Clearco requires US incorporation, at least 6 months of revenue, and monthly revenue over $100k. It provides non-dilutive funding up to $10 million with no collateral, and applications are reviewed in as little as 24 hours.
Are there any alternatives that offer transparent pricing?
Stripe publishes standard pricing at 2.9% + 30¢ per transaction, and LiveRamp lists starting prices from $20,000 per year. Most other alternatives, including Brex, Pipe, and Clearco, do not disclose pricing publicly.
Last updated October 19, 2026.