Maple Finance alternatives
12 products compared · Updated November 3, 2026
The short answer
For most businesses, Stripe is the strongest alternative for payment processing and financial infrastructure. Brex suits startups needing corporate cards and spend management. For embedded lending, Sivo is the best fit for platforms wanting to offer instant payouts or revenue-based advances.
Your shortlist, at a glance
Read the comparisons ↓- CCentrifugeNot publishedAsset managers and institutions looking to tokenize real-world assets like funds, credit, or treasuries and access DeFi liquidity.
- GGoldfinchNot publishedSophisticated investors who want onchain exposure to top-tier private credit funds and can accept the platform's wind-down status.
- TTrueFiNot publishedTRU token holders and borrowers navigating the migration to Brila who need community support and updates.
 AaveNot publishedTeams and individuals who want to earn yield or borrow onchain without intermediaries, especially those seeking stablecoin lending with global rates.
- CCompoundNot publishedCrypto holders who want to earn yield or borrow against their assets without going through a professional manager.
- AAlchemixNot publishedIndividual DeFi users and DAOs who want to borrow against ETH or USDC without selling, and prefer automated loan repayment over managed institutional lending.
 SivoNot publishedPlatforms and fintechs that want to offer instant payouts or revenue-based advances to their users without building lending infrastructure.
 BrexNot publishedStartups and growing companies that want corporate cards, expense management, and bill pay in one platform.
 ClearcoNot publishedDTC ecommerce brands in the U.S. with at least $100k monthly revenue that need fast, non-dilutive capital for inventory, purchase orders, or marketing.
EarninNot publishedHourly or salaried employees in the US who want to access earned wages before their next payday.
 PipeNot publishedVertical SaaS, payment facilitators, and marketplaces that want to embed financing and cash-flow tools into their platforms.
 Stripe3.4% + $0.50Online businesses and platforms that need to accept payments, manage subscriptions, or embed financial infrastructure globally.
About Maple Finance and its alternatives
Maple Finance is an onchain asset management platform for digital asset lending and yield. It offers institutional-quality yield from overcollateralized loans and permissioned secured lending for sophisticated allocators. The platform is known for transparency, with all loans and collateral verifiable on the blockchain.
When comparing alternatives, weigh pricing structure, geographic availability, integration effort, and support. Some products publish pricing, while others require contacting sales. Consider whether you need payments, corporate cards, embedded lending, or onchain yield, and match the tool to your specific financial operations.
Explore the alternatives
- CNot published
1.Centrifuge
Best for: Asset managers and institutions looking to tokenize real-world assets like funds, credit, or treasuries and access DeFi liquidity.
- Pricing
- Not published
- Category
- Other
Centrifuge is a full-stack platform for tokenizing real-world assets, aimed at asset managers and investors who want to bring funds, credit, or treasuries onchain. Choose it over Maple Finance if you need to tokenize a broad range of assets beyond digital asset lending, with automated infrastructure and multichain DeFi connectivity.
Where it is strong
- Supports tokenizing any type of real-world asset, not just loans.
- Multichain reach with deep DeFi integrations for liquidity.
- Automates issuance, reporting, and portfolio operations.
Where it falls short
- Pricing is not disclosed, so cost comparison is hard.
- May be more complex for simple lending needs compared to Maple's focused products.
- Pricing:
- Pricing is not published on the site.
- GNot published
2.Goldfinch
Best for: Sophisticated investors who want onchain exposure to top-tier private credit funds and can accept the platform's wind-down status.
- Pricing
- Not published
- Category
- Other
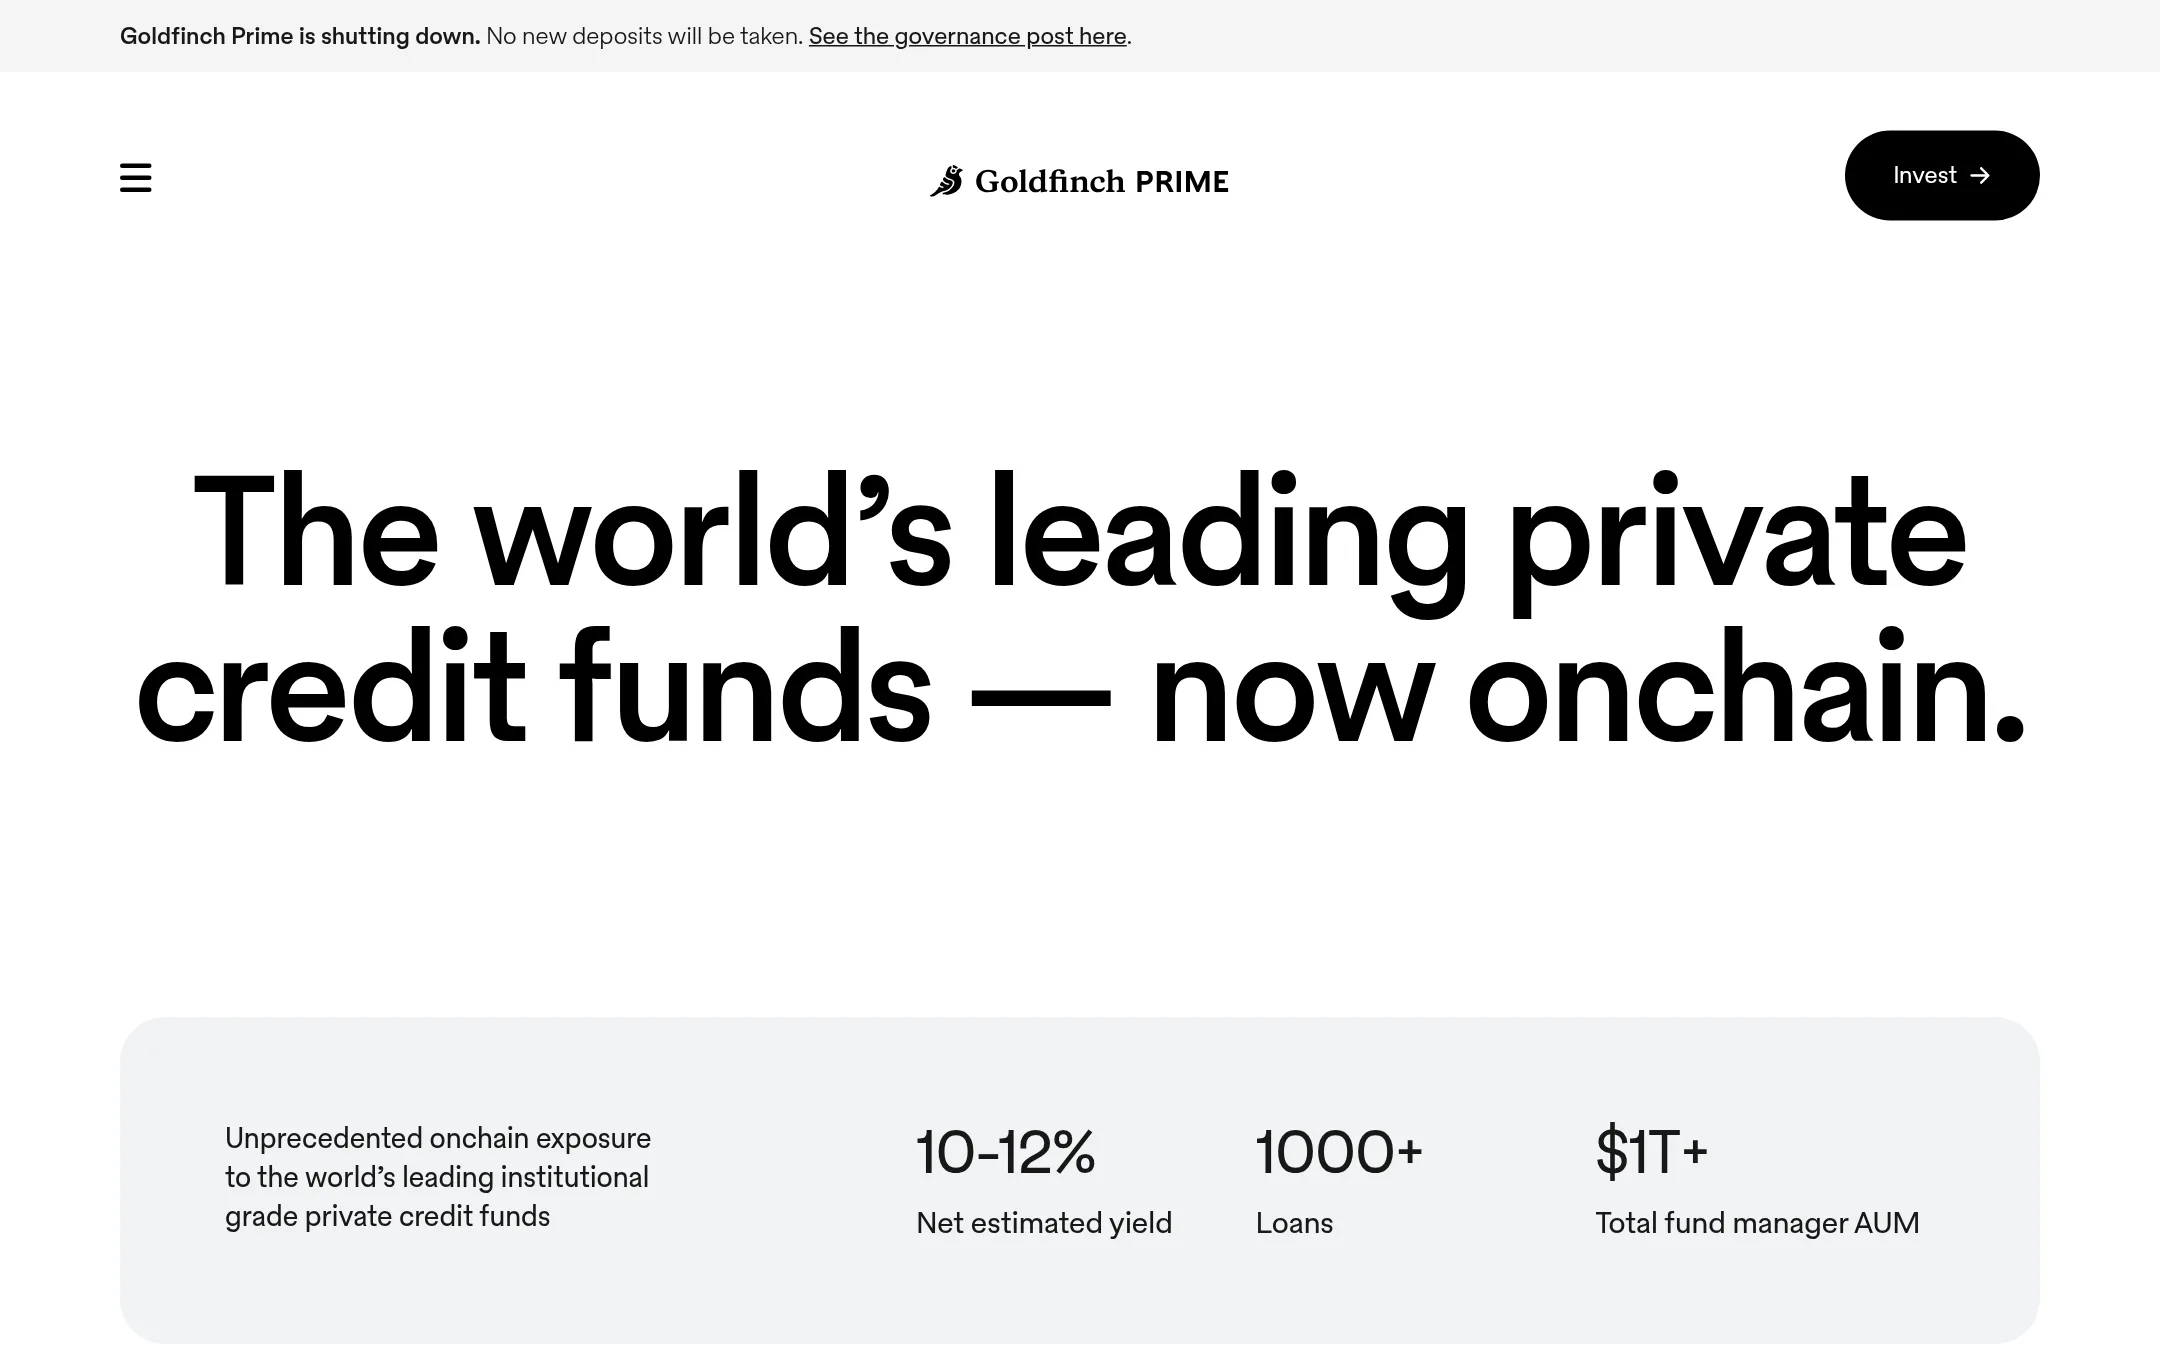
Goldfinch Prime offers onchain access to institutional private credit funds managed by firms like Ares and Apollo. It is a choice for investors seeking diversified exposure to senior secured loans, but it is currently shutting down and not accepting new deposits.
Where it is strong
- Access to funds from Ares, Apollo, and other major managers
- Diversified across 1000+ senior secured loans
- Targets 10-12% net estimated yield
Where it falls short
- Platform is shutting down, no new deposits
- No published pricing or fee details
- Pricing:
- Pricing is not published on the site.
- TNot published
3.TrueFi
Best for: TRU token holders and borrowers navigating the migration to Brila who need community support and updates.
- Pricing
- Not published
- Category
- Other
TrueFi is a community forum for an onchain lending protocol that has transitioned to Brila. Choose it if you are a TRU token holder or borrower looking for migration support and community discussion, not for active lending products.
Where it is strong
- Active community forum with migration guides and updates.
- Direct access to DAO proposals and governance discussions.
- Support for token swaps and migration issues.
Where it falls short
- No active lending or yield products currently offered.
- Forum is focused on migration issues, not ongoing financial services.
- Pricing:
- Pricing is not published on the site.
- Not published
4.Aave
Best for: Teams and individuals who want to earn yield or borrow onchain without intermediaries, especially those seeking stablecoin lending with global rates.
- Pricing
- Not published
- Category
- Finance & Accounting
Aave is a decentralized, non-custodial lending protocol where users supply assets to earn interest or borrow against collateral. Choose Aave instead of Maple Finance if you want open, permissionless access to lending markets without a professional manager, and you are comfortable managing your own risk.
Where it is strong
- Non-custodial: funds stay in smart contracts, not with a manager.
- Open to anyone globally, no permission needed.
- Proven track record: six years of uninterrupted operation and $3.46T lifetime deposits.
Where it falls short
- No professional management or curated loan book like Maple's.
- Rates and collateral ratios are set by governance, not tailored to individual borrowers.
- Pricing:
- Pricing is not published on the site.
- CNot published
5.Compound
Best for: Crypto holders who want to earn yield or borrow against their assets without going through a professional manager.
- Pricing
- Not published
- Category
- Other
Compound is a decentralized lending protocol where users can earn yield by depositing assets and borrow against them, with rates set by the market. Choose Compound instead of Maple Finance if you want a permissionless, self-serve market for digital assets rather than Maple's curated, expert-managed lending products.
Where it is strong
- Instant withdrawals and liquidity access
- Curated collateral assets with transparent risk profiles
- Audited and backed by a bug bounty program
Where it falls short
- No professional management or curated lending pools
- Borrow caps and liquidation penalties may apply
- Pricing:
- Pricing is not published on the site.
- ANot published
6.Alchemix
Best for: Individual DeFi users and DAOs who want to borrow against ETH or USDC without selling, and prefer automated loan repayment over managed institutional lending.
- Pricing
- Not published
- Category
- Other
Alchemix offers self-repaying loans on ETH or USDC with up to 90% LTV and 0% interest, where your collateral keeps earning yield to pay off the debt. Choose it instead of Maple Finance if you want a fully automated, liquidation-free borrowing experience without needing a permissioned institutional lending relationship.
Where it is strong
- Borrow up to 90% LTV with 0% interest
- Collateral keeps earning yield to repay the loan automatically
- No market liquidation risk on loans
Where it falls short
- Only supports ETH and USDC as collateral
- No institutional-grade secured lending or permissioned pools like Maple Finance
- Pricing:
- Pricing is not published on the site.
- Not published
7.Sivo
Best for: Platforms and fintechs that want to offer instant payouts or revenue-based advances to their users without building lending infrastructure.
- Pricing
- Not published
- Category
- Finance & Accounting
Sivo is a debt-as-a-service platform that turns pending payouts into instant cash for gig workers, merchants, and other businesses with verifiable revenue streams. It embeds lending into platforms via APIs, with AI-driven applications and instant funding decisions. Choose Sivo over Maple Finance if you need embedded working capital for your users rather than onchain asset management.
Where it is strong
- AI-powered application and account management, available 24/7
- Supports 7 currencies and generates term sheets in minutes
- Built on Solana with Nasdaq, offering institutional-grade infrastructure
Where it falls short
- No published pricing, so cost transparency is limited
- Focused on payout advances and revolving credit, not onchain asset management or yield products
- Pricing:
- Pricing is not published on the site.
- Not published
8.Brex
Best for: Startups and growing companies that want corporate cards, expense management, and bill pay in one platform.
- Pricing
- Not published
- Category
- Finance & Accounting
Brex is a corporate card and spend management platform for companies that need to control employee spending, automate expenses, and manage bill pay. Choose Brex instead of Maple Finance if you run a traditional business and need day-to-day financial operations, not crypto lending or yield products.
Where it is strong
- Unlimited global cards accepted in 210+ countries and territories
- AI-powered expense automation and accounting integrations
- Up to 3.97% cash back on business account balances
Where it falls short
- Pricing requires contacting sales. No public rates
- No crypto lending or yield products, unlike Maple Finance
- Pricing:
- Pricing is not published on the site.
- Not published
9.Clearco
Best for: DTC ecommerce brands in the U.S. with at least $100k monthly revenue that need fast, non-dilutive capital for inventory, purchase orders, or marketing.
- Pricing
- Not published
- Category
- Finance & Accounting
Clearco provides non-dilutive revenue-based financing for DTC ecommerce brands, with funding up to $10 million and terms up to 12 months. Choose Clearco over Maple Finance if you run an ecommerce business and need cash for inventory or growth without giving up equity or dealing with crypto lending.
Where it is strong
- No equity dilution or collateral required
- Funding up to $10 million based on revenue
- Application reviewed in as little as 24 hours
Where it falls short
- Only for U.S. incorporated businesses with active U.S. bank accounts
- Requires 6+ months of consistent revenue over $100k/month
- Pricing:
- Pricing is not published on the site.
- Not published
10.Earnin
Best for: Hourly or salaried employees in the US who want to access earned wages before their next payday.
- Pricing
- Not published
- Category
- Finance & Accounting
EarnIn gives workers early access to wages they've already earned, with no mandatory fees or interest. It's for employees who need cash before payday, not for institutions seeking onchain lending or yield.
Where it is strong
- No mandatory fees or interest charges
- Get up to $200 per day, or $1500 per pay period with direct deposit
- Money arrives in 1-3 business days for free, or instantly for a small fee
Where it falls short
- Only for individual employees, not for institutional lending
- No onchain or DeFi yield products
- Pricing:
- Pricing is not published on the site.
- Not published
11.Pipe
Best for: Vertical SaaS, payment facilitators, and marketplaces that want to embed financing and cash-flow tools into their platforms.
- Pricing
- Not published
- Category
- Finance & Accounting
Pipe is an embedded financial OS that lets platforms offer capital and cash-flow tools to their customers. It is a good fit for vertical SaaS, payment facilitators, and marketplaces that want to add financing without building it themselves. Choose Pipe over Maple Finance if you need to embed financial products into your software, not manage onchain lending.
Where it is strong
- Single integration to offer financial tools globally
- Industry-specific risk models for vertical SaaS
- Strong partner support and fast implementation
Where it falls short
- Pricing not disclosed publicly
- No onchain or DeFi capabilities compared with Maple Finance
- Pricing:
- Pricing is not published on the site.
- 3.4% + $0.50
12.Stripe
Best for: Online businesses and platforms that need to accept payments, manage subscriptions, or embed financial infrastructure globally.
- Pricing
- 3.4% + $0.50
- Category
- Finance & Accounting
Stripe is a payments platform for accepting and managing money movement, not a lending or yield product. Choose it when you need to collect payments, handle subscriptions, or embed financial services in your own product, rather than borrowing or earning yield on digital assets.
Where it is strong
- Supports 135+ currencies and payment methods.
- Handles high transaction volumes with 99.999% uptime.
- Offers flexible billing models and embedded payments.
Where it falls short
- Not designed for lending or yield products.
- Pricing varies by region and can be complex for international cards.
- Pricing:
- In Singapore, domestic card payments cost 3.4% + $0.50 per successful transaction, with custom pricing for higher volume.
See more comparisons in Finance & Accounting alternatives.
FAQ
Questions about Maple Finance alternatives
What is the main difference between Maple Finance and Stripe?
Maple Finance is for onchain lending and yield, while Stripe is for accepting payments and managing money movement. Choose Stripe if you need to collect payments or handle subscriptions, not for borrowing or earning yield on digital assets.
Which alternative is best for a startup needing corporate cards?
Brex is the best fit for startups wanting corporate cards, expense management, and bill pay. It offers unlimited global cards and AI-powered expense automation, though pricing requires contacting sales.
Can I embed lending into my platform with any of these alternatives?
Yes, Sivo and Pipe both offer embedded lending. Sivo turns pending payouts into instant cash for gig workers and merchants, while Pipe lets vertical SaaS and marketplaces offer financing to their customers.
Are there alternatives that offer onchain yield like Maple Finance?
Aave and Compound are decentralized lending protocols where you can earn yield or borrow against assets. They are permissionless and self-serve, unlike Maple's curated, expert-managed products. Centrifuge also tokenizes real-world assets for DeFi liquidity.
Which alternative is best for ecommerce brands needing fast capital?
Clearco provides non-dilutive revenue-based financing for DTC ecommerce brands in the U.S. with at least $100k monthly revenue. Funding goes up to $10 million, with applications reviewed in as little as 24 hours.
Last updated November 3, 2026.