Bankjoy alternatives
10 products compared · Updated October 16, 2026
The short answer
For banks and credit unions evaluating alternatives to Bankjoy, the strongest options are Q2 for mid-sized and large institutions needing commercial banking and advanced fraud detection, Alkami for data-driven engagement and business account growth, and Jack Henry for a comprehensive technology stack including core processing and payments. Each suits different institution sizes and needs, so consider your scale and feature priorities.
Your shortlist, at a glance
Read the comparisons ↓Q2Not publishedMid-sized and large banks and credit unions that need commercial banking features and advanced fraud detection.
 AlkamiNot publishedMid-sized banks and credit unions that want to use data to anticipate member needs and grow business accounts.
 Jack HenryNot publishedCommunity and regional financial institutions that want a comprehensive technology stack beyond digital banking, including core processing and payments.
- nnCinoSee websitenCino cloud platform for financial services
 TemenosNot publishedLarge banks and financial institutions that need a complete, cloud-native core banking platform with global reach and end-to-end capabilities.
- TThought MachineNot publishedTeams researching cloud core banking platforms who are willing to wait until Thought Machine's site is live again.
 MambuNot publishedFinancial institutions in 65+ countries that want to compose their own banking stack and launch lending, deposits, and payments products quickly.
 FIS Digital BankingNot publishedLarge banks and financial institutions that need a global, end-to-end platform for core banking, payments, and treasury operations.
- FFinastraSee websiteFinancial technology solutions
 CouchbaseFrom $0.15/hr/nodeTeams building production AI agents, mobile apps, or distributed systems that need a unified JSON database with vector search and low-latency access across cloud and edge.
About Bankjoy and its alternatives
Bankjoy is a digital banking platform for community banks and credit unions. It offers consumer and business banking solutions, including mobile apps, online account opening, loan applications, and integrations with core systems. Bankjoy is known for its all-in-one approach and focus on community financial institutions.
When comparing alternatives, weigh pricing structure, regions served, integrations with your core system, support quality, and contract terms. Some vendors publish pricing, while others require sales conversations. Consider whether you need a turnkey digital banking layer or a broader technology stack.
Explore the alternatives
- Not published
1.Q2
Best for: Mid-sized and large banks and credit unions that need commercial banking features and advanced fraud detection.
- Pricing
- Not published
- Category
- Finance & Accounting
Q2 is a digital banking platform for banks and credit unions, covering consumer, small business, and commercial banking with built-in fraud intelligence. Choose Q2 over Bankjoy if you need a platform that scales to larger institutions and emphasizes AI-driven fraud prevention and commercial banking capabilities.
Where it is strong
- Serves consumer, SMB, and commercial banking segments
- AI-powered fraud detection across channels
- Used by 1,000+ financial institutions
Where it falls short
- Pricing not public, likely enterprise-focused
- May be more complex than Bankjoy for smaller community institutions
- Pricing:
- Pricing is not published on the site.
- Not published
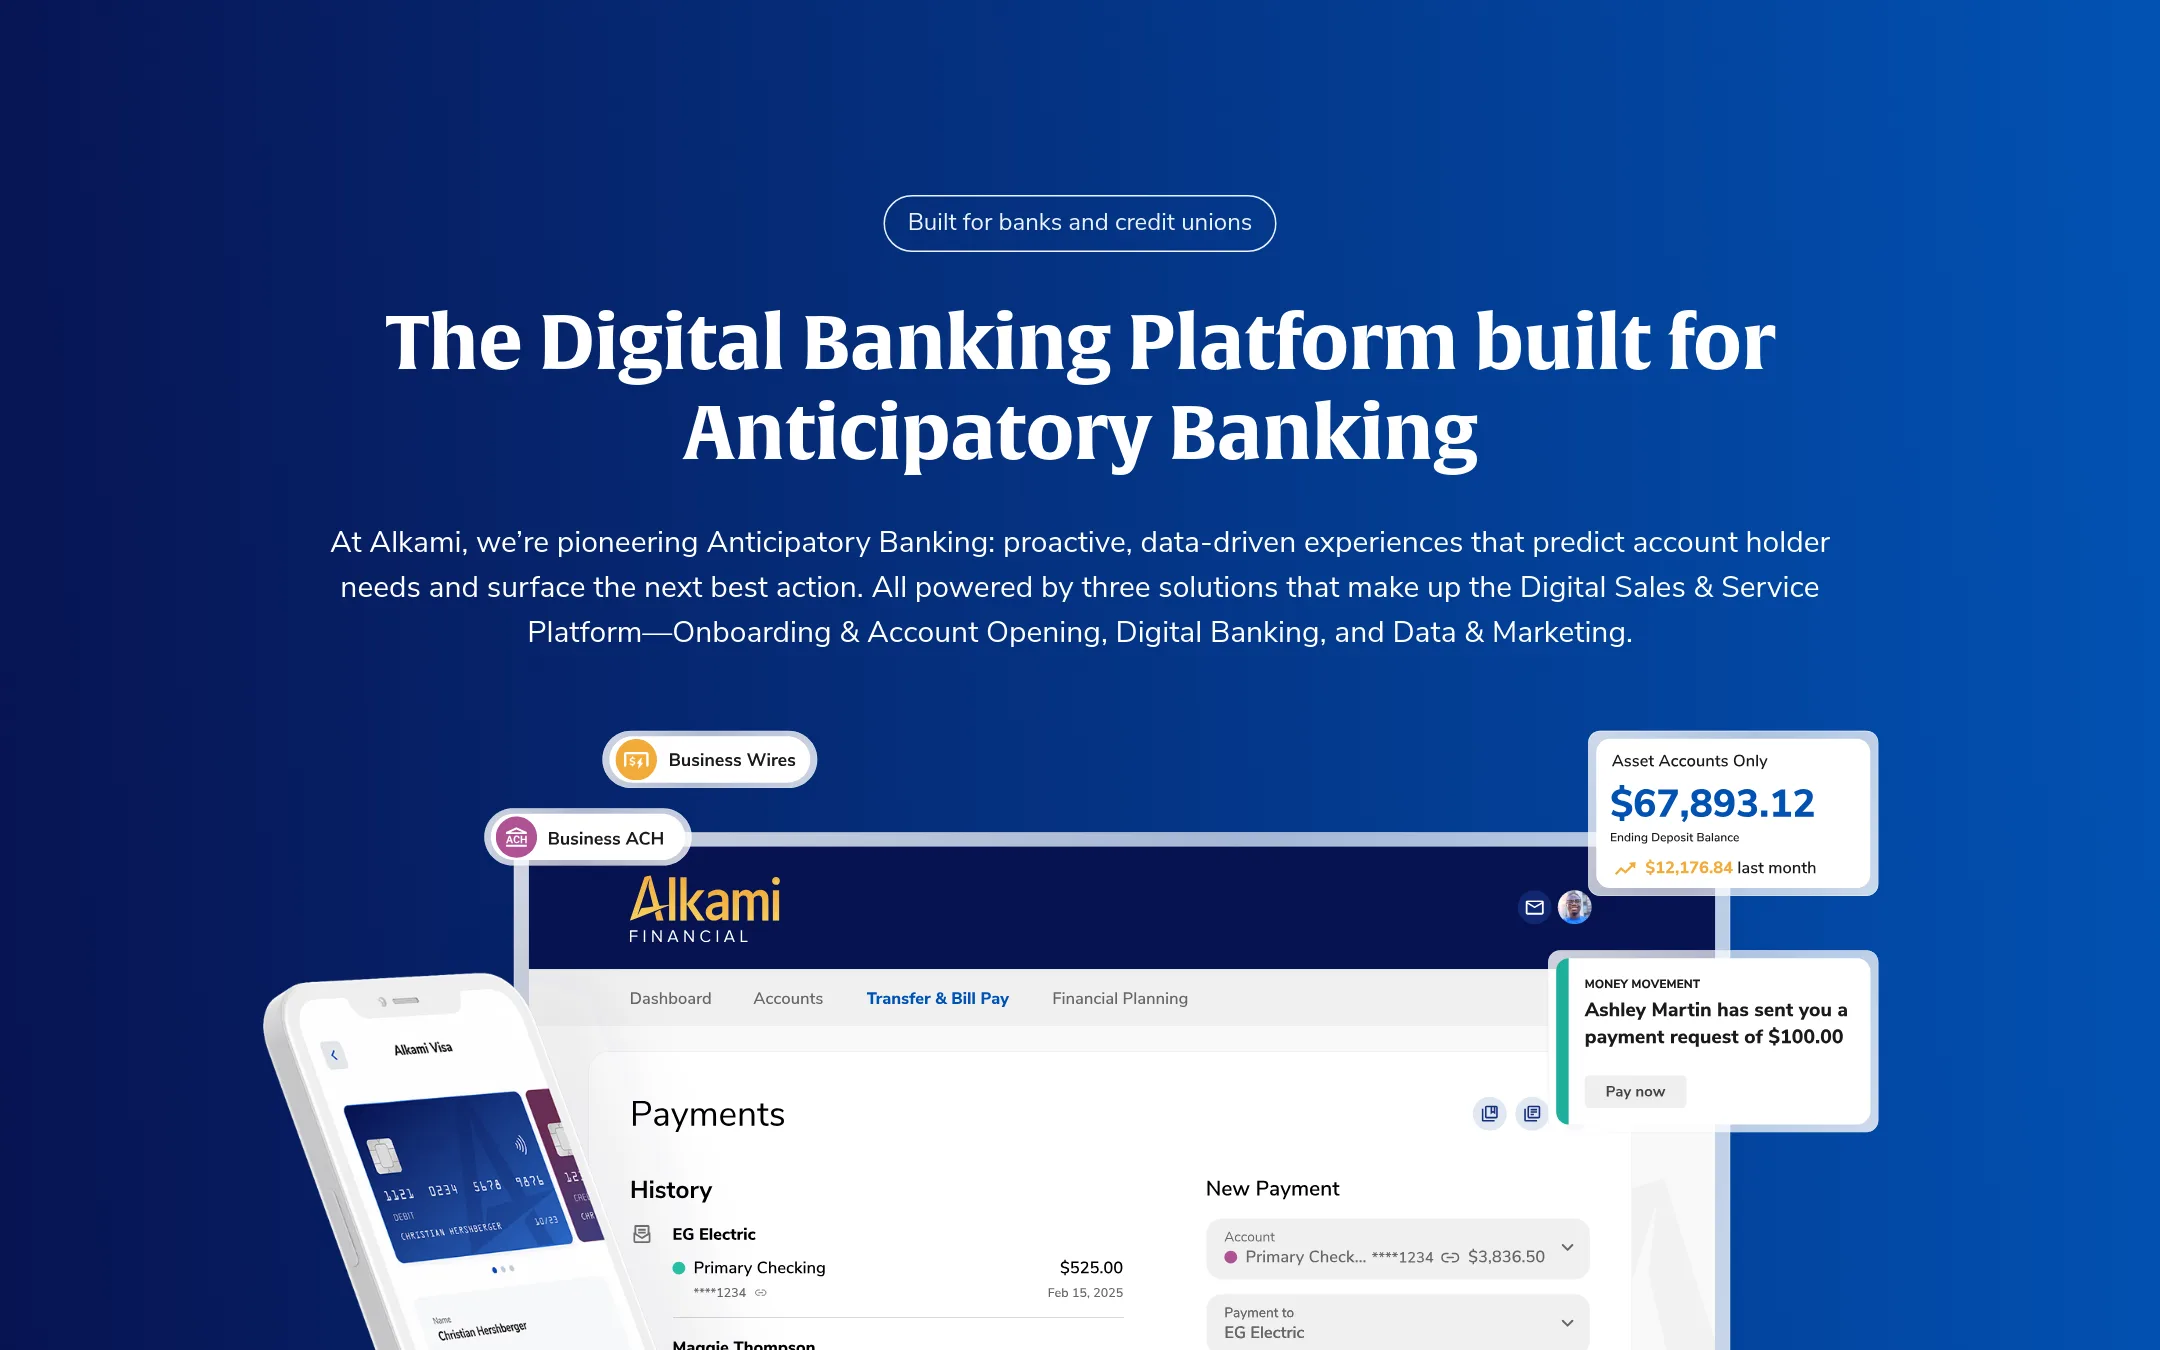
2.Alkami
Best for: Mid-sized banks and credit unions that want to use data to anticipate member needs and grow business accounts.
- Pricing
- Not published
- Category
- Finance & Accounting
Alkami is a digital banking platform for banks and credit unions that focuses on anticipating member needs through data-driven engagement. Choose it over Bankjoy if you want a platform that emphasizes predictive analytics and growth-oriented features for business accounts.
Where it is strong
- Built for anticipatory banking with data-driven insights
- Designed to grow business accounts and revenue
- Trusted by regional and community financial institutions
Where it falls short
- Pricing not disclosed, likely enterprise-focused
- May be more complex than Bankjoy for smaller institutions
- Pricing:
- Pricing is not published on the site.
- Not published
3.Jack Henry
Best for: Community and regional financial institutions that want a comprehensive technology stack beyond digital banking, including core processing and payments.
- Pricing
- Not published
- Category
- Finance & Accounting
Jack Henry is a broad technology provider for community and regional banks, credit unions, and fintechs, offering core platforms, digital banking, payments, and lending. Choose it if you need a full technology ecosystem with deep integration options and are willing to manage a larger, more complex vendor relationship.
Where it is strong
- Offers a wide range of services including core platforms, payments, and lending.
- Cloud-native platform built with Google Cloud for scalability and security.
- Strong focus on community and regional institutions with advocacy and support.
Where it falls short
- Pricing is not transparent, likely enterprise-level contracts.
- May be more complex to implement than a focused digital banking solution like Bankjoy.
- Pricing:
- Pricing is not published on the site.
- nSee website
4.nCino
Finance & Accounting
nCino focuses on cloud-based banking solutions with emphasis on commercial lending and CRM workflows for banks. It shines in loan origination efficiency but offers less emphasis on consumer PFM or vertical market branding compared to Bankjoy, making it a fit for institutions prioritizing business lending over broad retail digital experiences.
- Not published
5.Temenos
Best for: Large banks and financial institutions that need a complete, cloud-native core banking platform with global reach and end-to-end capabilities.
- Pricing
- Not published
- Category
- Finance & Accounting
Temenos is a global, cloud-native banking platform covering core banking, digital banking, payments, wealth, and financial crime mitigation. Choose it over Bankjoy if you are a large bank or financial institution that needs a full core banking replacement and operates across multiple countries, not just a digital front-end for an existing core.
Where it is strong
- End-to-end platform: core, digital, payments, wealth, and financial crime mitigation.
- Trusted by 950+ banks globally, with a strong track record in large-scale transformations.
- Cloud-native and AI-driven, with SaaS deployment options for faster modernization.
Where it falls short
- Enterprise-scale platform, likely overkill for community banks or credit unions.
- Pricing is not transparent and requires a sales engagement.
- Pricing:
- Pricing is not published on the site.
- TNot published
6.Thought Machine
Best for: Teams researching cloud core banking platforms who are willing to wait until Thought Machine's site is live again.
- Pricing
- Not published
- Category
- Finance & Accounting
Thought Machine's domain is parked, so the product is not currently accessible. Choose it only if you are evaluating the company for future core banking needs, not as a working alternative to Bankjoy today.
Where it is strong
- Known for cloud-native core banking technology.
- Targets modern banks with a Vault platform.
- No legacy infrastructure to migrate from.
Where it falls short
- Website is parked, so no product details or demos are available.
- No pricing or feature information can be verified.
- Pricing:
- Pricing is not published on the site.
- Not published
7.Mambu
Best for: Financial institutions in 65+ countries that want to compose their own banking stack and launch lending, deposits, and payments products quickly.
- Pricing
- Not published
- Category
- Finance & Accounting
Mambu is a composable cloud banking platform that connects core banking, payments, and AI into one system. Choose it over Bankjoy if you are a larger or more tech-driven financial institution that needs to build custom banking products and move at AI speed, rather than a community bank or credit union looking for an out-of-the-box digital banking suite.
Where it is strong
- Composable platform lets you pick and integrate only the modules you need.
- Serves 65+ countries, so it is built for global operations.
- Strong API and developer ecosystem for custom integrations.
Where it falls short
- No published pricing, so budgeting requires a sales conversation.
- More complex to set up than a turnkey digital banking suite like Bankjoy.
- Pricing:
- Pricing is not published on the site.
- Not published
8.FIS Digital Banking
Best for: Large banks and financial institutions that need a global, end-to-end platform for core banking, payments, and treasury operations.
- Pricing
- Not published
- Category
- Finance & Accounting
FIS Digital Banking is a large-scale fintech platform covering the full money lifecycle, from core banking to payments and treasury. Choose it over Bankjoy if you are a large institution needing a global, end-to-end infrastructure rather than a community-focused digital banking layer.
Where it is strong
- Global scale with solutions across the entire money lifecycle
- Strong security, compliance, and resilience reputation
- Analytics to uncover growth opportunities
Where it falls short
- Pricing not disclosed, likely enterprise-level
- May be overkill for community banks or credit unions
- Pricing:
- Pricing is not published on the site.
- FSee website
9.Finastra
Finance & Accounting
Finastra delivers lending and digital solutions for banks with emphasis on treasury and transaction banking. It competes on enterprise lending workflows but lacks Bankjoy's specific consumer tools like gamified PFM or fast vertical banking setups tailored for credit unions.
- From $0.15/hr/node
10.Couchbase
Best for: Teams building production AI agents, mobile apps, or distributed systems that need a unified JSON database with vector search and low-latency access across cloud and edge.
Couchbase is an operational data platform for building and scaling AI agents, mobile apps, and mission-critical applications with sub-millisecond latency. Choose it over Bankjoy if you need a high-performance NoSQL database with vector search and edge deployment, not a digital banking front-end.
Where it is strong
- Sub-millisecond latency and 99.999% availability for critical workloads
- Unified JSON, vector search, and mobile sync in one platform
- Deploy across cloud, on-prem, edge, and air-gapped environments
Where it falls short
- No digital banking features like account opening or loan applications
- Pricing is per node per hour, which can get complex for large clusters
- Pricing:
- Pricing starts at $0.15/hr per node for Basic, $0.35/hr per node for Developer Pro, and $0.49/hr per node for Enterprise. A free tier is available.
See more comparisons in Finance & Accounting alternatives.
FAQ
Questions about Bankjoy alternatives
What are the main differences between Bankjoy and Q2?
Q2 serves mid-sized and large banks and credit unions, with a focus on commercial banking and AI-driven fraud detection. Bankjoy targets community financial institutions with a simpler, all-in-one digital banking suite. Q2 may be more complex and enterprise-focused, while Bankjoy is designed for smaller institutions.
Which alternative is best for a community bank or credit union?
Jack Henry is a strong choice for community and regional institutions that want a comprehensive technology stack, including core processing and payments. Alkami also serves mid-sized banks and credit unions, with a focus on data-driven engagement. Bankjoy itself remains a viable option for community institutions.
Are there alternatives with transparent pricing?
Most alternatives, including Q2, Alkami, Jack Henry, Temenos, Mambu, and FIS, do not publish pricing and require sales engagement. Couchbase, which is not a digital banking platform, publishes per-node hourly pricing. For budgeting, you will likely need to contact vendors directly.
Can these alternatives replace a core banking system?
Temenos and Thought Machine offer core banking platforms, while Jack Henry provides core processing as part of its ecosystem. Q2, Alkami, and Bankjoy are digital banking front-ends that integrate with existing cores. Choose based on whether you need a full core replacement or just a digital layer.
Which alternative is best for a large bank with global operations?
Temenos and FIS Digital Banking are built for large, global institutions, offering end-to-end capabilities across core banking, payments, and treasury. Mambu also serves 65+ countries with a composable platform. These are likely overkill for community banks but suitable for large-scale needs.
Last updated October 16, 2026.