Baraka alternatives
7 products compared · Updated November 3, 2026
The short answer
The strongest Baraka alternatives are Betterment for Business, Robinhood, and Wealthfront. Betterment for Business suits US employers and individuals wanting automated, fee-based investing and retirement accounts. Robinhood is ideal for US-based investors seeking commission-free trading with a simple mobile app. Wealthfront fits US investors who prefer hands-off portfolio management or fee-free self-directed trading.
Your shortlist, at a glance
Read the comparisons ↓- WWealthfront0.25% annual + $0 tradUS investors who want hands-off portfolio management or fee-free ETF and stock trading, and who don't need GCC market access or Sharia-compliant options.
 Betterment for BusinessNot publishedUS employers and individuals who want automated, fee-based investing and retirement accounts instead of self-directed trading.
- MM1 FinanceNot publishedUS-based long-term investors who want automated pie investing, cash management, and margin loans in a single account.
- RRobinhoodNot publishedUS-based or US-focused investors who want commission-free stock and options trading with a simple mobile app.
Fidelity 401(k)Not publishedUS employers and employees who want a 401(k) plan with Fidelity's retirement services.
Charles SchwabSee websiteFinancial services with an authorization error on access
Vanguard 401(k)Not publishedEmployers and employees who need a low-cost, long-term retirement plan with Vanguard's index fund lineup.
About Baraka and its alternatives
Baraka is a UAE and GCC-focused investing platform that lets you buy US stocks, ETFs, options, and physical gold from your phone. It is known for a Sharia filter, fractional shares from $1, and DFSA regulation, with plans starting at $9.99 per month.
When comparing alternatives, weigh pricing structure (monthly fees vs. commission-free), regional availability (US-only vs. GCC access), integrations with retirement plans, support quality, and contract terms like minimum balances or advisory fees.
Explore the alternatives
- W0.25% annual + $0 trad
1.Wealthfront
Best for: US investors who want hands-off portfolio management or fee-free ETF and stock trading, and who don't need GCC market access or Sharia-compliant options.
- Pricing
- 0.25% annual + $0 trad
- Category
- Other
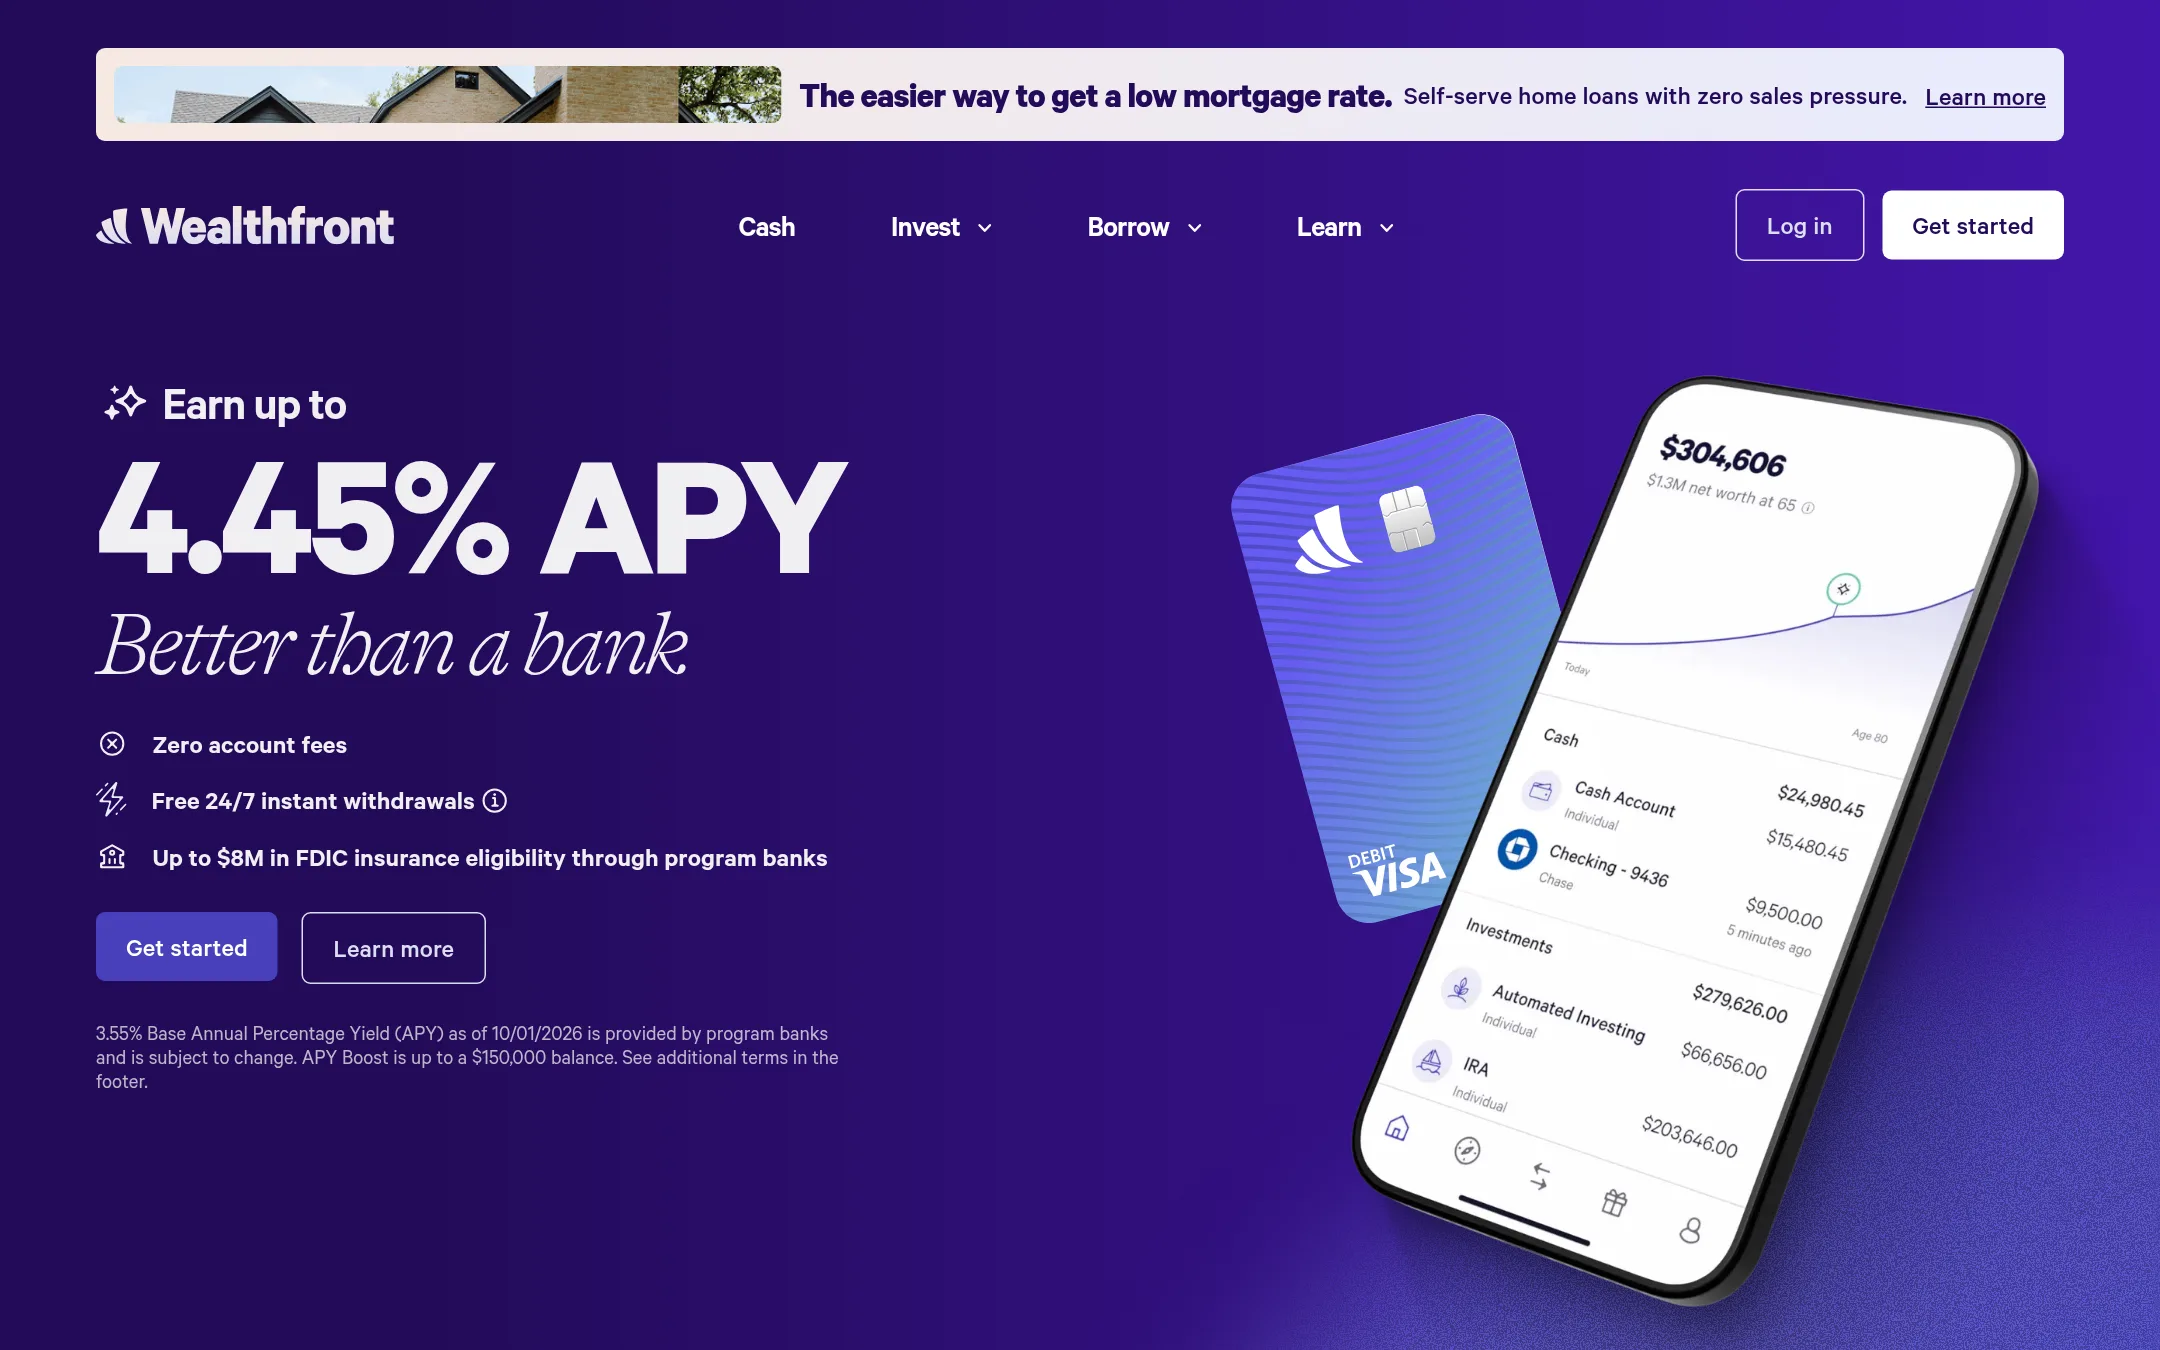
Wealthfront is a US-based automated investing and cash management platform. Choose it over Baraka if you want a robo-advisor that builds and manages a diversified portfolio for you, or a self-directed brokerage with no trading fees, and you don't need access to GCC markets or Sharia filtering.
Where it is strong
- Automated portfolio management with tax-loss harvesting
- No fees for self-directed ETF and stock trading
- Cash account earns high APY
Where it falls short
- No access to GCC markets or Sharia filter
- Advisory fee applies only to managed portfolios, not self-directed
- Pricing:
- The Wealthfront Portfolio advisory fee is 0.25% annually. The Brokerage Account has no fees and requires $1 to start.
- Switching from Baraka:
- Moving from Baraka means transferring your investments to a US-based platform, which may involve selling GCC assets and opening a new account with US banking details.
- Not published
2.Betterment for Business
Best for: US employers and individuals who want automated, fee-based investing and retirement accounts instead of self-directed trading.
- Pricing
- Not published
- Category
- Finance & Accounting
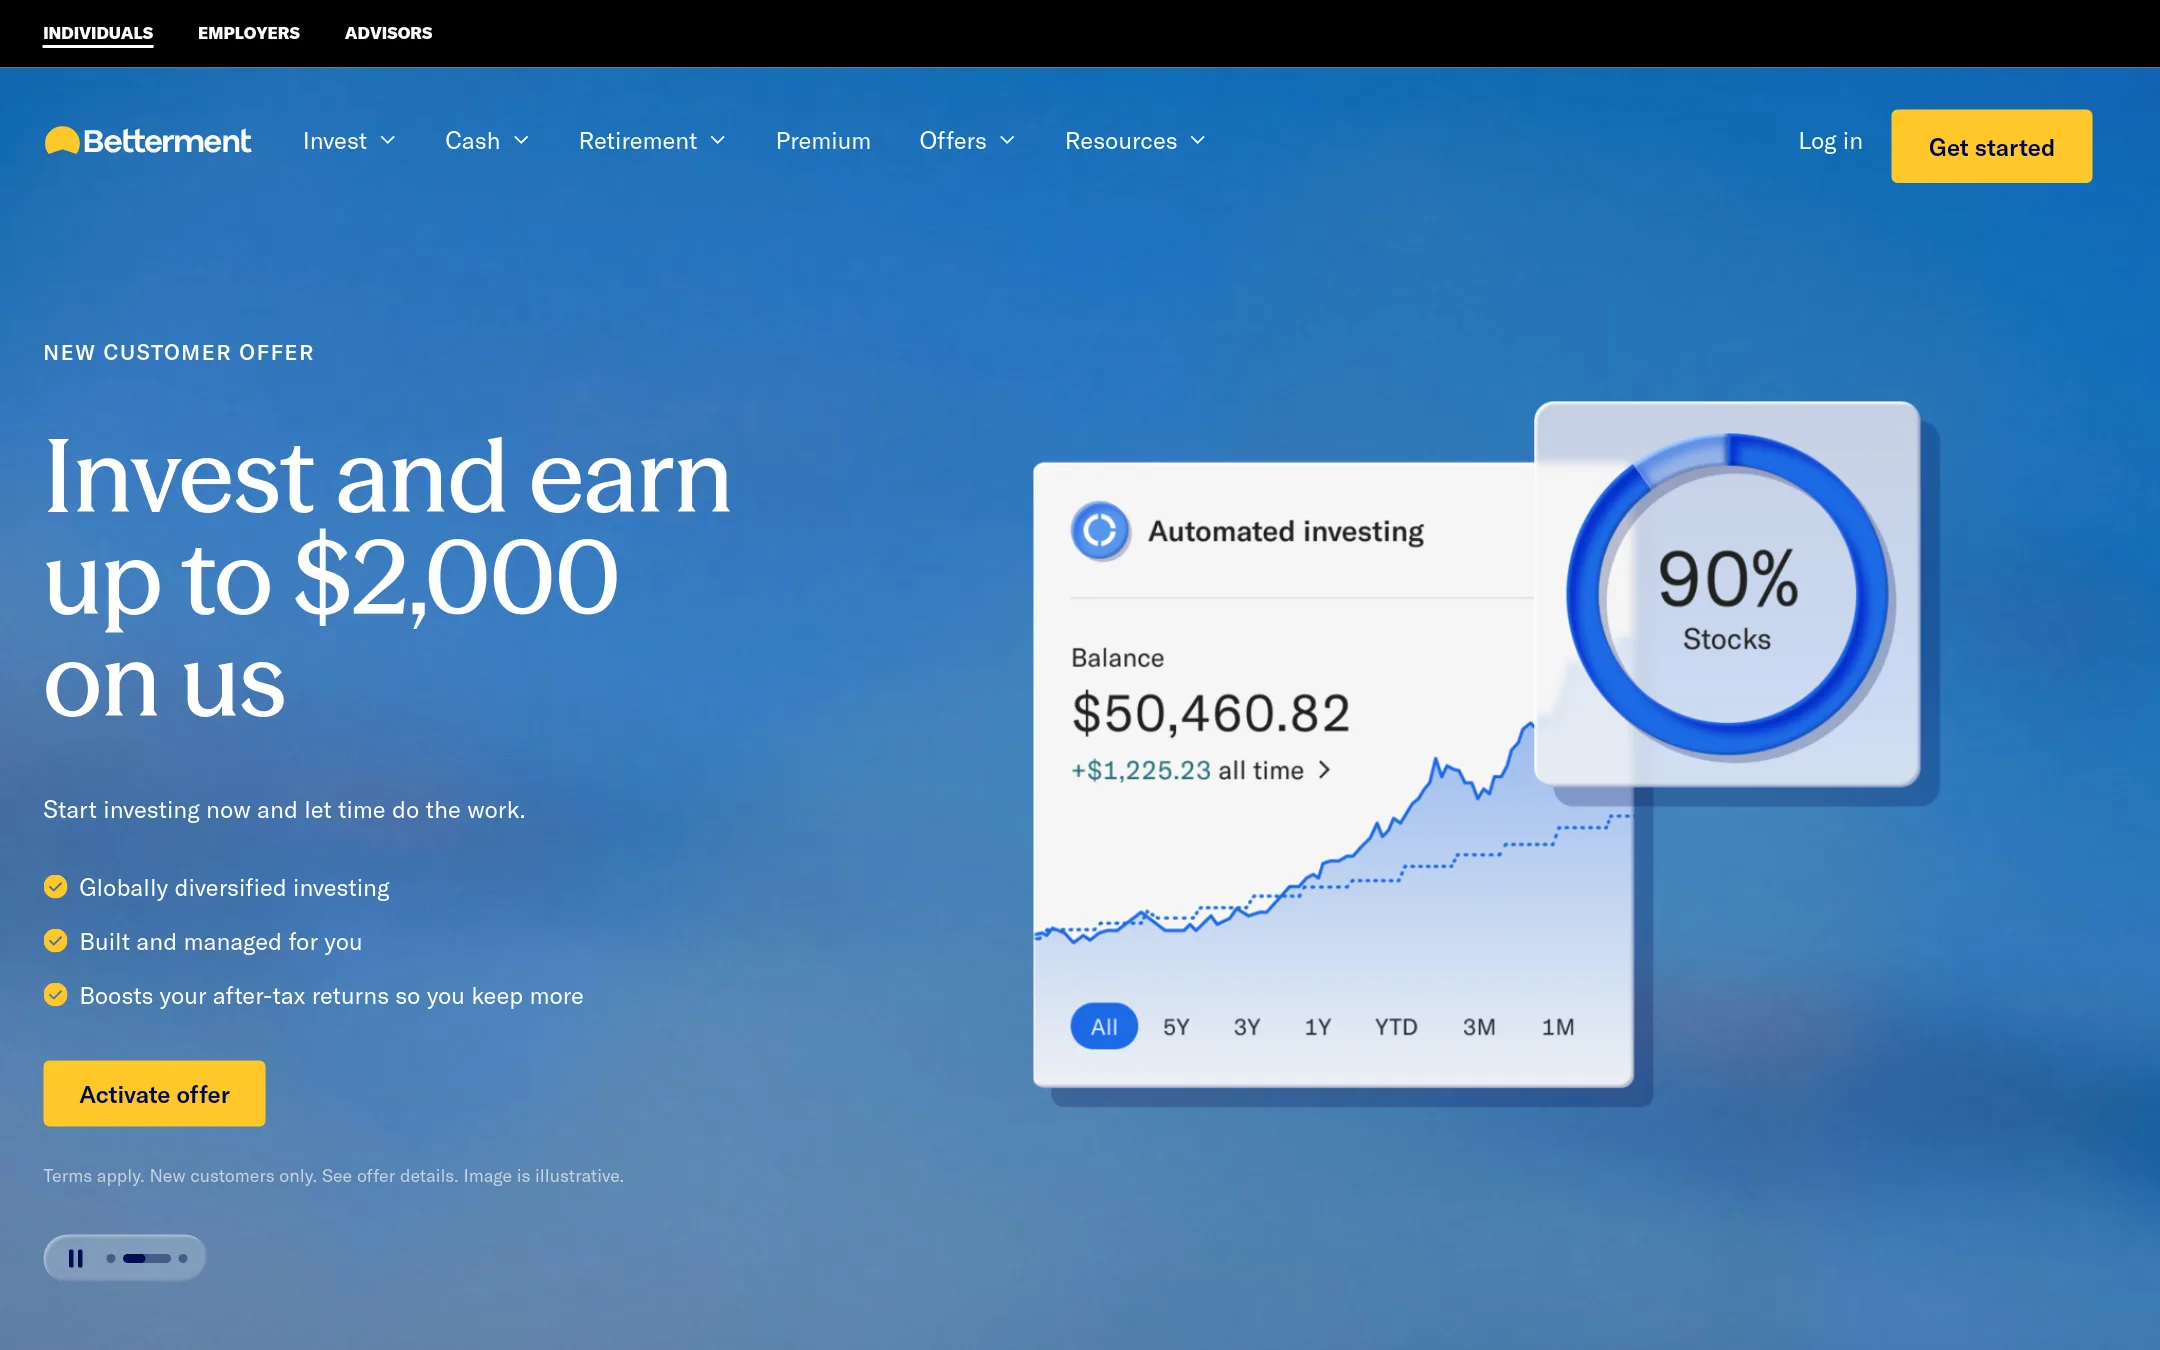
Betterment for Business is an automated investing and retirement platform for US-based businesses and individuals. You would choose it over Baraka if you want a fiduciary robo-advisor with tax-loss harvesting, cash management, and 401(k) plans, rather than direct access to US stocks and options from the GCC.
Where it is strong
- Automated portfolio management with rebalancing and tax-loss harvesting
- No commission fees for self-directed stock and ETF trades
- Cash accounts with FDIC insurance up to $8M (joint) and $4M (individual)
Where it falls short
- No direct access to GCC markets or Sharia filter like Baraka
- Premium plan requires a $100,000 minimum balance for advisor access
- Pricing:
- Pricing is not published on the site.
- MNot published
3.M1 Finance
Best for: US-based long-term investors who want automated pie investing, cash management, and margin loans in a single account.
- Pricing
- Not published
- Category
- Other
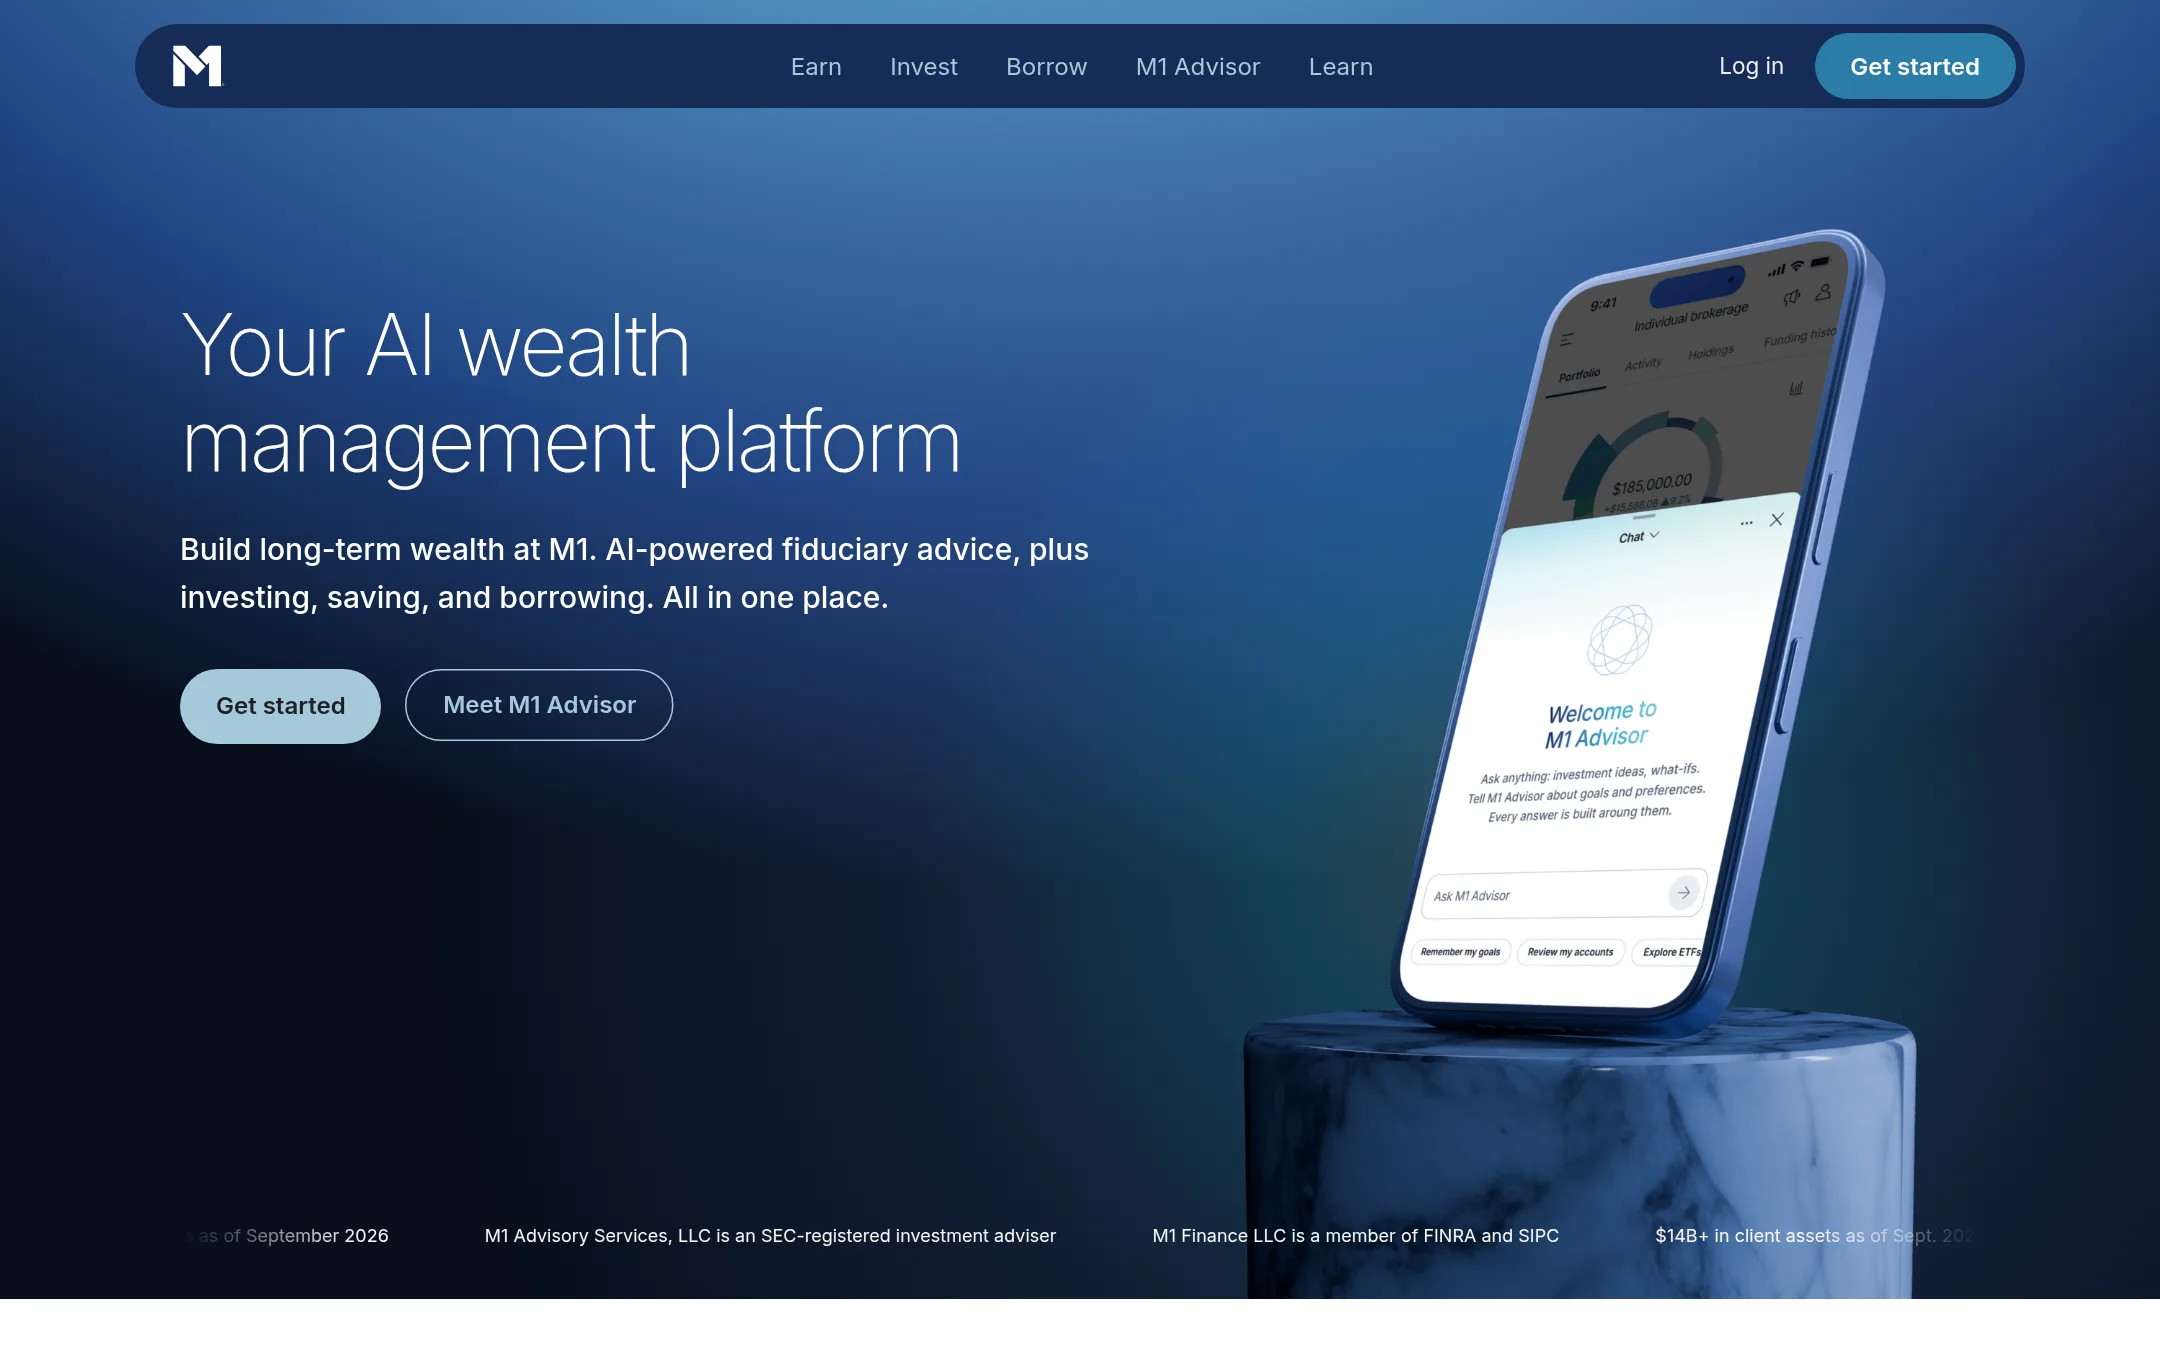
M1 Finance is a US-based platform that combines automated investing, high-yield cash accounts, and margin borrowing in one place. You would choose it over Baraka if you are a US investor who wants long-term wealth building with built-in fiduciary advice and the ability to borrow against your portfolio.
Where it is strong
- Automated investing with customizable pies
- High-yield cash account with 3.35% APY on uninvested cash
- Built-in margin loans and portfolio line of credit
Where it falls short
- No published pricing for trading fees or account costs
- Focused on US investors, not available for GCC users like Baraka
- Pricing:
- Pricing is not published on the site.
- RNot published
4.Robinhood
Best for: US-based or US-focused investors who want commission-free stock and options trading with a simple mobile app.
- Pricing
- Not published
- Category
- Other
Robinhood is a commission-free trading app for US stocks, ETFs, and options, with fractional shares and a 24-hour market. Choose it over Baraka if you want a US-centric platform with no per-trade fees and a broader range of features like margin and stock lending.
Where it is strong
- No commission on US stock and ETF trades
- Fractional shares from $1
- 24-hour trading on major US stocks
Where it falls short
- No Sharia filter or halal investing options
- Limited to US markets. No GCC local stocks
- Pricing:
- Pricing is not published on the site.
- Not published
5.Fidelity 401(k)
Best for: US employers and employees who want a 401(k) plan with Fidelity's retirement services.
- Pricing
- Not published
- Category
- Finance & Accounting
Fidelity 401(k) is a retirement plan provider for US-based employers and their employees. Choose it instead of Baraka if you need a workplace retirement account with tax advantages, not a self-directed brokerage for trading US stocks and ETFs from the GCC.
Where it is strong
- Widely recognized US financial services firm.
- Focus on retirement planning, not just trading.
- Accessible only to US individuals per the site's usage agreement.
Where it falls short
- Not available to investors outside the US.
- No pricing details or fee schedule on the site.
- Pricing:
- Pricing is not published on the site.
- See website
6.Charles Schwab
Finance & Accounting
A major brokerage with automated investing and low fees, competing for the same investor segment.
- Not published
7.Vanguard 401(k)
Best for: Employers and employees who need a low-cost, long-term retirement plan with Vanguard's index fund lineup.
- Pricing
- Not published
- Category
- Finance & Accounting
Vanguard 401(k) is a retirement plan provider for employers, not a retail investing app. Choose it if you are an employer setting up a company retirement plan, or an employee who wants low-cost index funds inside a 401(k). Baraka is for individual investors in the GCC buying US stocks, ETFs, and options.
Where it is strong
- Low-cost index funds and ETFs from a trusted provider.
- Designed for long-term retirement savings with employer plans.
- Strong reputation with 30 million investors.
Where it falls short
- No pricing details published, so cost comparison is hard.
- Not for individual stock trading or options like Baraka.
- Pricing:
- Pricing is not published on the site.
See more comparisons in Finance & Accounting alternatives.
FAQ
Questions about Baraka alternatives
What are the main differences between Baraka and Betterment for Business?
Baraka is a self-directed trading app for GCC investors, while Betterment for Business is a US-focused automated investing platform. Betterment offers robo-advisory, tax-loss harvesting, and 401(k) plans, but no GCC market access or Sharia filter.
Is Robinhood a good alternative for GCC investors?
Robinhood is commission-free and easy to use, but it is limited to US markets and has no Sharia filter. GCC investors who want local stocks or halal investing would need to look elsewhere.
Does Wealthfront charge fees?
Wealthfront charges a 0.25% annual advisory fee for managed portfolios, but self-directed brokerage accounts have no fees and require $1 to start. It is US-only and does not offer GCC market access.
Can I use M1 Finance outside the US?
M1 Finance is focused on US investors and is not available for GCC users. It offers automated pie investing, high-yield cash accounts, and margin loans, but no published pricing for trading fees.
Which alternative is best for retirement plans?
Vanguard 401(k) and Fidelity 401(k) are designed for employer-sponsored retirement plans, not individual trading. They are US-only and have no published pricing, but they offer low-cost index funds and strong reputations.
Last updated November 3, 2026.