Fintoc alternatives
10 products compared · Updated November 3, 2026
The short answer
For Latin American fintechs needing financial data alongside payments, Belvo is the strongest alternative. For U.S.-focused apps requiring broad bank connectivity, Plaid is the best fit. For Chilean e-commerce businesses wanting instant bank transfers and recurring billing, Khipu is the most direct alternative.
Your shortlist, at a glance
Read the comparisons ↓ PlaidNot publishedU.S.-focused fintechs and apps that need bank data connectivity, identity verification, and payment initiation across thousands of institutions.
 TrueLayerNot publishedEuropean ecommerce, iGaming, and financial services companies that want instant bank payments and payouts.
 BelvoCustom quoteFintechs and lenders in Latin America that need to verify income and financial history while also collecting payments.
- PPomeloNot publishedTeams that already know Pomelo's capabilities and need a payment infrastructure provider, but only after confirming current service details directly.
 YapilyCustom quoteEuropean fintechs, PSPs, and enterprises that need open banking payments and account data across multiple countries.
 Salt EdgeNot publishedCompanies operating internationally that need bank connections in many countries for payments, data, and regulatory compliance.
- FFinverse0.5% per transactionCompanies in Hong Kong, Singapore, or broader Asia-Pacific that want low-cost recurring bank payments and bank data access.
- PPrometeoSee websiteOther
- KKhipuNot publishedChilean e-commerce businesses that want instant bank transfer payments and automated recurring billing without card fees.
 Mercado PagoNot publishedSmall businesses and sellers in Latin America that want a single account for payments, credit, and investment features.
About Fintoc and its alternatives
Fintoc is a payment platform for Mexico and Chile. It lets businesses receive online payments, manage subscriptions, and automate collections. It is known for its account-to-account payments and AI-driven payment optimization, with over 1,200 companies using it.
When comparing alternatives, weigh pricing structure, geographic coverage, and integrations. Check if the provider publishes transparent rates or requires a sales call. Consider whether you need recurring billing, financial data, or just payment acceptance. Also review contract terms and support options.
Explore the alternatives
- Not published
1.Plaid
Best for: U.S.-focused fintechs and apps that need bank data connectivity, identity verification, and payment initiation across thousands of institutions.
- Pricing
- Not published
- Category
- Finance & Accounting
Plaid is a financial data network that connects apps to users' bank accounts, enabling payments, identity verification, and fraud protection. Choose it over Fintoc if you need broad U.S. coverage and a wide range of data products beyond just account-to-account payments.
Where it is strong
- Largest financial network in the U.S., with 12,000 institutions across 20 countries.
- Multiple products: Auth, Balance, Identity, Transactions, and more.
- Free sandbox and limited production testing up to 200 API calls per product.
Where it falls short
- Pricing is opaque and requires contacting sales for most products.
- No built-in subscription management or recurring billing features like Fintoc.
- Pricing:
- Pricing is not published on the site. Plans are Pay as You Go, Growth, and Custom with contact for quotes.
- Switching from Fintoc:
- Moving from Fintoc to Plaid means re-integrating your payment flows and data connections, as Plaid's API and product set differ significantly.
- Not published
2.TrueLayer
Best for: European ecommerce, iGaming, and financial services companies that want instant bank payments and payouts.
- Pricing
- Not published
- Category
- Finance & Accounting
TrueLayer is an open banking platform that lets you accept Pay by Bank payments and make instant payouts across Europe. Choose it over Fintoc if you operate in Europe and want to replace card payments with bank-based transactions that cut costs and reduce fraud.
Where it is strong
- Instant payouts and payments via open banking
- Higher conversion rates, with 90% of returning customers converting
- Reduces card fraud and costs by removing cards
Where it falls short
- Limited to Europe, so not useful for Latin America
- No subscription or recurring billing features mentioned
- Pricing:
- Pricing is not published on the site.
- Custom quote
3.Belvo
Best for: Fintechs and lenders in Latin America that need to verify income and financial history while also collecting payments.
- Pricing
- Custom quote
- Category
- Finance & Accounting
Belvo is an open finance API platform for Latin America that provides both financial data access and account-to-account payments. Choose it over Fintoc when you need deeper financial data insights, such as banking, employment, and fiscal verification, alongside payment capabilities.
Where it is strong
- Offers banking, employment, and fiscal data connections in one API.
- Supports direct debit, biometric payments, and Pix smart transfers.
- Trusted by major Latam fintechs with over 80 million accounts connected.
Where it falls short
- Pricing requires contacting sales. No transparent rates.
- Focused on data and payments, but may lack Fintoc's AI-driven payment optimization features.
- Pricing:
- Pricing is not published on the site. Plans are available on request, with a free sandbox for testing.
- Switching from Fintoc:
- Moving from Fintoc to Belvo involves integrating a new API for data and payments, which may require reworking existing payment flows and data connections.
- PNot published
4.Pomelo
Best for: Teams that already know Pomelo's capabilities and need a payment infrastructure provider, but only after confirming current service details directly.
- Pricing
- Not published
- Category
- Other
Pomelo's website is currently unreachable, so we can't verify what it does or how it compares to Fintoc. If you're evaluating account-to-account payment alternatives, you'd need to contact Pomelo directly for details. Choose it only if you have prior knowledge of its offerings and they fit your needs better than Fintoc's Chile and Mexico focus.
Where it is strong
- No pricing information to evaluate, so no cost surprises if you negotiate directly.
- Potential for tailored solutions if you reach out and discuss your use case.
- You avoid relying on a site that is currently down, so you can ask questions upfront.
Where it falls short
- Website is unreachable, so you cannot verify features, integrations, or regions.
- No public documentation or pricing, making it hard to compare with Fintoc's transparent offering.
- Pricing:
- Pricing is not published on the site.
- Custom quote
5.Yapily
Best for: European fintechs, PSPs, and enterprises that need open banking payments and account data across multiple countries.
- Pricing
- Custom quote
- Category
- Finance & Accounting
Yapily is an open banking API platform that connects to thousands of banks across 19 countries, mainly in Europe. It offers Pay by Bank, recurring payments, and financial data access. Choose it over Fintoc if you need broad European bank coverage and want to build on open banking infrastructure rather than Fintoc's Chile and Mexico focus.
Where it is strong
- Broad bank coverage across 19 countries, including UK and Germany.
- Combines payments and financial data in one API.
- Agentic-ready docs designed for AI coding agents.
Where it falls short
- Pricing is not transparent. Requires a sales conversation.
- No coverage in Latin America, unlike Fintoc's Chile and Mexico focus.
- Pricing:
- Pricing is not published on the site. It is tailored per business and requires speaking with the team.
- Switching from Fintoc:
- Moving from Fintoc to Yapily means re-integrating your payment and data flows to a new API, with different bank coverage and no direct migration path.
- Not published
6.Salt Edge
Best for: Companies operating internationally that need bank connections in many countries for payments, data, and regulatory compliance.
- Pricing
- Not published
- Category
- Finance & Accounting
Salt Edge is a global open banking platform that connects to over 5000 banks for data aggregation, payments, and compliance. You would choose it over Fintoc if you need bank coverage across many countries, not just Mexico and Chile, and if your use case includes both account-to-account payments and broader open banking data services.
Where it is strong
- Connects to 5000+ banks worldwide, far beyond Fintoc's two-country focus.
- Covers data aggregation, payments, and compliance in one platform.
- Global reach suits multi-country operations.
Where it falls short
- No published pricing, so you must contact sales for a quote.
- May be more complex than Fintoc if you only need payments in Mexico and Chile.
- Pricing:
- Pricing is not published on the site.
- Switching from Fintoc:
- Moving from Fintoc means re-integrating your payment flows and data connections with Salt Edge's API, which is a different technical setup.
- F0.5% per transaction
7.Finverse
Best for: Companies in Hong Kong, Singapore, or broader Asia-Pacific that want low-cost recurring bank payments and bank data access.
- Pricing
- 0.5% per transaction
- Category
- Other
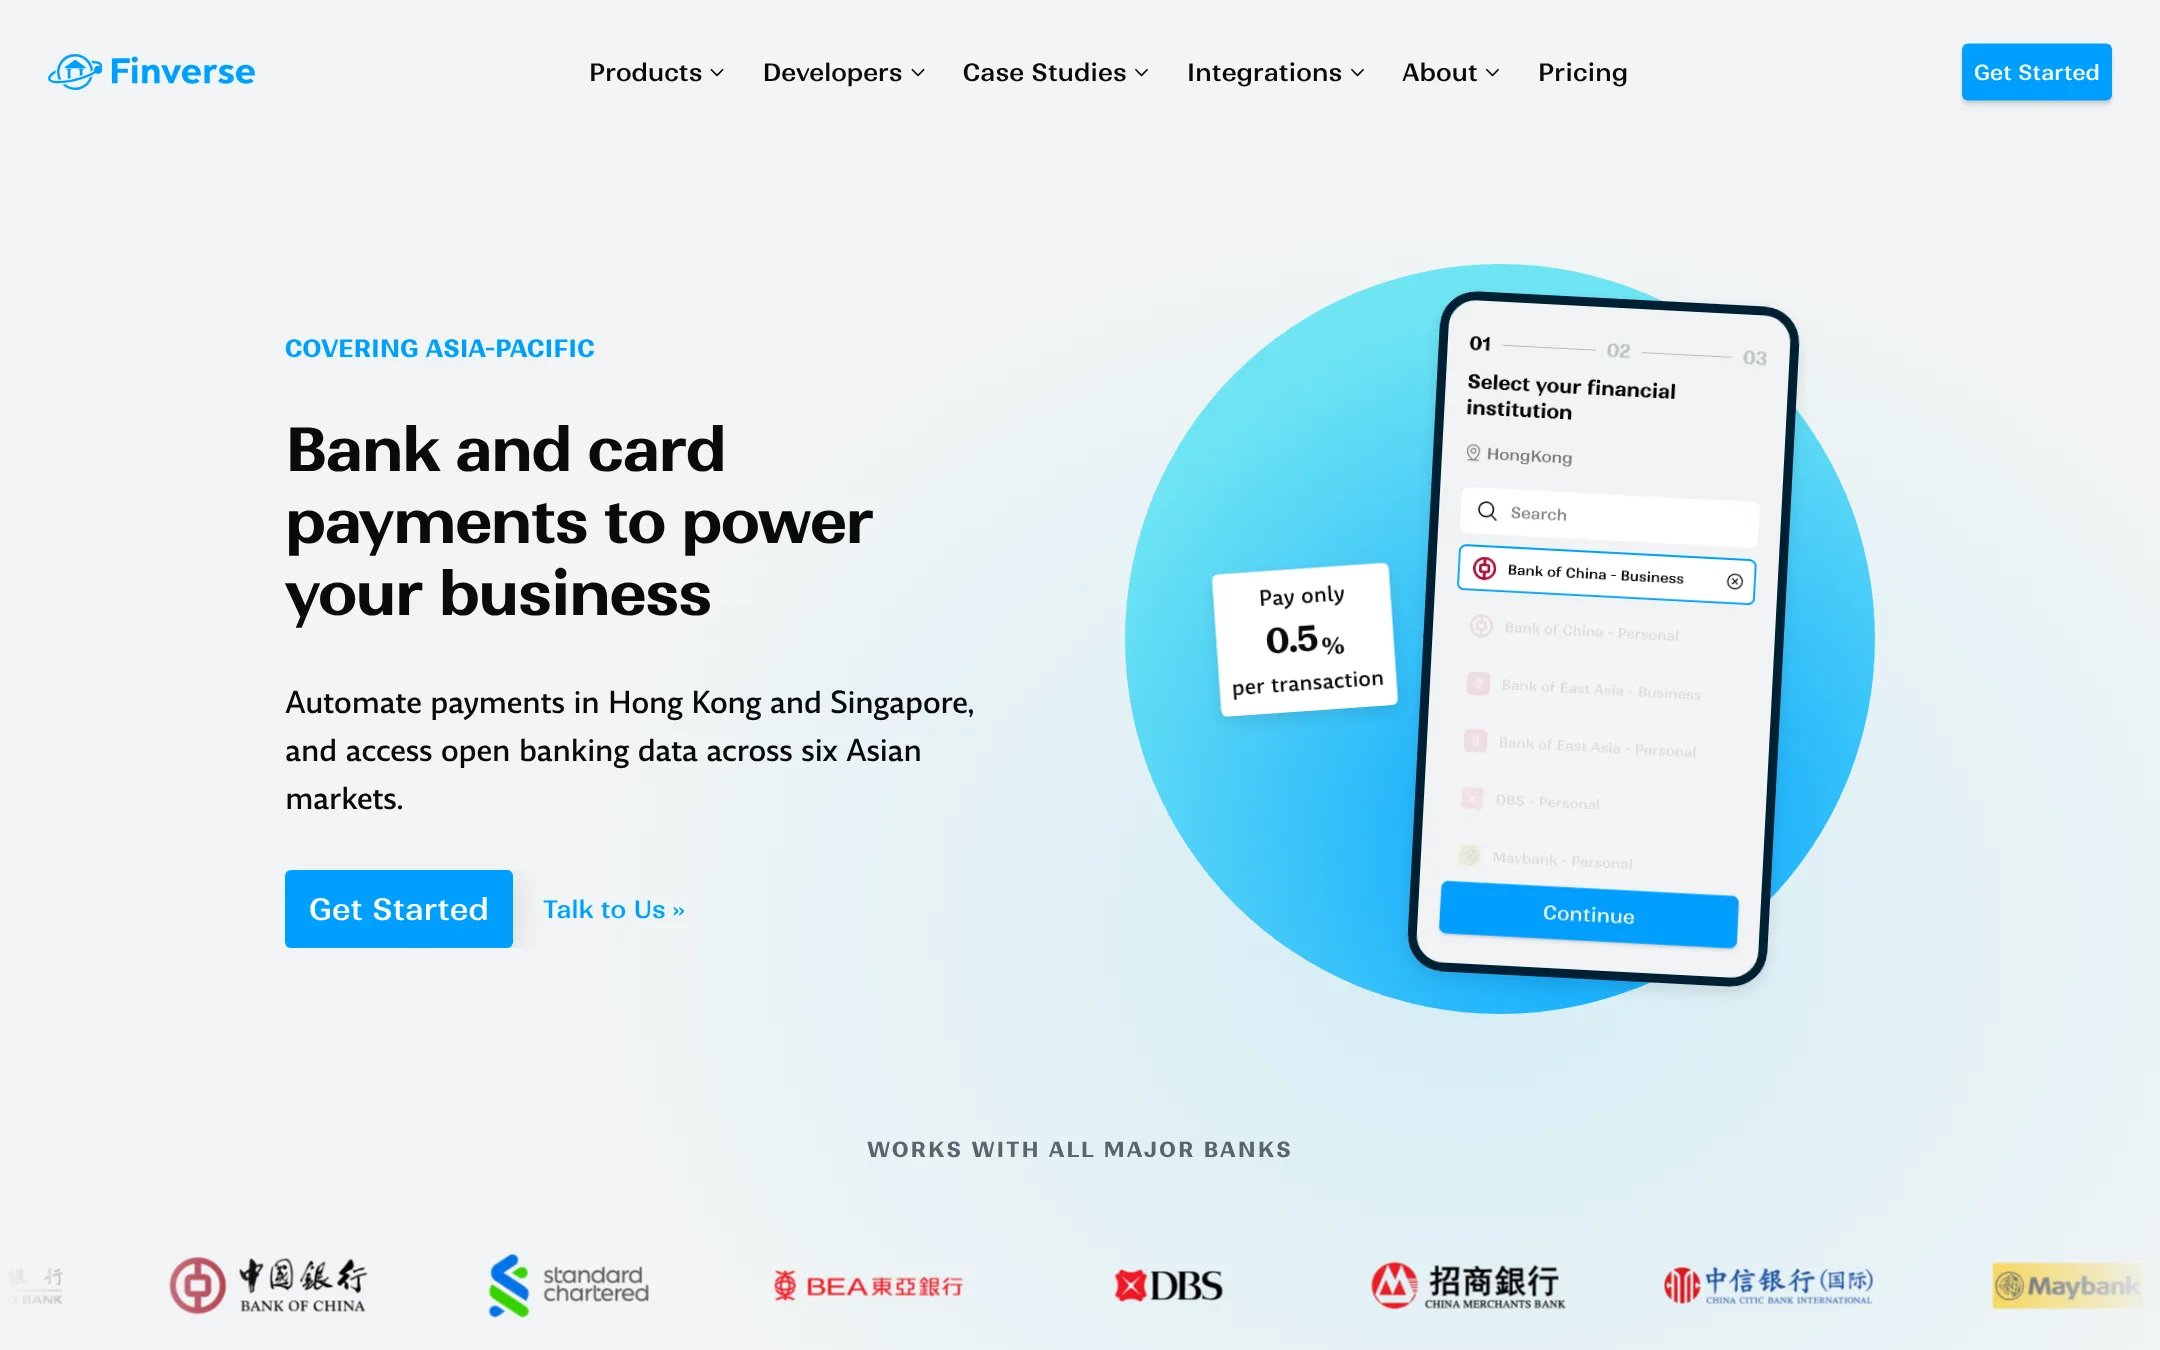
Finverse is an API and dashboard for collecting bank and card payments, with a focus on Hong Kong and Singapore plus open banking data across six Asian markets. You would choose it over Fintoc if your business operates in Asia-Pacific and needs direct debit, payment links, and bank data aggregation from local banks.
Where it is strong
- 85% cheaper than card payments
- Covers 150+ banks in HK and Southeast Asia
- No setup, monthly, or hidden fees
Where it falls short
- Limited to Asia-Pacific markets, not Latin America
- Bank data API covers only 40+ banks, less than the 150+ for payments
- Pricing:
- Standard pricing is 0.5% per transaction, with volume-based custom pricing available for larger volumes.
- PSee website
8.Prometeo
Other
A Latin American open banking platform that offers real-time bank account aggregation and payment initiation.
- KNot published
9.Khipu
Best for: Chilean e-commerce businesses that want instant bank transfer payments and automated recurring billing without card fees.
- Pricing
- Not published
- Category
- Other
Khipu is a Chilean payment platform that lets you receive instant bank transfers without cards or redirects, plus recurring payments and open finance data APIs. Choose it over Fintoc if you want a single provider for both payments and financial data extraction, with over 10 years of local experience and 4,000+ merchants.
Where it is strong
- Payments happen in the same tab, reducing checkout abandonment.
- Supports recurring payments via mandates, not just card subscriptions.
- Offers open finance APIs for bank data, invoices, and risk analysis.
Where it falls short
- Pricing is not transparent on the website.
- Primarily focused on Chile and Argentina, so limited global reach.
- Pricing:
- Pricing is not published on the site.
- Not published
10.Mercado Pago
Best for: Small businesses and sellers in Latin America that want a single account for payments, credit, and investment features.
- Pricing
- Not published
- Category
- Finance & Accounting
Mercado Pago is a digital account and payments platform tied to Mercado Libre, offering card terminals, payment links, and a payment gateway. Choose it over Fintoc if you need a broader set of payment tools like POS hardware and credit products, and you operate in markets where Mercado Pago is available.
Where it is strong
- Includes physical POS terminals and payment links for in-person and online sales.
- Offers credit and financing options for businesses.
- Provides a digital account with potential yield on balances.
Where it falls short
- Pricing details are not publicly listed, making cost comparison harder.
- Tied to the Mercado Libre ecosystem, which may not suit all merchants.
- Pricing:
- Pricing is not published on the site.
See more comparisons in Finance & Accounting alternatives.
FAQ
Questions about Fintoc alternatives
Which alternative is best for Latin America?
Belvo is the strongest for Latin America because it offers financial data and payments across the region. Khipu is a solid choice if you only need Chile. Fintoc itself covers Mexico and Chile, so Belvo gives you broader regional coverage.
Which alternative has the most transparent pricing?
Finverse publishes its pricing at 0.5% per transaction. Most others, including Belvo, Plaid, and Khipu, require contacting sales for a quote. If transparent pricing is a priority, Finverse is the only one with a clear rate.
Can I use these alternatives for recurring payments?
Yes. Fintoc supports subscriptions and recurring billing. Khipu also offers recurring payments via mandates. Finverse supports direct debit. Plaid and TrueLayer do not mention built-in subscription management, so you would need to build that yourself.
Which alternative has the broadest bank coverage?
Salt Edge connects to over 5,000 banks worldwide, which is the widest coverage. Plaid covers 12,000 institutions across 20 countries, but is strongest in the U.S. Finverse covers 150+ banks in Asia-Pacific. Choose based on your operating region.
Do any alternatives offer financial data alongside payments?
Yes. Belvo provides banking, employment, and fiscal data with payments. Khipu offers open finance APIs for bank data and risk analysis. Salt Edge also covers data aggregation and compliance. Plaid focuses on data but also supports payment initiation.
Last updated November 3, 2026.