Method Financial alternatives
6 products compared · Updated November 5, 2026
The short answer
Finch suits software teams that need employee, payroll and benefits data from many HR systems through one API. Plaid suits fintech apps and lenders in the U.S. and other supported markets that need bank account data, payments or identity checks. Yodlee suits banks, wealth managers and fintech apps that need aggregated account data and analytics across many institutions. Method Financial's own focus is consumer credit and liability connectivity with embedded payments, so pick an alternative only if your core need is one of these other data types.
Your shortlist, at a glance
Read the comparisons ↓ PlaidCustom quoteFintech apps and lenders in the U.S. and other supported markets that need bank account data, payments or identity checks
- MMXNot publishedBanks and credit unions that want to grow deposits, loans and card spend from their existing customer data
- FFinicitySee websiteFinancial data solutions
- YYodlee (Envestnet)Not publishedBanks, wealth managers and fintech apps that need aggregated account data and analytics across many institutions
 FinchNot publishedSoftware teams that need employee and payroll data from many HR systems without building each integration themselves
- AAkoyaCustom quoteFintechs and aggregators that need consumer-permissioned data from many banks and credit unions through one connection
About Method Financial and its alternatives
Method Financial provides connectivity to consumer credit and liability accounts, including embedded payments, end-to-end lending experiences, real-time account data intelligence and one-click checkout, according to its site. Its pitch centres on credit cards, loans and mortgages rather than bank deposits or employee records.
When comparing alternatives in this category, weigh the type of account or data you need access to, since some vendors cover bank accounts, others cover payroll or deposit data. Also compare pricing structure (published tiers, usage-based fees or quote-only pricing), regional coverage, which integrations and products are included, the level of support, and contract terms such as month-to-month plans versus long commitments.
Explore the alternatives
- Custom quote
1.Plaid
Best for: Fintech apps and lenders in the U.S. and other supported markets that need bank account data, payments or identity checks
- Pricing
- Custom quote
- Category
- Finance & Accounting
Plaid connects bank and financial accounts to apps so users can share their data safely and with their consent. Teams pick it over Method Financial when the product needs bank-account data, such as payments from a bank account, identity checks, or income and transaction data, rather than connectivity to credit cards, loans and mortgages.
Where it is strong
- Connects to over 12,000 financial institutions across 20 countries, according to the site.
- Covers bank payments, identity, income, transactions and fraud checks in one platform.
- Pay as You Go lets you start in production without a long contract.
Where it falls short
- Its focus is bank and deposit accounts, so it is a weaker fit than Method Financial for consumer credit and liability connectivity.
- Some products, such as Layer and Signal, require contacting Plaid for pricing, and beta products are only on the Custom plan.
- Pricing:
- Plaid's Pay as You Go plan is month-to-month with no upfront commitment, and you pay per connected account or per successful API call depending on the product, but the site does not list exact figures.
- MNot published
2.MX
Best for: Banks and credit unions that want to grow deposits, loans and card spend from their existing customer data
- Pricing
- Not published
- Category
- Other
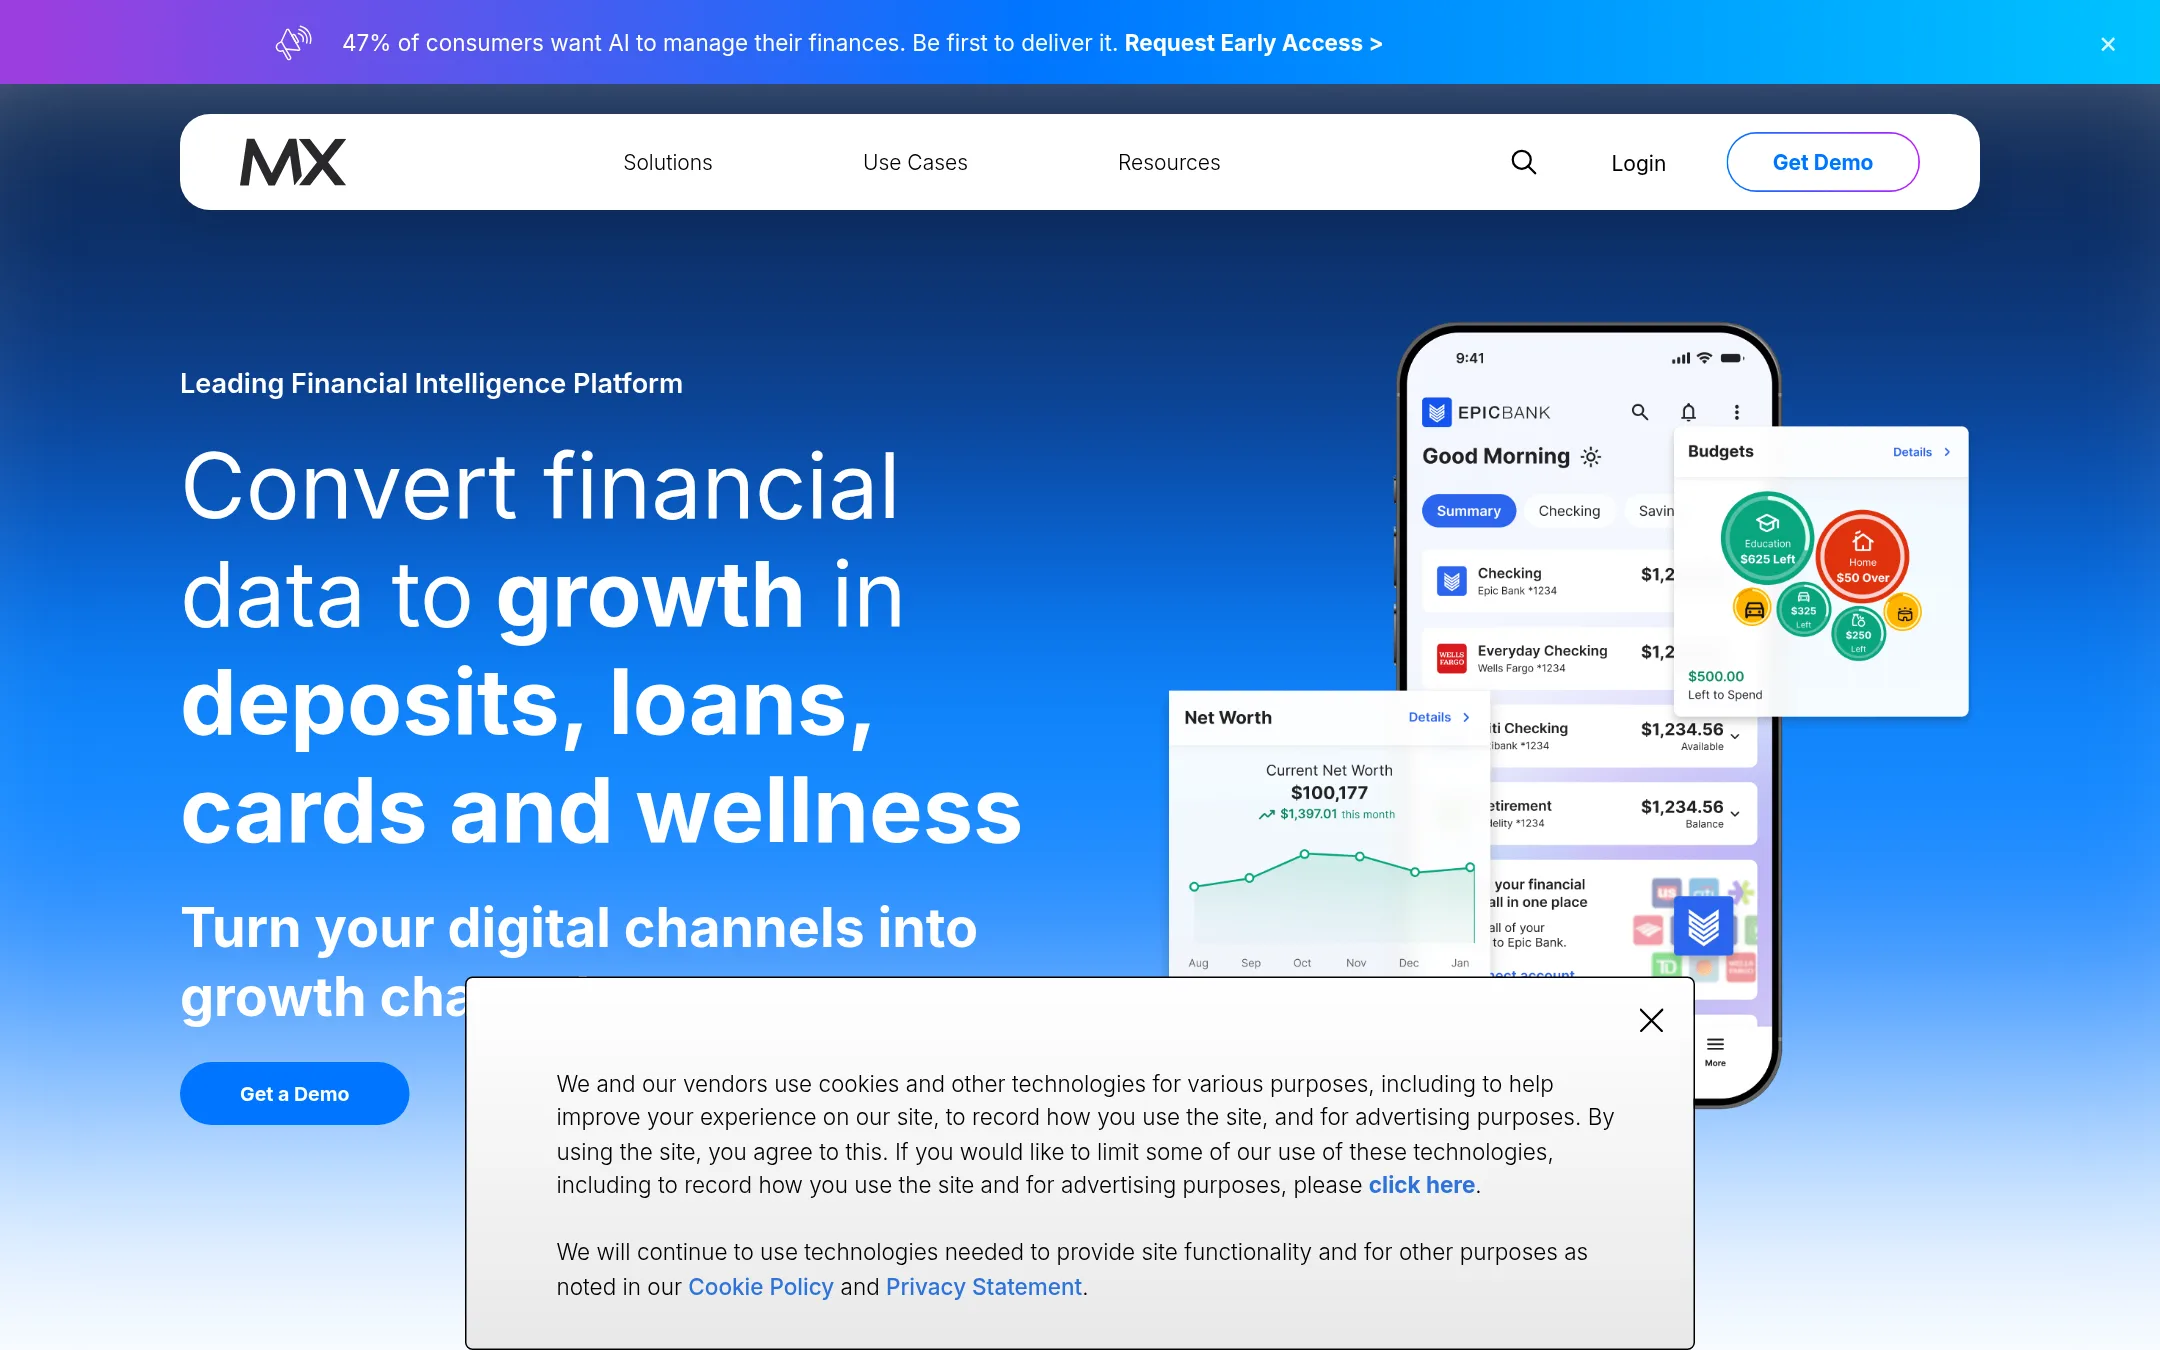
MX is a financial data platform that turns consumer account and transaction data into insight for banks and fintechs. It is aimed at growing deposits, loans, cards and financial wellness rather than at moving money. Pick MX over Method Financial when your main goal is understanding and marketing to existing customers, not embedding payments or lending flows.
Where it is strong
- Built for analytics on account and transaction data to spot customers ready to borrow or move deposits
- Case studies from banks such as BECU and Central Pacific Bank describe direct deposit switch and targeted outreach
- Covers investment holdings and external accounts alongside bank data in one view
Where it falls short
- The site focuses on banks and fintechs, so it is less suited to a startup that needs to embed payments or lending itself
- Method Financial's emphasis on embedded payments and one-click checkout is not part of MX's described offering
- Pricing:
- Pricing is not published on the site.
- FSee website
3.Finicity
Finance & Accounting
Account aggregation and open banking data API, used for income verification and lending decisions, overlapping with Method's account data intelligence.
- YNot published
4.Yodlee (Envestnet)
Best for: Banks, wealth managers and fintech apps that need aggregated account data and analytics across many institutions
- Pricing
- Not published
- Category
- Other
Yodlee connects, enriches and activates financial data for banks, wealth managers, lenders and fintechs. Its products cover personal financial management, credit decisioning from alternative data, payment account verification and open finance APIs. A team would pick Yodlee over Method Financial when it needs broad account aggregation and data analytics for banking or wealth workflows, rather than embedded payments and lending built around consumer credit and liability accounts.
Where it is strong
- Covers personal financial management, credit, wealth, payments and open finance from one vendor
- Built for institutional buyers with a long track record in account aggregation
- Lists named partners such as JPMorganChase and PayPal as customers
Where it falls short
- Aimed mainly at large institutions, so smaller startups may find it hard to access
- Does not present embedded payments or one-click checkout as a core offering the way Method Financial does
- Pricing:
- Pricing is not published on the site.
- Not published
5.Finch
Best for: Software teams that need employee and payroll data from many HR systems without building each integration themselves
- Pricing
- Not published
- Category
- Finance & Accounting
Finch is a unified API that connects to payroll, HR and benefits systems, giving you one standard data format across 250+ providers. Teams choose it over Method Financial when they need employee, payroll or benefits data rather than consumer credit and liability account connectivity.
Where it is strong
- One standard data format covers payroll, HR and benefits from 250+ providers.
- A free sandbox with mock data lets developers test before signing a contract.
- Starter plan has month-to-month contracts with no commitment.
Where it falls short
- Built for employment data, so it does not cover consumer credit or loan accounts the way Method Financial does.
- Write access to deductions and the full provider list are on the Pro plan, not the Starter plan.
- Pricing:
- Pricing is not published on the site.
- ACustom quote
6.Akoya
Best for: Fintechs and aggregators that need consumer-permissioned data from many banks and credit unions through one connection
- Pricing
- Custom quote
- Category
- Other
Akoya is an open finance network that connects apps to bank and credit union data through direct, OAuth-based APIs, so consumers log in at their own bank instead of handing over credentials. Someone would pick it over Method Financial when they need permissioned access to deposit and account data from thousands of institutions for a third-party app, rather than embedded lending and payments on consumer liability accounts.
Where it is strong
- Single connection reaches 4,500+ financial institutions
- Consumers authorize accounts without sharing login credentials
- Free self-service sandbox with test data
Where it falls short
- Pricing details beyond the Standard and Enterprise tiers are not published
- Focused on data sharing, so it does not offer embedded lending or one-click checkout like Method Financial
- Pricing:
- Akoya publishes two tiers: Standard, for up to 10,000 unique connections per month, with custom pricing for Enterprise above that, and a setup or implementation fee may apply.
See more comparisons in Finance & Accounting alternatives.
FAQ
Questions about Method Financial alternatives
What is Method Financial known for?
According to its site, Method Financial provides connectivity to consumer credit and liability accounts, with embedded payments, lending experiences, account data intelligence and one-click checkout. Its focus is credit cards, loans and mortgages rather than bank deposit accounts or employee data.
Which alternative is best for bank account data and payments?
Plaid is the entry aimed at this need. It connects bank and financial accounts to apps with user consent, and covers bank payments, identity, income and transaction data. The site says it connects to over 12,000 institutions across 20 countries.
Can I use one of these tools for employee payroll data?
Finch is built for that purpose. It is a unified API that connects to payroll, HR and benefits systems across 250+ providers using one standard data format. It does not cover consumer credit or loan accounts the way Method Financial does.
Which option suits banks and credit unions that want to grow their customer relationships?
MX is aimed at banks and credit unions that want to grow deposits, loans and card spend from existing customer data. Yodlee is another option for institutions needing aggregated account data and analytics across many providers. Both emphasise analytics more than embedded payments or checkout.
How do I compare pricing across these alternatives?
Pricing varies a lot. Plaid offers a Pay as You Go plan with no upfront commitment, and Akoya publishes Standard and Enterprise tiers, but the exact figures are not listed. Finch, MX and Yodlee do not publish pricing, so you will need to request a quote from each vendor.
Last updated November 5, 2026.