Mono alternatives
9 products compared · Updated November 8, 2026
The short answer
The three strongest alternatives to Mono are Stripe, Adyen and Wompi. Stripe suits global online businesses and SaaS companies that need card, wallet and local methods across many currencies. Adyen suits global enterprises that want one payments platform across many markets. Wompi suits Colombian merchants that mainly need payment links or a checkout button for online sales.
Your shortlist, at a glance
Read the comparisons ↓ StripeFrom 2.9% + 30¢Global online businesses and SaaS companies that need card, wallet and local payment methods across many currencies
- WWompiNot publishedColombian merchants that sell online and want payment links or a checkout button without building a custom integration
PayUCustom quoteIndian e-commerce and D2C brands that need UPI, cards and EMI at checkout
- BBoldNot publishedJob seekers who need resume, cover letter, or job search help rather than payment infrastructure
- NNequiNot publishedIndividuals and micro-sellers in Colombia who want a phone-first wallet for personal payments and simple cash receipts
 AdyenNot publishedGlobal enterprises and scaling SaaS, retail and travel businesses that need one payments platform across many currencies and markets
 NombaNot publishedNigerian small businesses and retailers that take card payments in store and online and want a business bank account with overdrafts.
 FlutterwaveNot publishedBusinesses selling to customers across several African countries that need one provider for collections and payouts
- PPaystackNot publishedOnline and offline merchants in Africa that need to collect payments from many local channels through one gateway
About Mono and its alternatives
Mono is embedded finance infrastructure for Latin American enterprises. According to its site, it is known for a single integration that covers collections, payouts, Bre-B instant payments, branded digital wallets and Visa cards, with a focus on Colombia.
When comparing alternatives in this category, weigh the pricing structure, which regions the provider covers, which integrations and payment methods it supports, the level of support, and the contract terms. Several providers on this page do not publish prices, so ask for a quote before deciding.
Explore the alternatives
- From 2.9% + 30¢
1.Stripe
Best for: Global online businesses and SaaS companies that need card, wallet and local payment methods across many currencies
- Pricing
- From 2.9% + 30¢
- Category
- Finance & Accounting
Stripe is a general payments and financial infrastructure platform used by businesses of all sizes for accepting payments, billing, card issuing and payouts. Teams usually pick Stripe over Mono when they sell across many countries and need a broad set of payment methods, billing tools and developer APIs in one place.
Where it is strong
- Supports 135+ currencies and payment methods
- Broad product set covering billing, card issuing, disputes and payouts
- Published developer documentation and SDKs for building custom integrations
Where it falls short
- Its pricing page covers many products, so the total cost depends on which ones you use
- Mono's focus on Colombia and Bre-B direct connections is not part of Stripe's offer as described on the page
- Pricing:
- The site lists a standard rate of 2.9% + 30¢ per successful domestic card transaction, with international cards, currency conversion and other products priced separately.
- Switching from Mono:
- Moving from Mono to Stripe would mean rebuilding payment flows on Stripe's APIs, and the pages supplied do not describe a migration path.
- WNot published
2.Wompi
Best for: Colombian merchants that sell online and want payment links or a checkout button without building a custom integration
- Pricing
- Not published
- Category
- Other
Wompi is a payments gateway backed by the Bancolombia ecosystem. It offers payment links, a payment button, online card and other electronic payment methods, and a Tap to Pay option on iPhone. A company might pick Wompi over Mono when its main need is accepting customer payments online through a standard checkout rather than moving money in bulk across a business.
Where it is strong
- Payment links can be shared by social media, SMS or email
- Holds PCI DSS certification for card transactions
- Backed by the Bancolombia ecosystem
Where it falls short
- The site does not describe payouts or bulk disbursements to drivers, suppliers or payroll the way Mono does
- No mention of embedded wallets or white-label cards on the site
- Pricing:
- Pricing is not published on the site.
- Custom quote
3.PayU
Best for: Indian e-commerce and D2C brands that need UPI, cards and EMI at checkout
- Pricing
- Custom quote
- Category
- Finance & Accounting
PayU is a payments platform built for India. It takes card, UPI, net banking, wallet and BNPL payments through one gateway, and adds payouts, subscriptions, POS and split settlements. A team would pick it over Mono when its customers and money flows are mainly in India and they want UPI, EMI and consumer checkout options in one place.
Where it is strong
- Covers 150+ payment methods, including UPI, cards, net banking, wallets, EMI and BNPL.
- Offers payouts, split settlements and instant refunds for marketplaces and sellers.
- Has ready-made plugins, including Shopify, and a no-code option for merchants.
Where it falls short
- Its footprint is India-focused, so it is a weaker fit for Colombia or other LatAm markets than Mono.
- Its product set is aimed at consumer checkout, so it lacks Mono's branded wallet and Visa card issuing.
- Pricing:
- Pricing is not published as figures on the site. It offers a Standard plan with no setup or annual maintenance fee and a custom-priced Enterprise plan, with UPI pricing varying by business type and volume.
- BNot published
4.Bold
Best for: Job seekers who need resume, cover letter, or job search help rather than payment infrastructure
- Pricing
- Not published
- Category
- Other
Bold is a set of career tools for job seekers. It includes AI-powered resume and cover letter builders, job search sites, networking platforms, and productivity tools. Someone would pick Bold over Mono only if they are looking for help with job searching, not for moving money. Bold does not offer payments, collections, or card issuing.
Where it is strong
- Covers resume and cover letter building with AI-assisted tools
- Includes job search and networking products in one place
- Serves users in many countries and languages
Where it falls short
- Offers no payment, collection, or card products, so it does not replace Mono
- The site describes consumer career tools and does not describe business or enterprise plans
- Pricing:
- Pricing is not published on the site.
- NNot published
5.Nequi
Best for: Individuals and micro-sellers in Colombia who want a phone-first wallet for personal payments and simple cash receipts
- Pricing
- Not published
- Category
- Other
Nequi is a consumer digital wallet and savings account from Colombia, used from a phone for paying bills, sending money, buying SOAT insurance, and getting a Visa debit card. It is built for individuals and small sellers who want a personal money app. A founder would pick it over Mono only if they need a personal or simple receiving account for their own use, not embedded payments, bank-grade collections, or a white-label wallet for their own customers.
Where it is strong
- Used from a phone with no branch visits needed
- Savings account listed with no maintenance fee and no minimum balance
- Visa debit card with a virtual option and a physical option
Where it falls short
- Built for individual users, not for embedding payments into another product
- Does not offer white-label wallets or branded cards for a company's own customers
- Pricing:
- Pricing is not published on the site.
- Not published
6.Adyen
Best for: Global enterprises and scaling SaaS, retail and travel businesses that need one payments platform across many currencies and markets
- Pricing
- Not published
- Category
- Finance & Accounting
Adyen is a global payments platform that handles acceptance, settlement, payouts and financial products like card issuing and capital through one API. A company would pick Adyen over Mono when it sells across many countries and needs one provider to cover many currencies and local payment methods, rather than a Colombia-focused stack.
Where it is strong
- Supports 150+ currencies and 200+ local payment methods
- Published 99.999% historical uptime and banking licenses in the US, UK and EU
- Payments, payouts, card issuing and capital run on one platform
Where it falls short
- Pricing details shown on the site are indicative and require talking to sales for an actual quote
- The site does not describe a Colombia or Bre-B offering the way Mono does
- Pricing:
- Pricing is not published on the site.
- Not published
7.Nomba
Best for: Nigerian small businesses and retailers that take card payments in store and online and want a business bank account with overdrafts.
- Pricing
- Not published
- Category
- Finance & Accounting
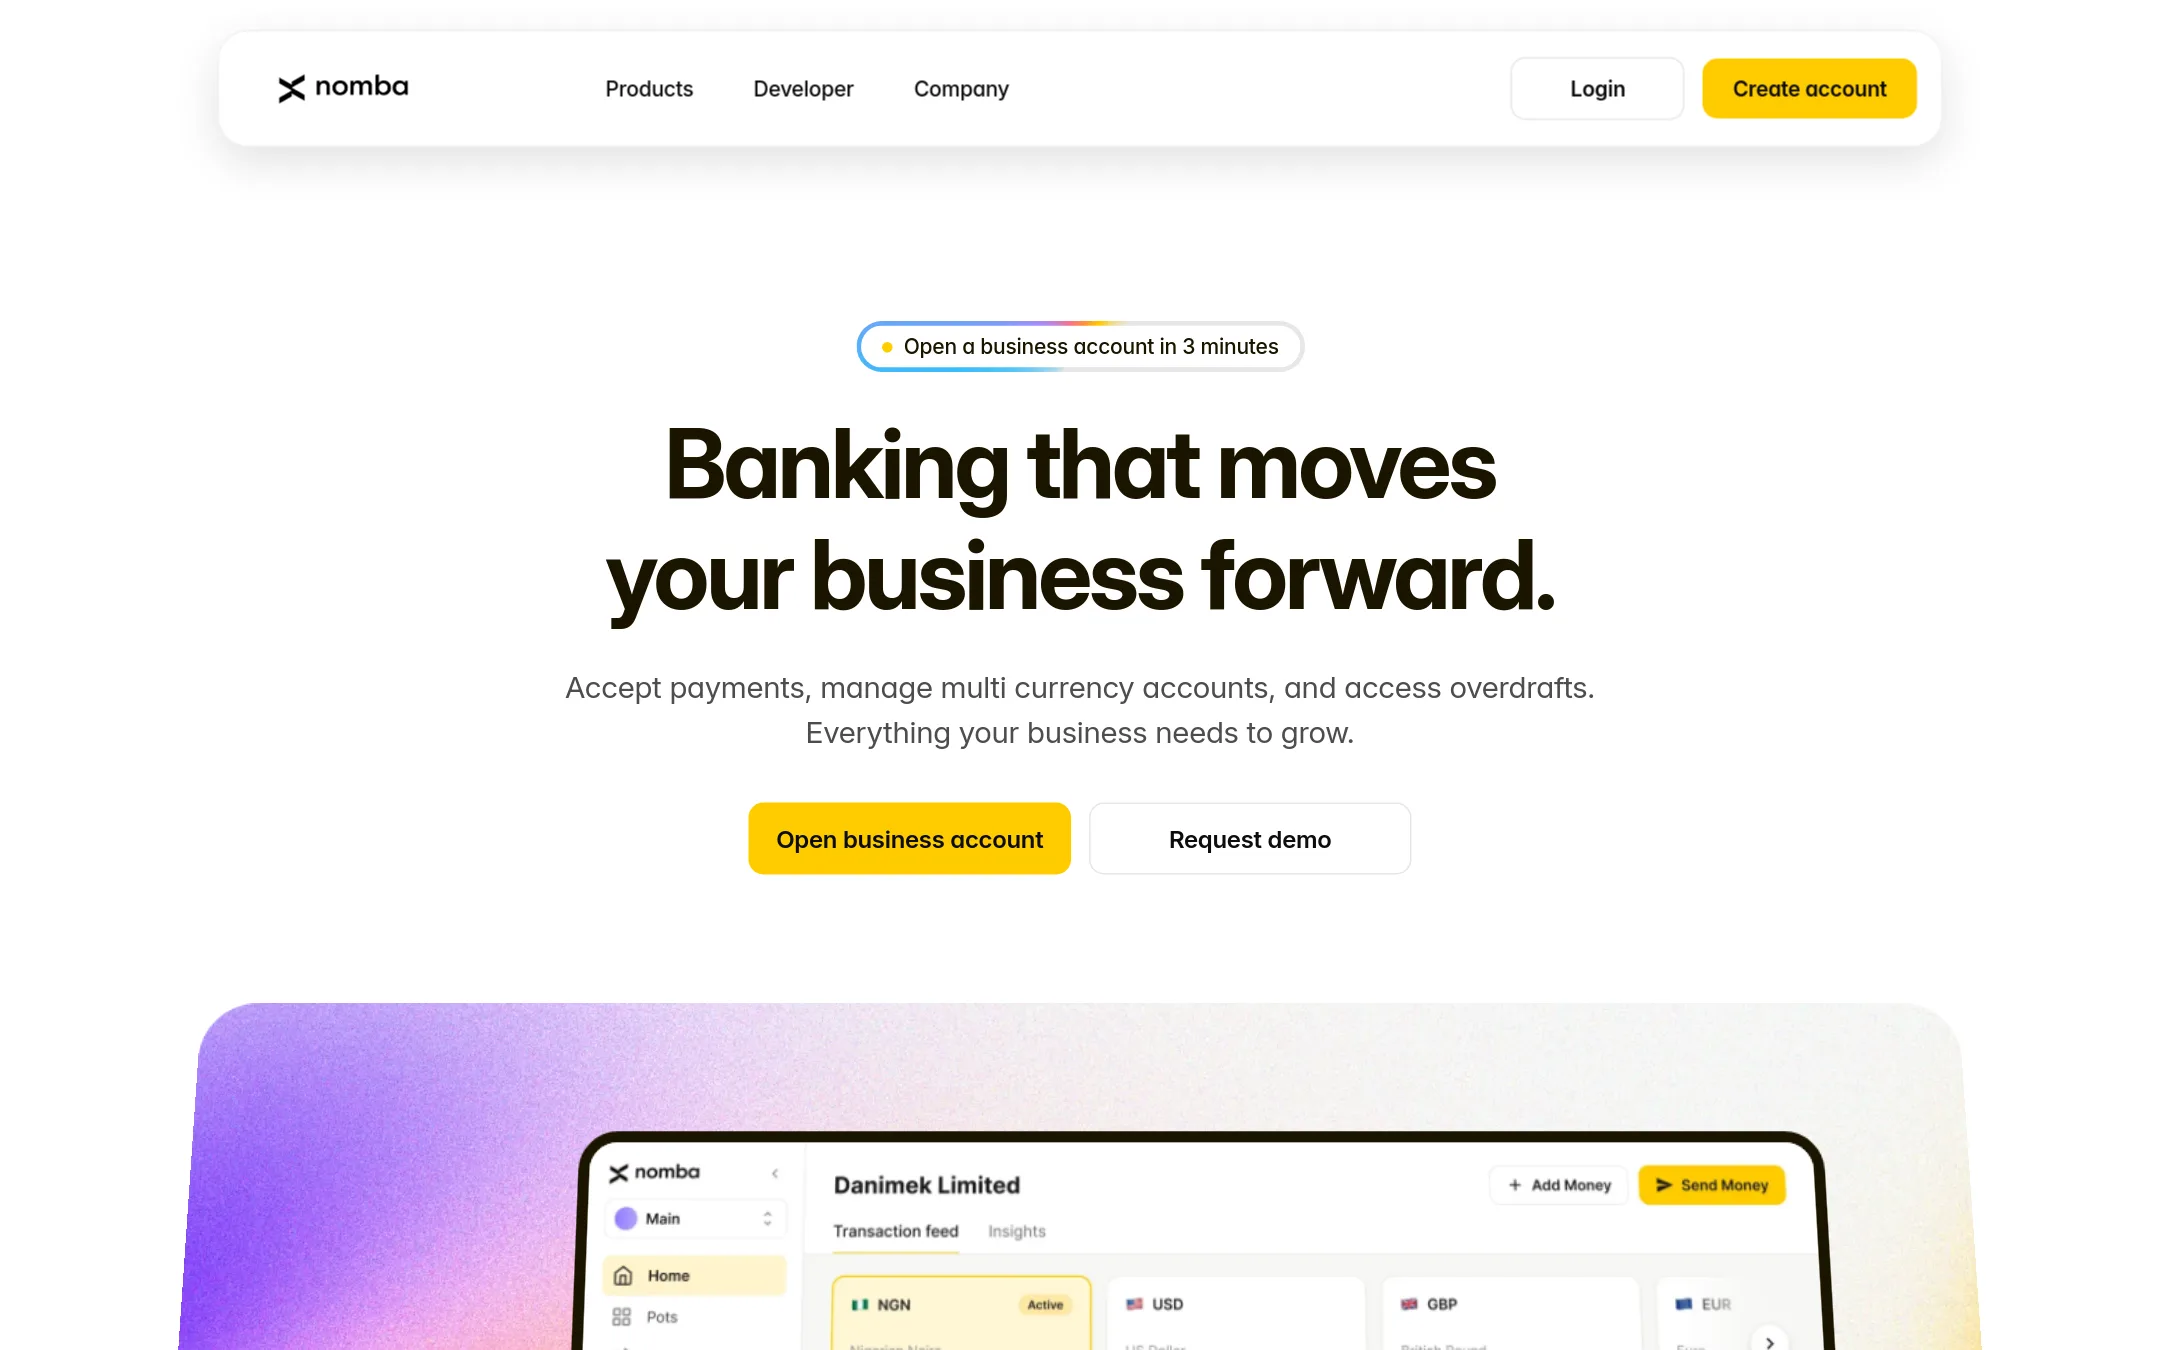
Nomba is a Nigerian business bank account with POS terminals, online checkout, payment links, USD and NGN wallets, overdrafts and yield on balances. Choose it over Mono when the business sells in Nigeria and wants a bank account, card terminals and short-term credit in one app rather than an embedded payments layer for building your own product.
Where it is strong
- Business account opens in about three minutes, with most approvals the same day.
- Holds NGN and USD wallets and offers an overdraft based on sales history, with no collateral.
- Covers POS, payment links, USSD and bank transfer from one account.
Where it falls short
- Built around Nigeria, so it does not cover the Colombian rails Mono focuses on, such as Bre-B.
- Offers no white-label wallet or branded card issuing like Mono's embedded products.
- Pricing:
- Pricing is not published on the site.
- Not published
8.Flutterwave
Best for: Businesses selling to customers across several African countries that need one provider for collections and payouts
- Pricing
- Not published
- Category
- Finance & Accounting
Flutterwave is a payments platform for businesses that take and send money across Africa. A company would pick it over Mono when its customers are spread across several African markets and it needs one provider for collections and payouts there. Mono's own page is built around Colombia and Latin America, so Flutterwave is the more natural fit for an African footprint.
Where it is strong
- Built for making and accepting payments across Africa
- Serves enterprises, small businesses, and startups alike
- Positioned for emerging markets
Where it falls short
- Coverage is African markets, so it does not help with Colombia or wider Latin America
- Pricing is not published, so costs need a direct conversation
- Pricing:
- Pricing is not published on the site.
- PNot published
9.Paystack
Best for: Online and offline merchants in Africa that need to collect payments from many local channels through one gateway
- Pricing
- Not published
- Category
- Finance & Accounting
Paystack lets businesses in Africa collect payments from customers through many channels, including cards, bank transfers, USSD, mobile money and Apple Pay or Google Pay. Teams choose it when they sell across several African markets and want one gateway with well-documented APIs, fraud detection and reconciliation reports. Mono is the stronger fit for Colombian companies that need embedded accounts, Bre-B instant payments and white-label cards.
Where it is strong
- Accepts cards, bank transfers, USSD, mobile money and QR payments
- Routes payments through the most suitable channels to raise transaction success rates
- Offers documented APIs for one-time and recurring payments and instant transfers
Where it falls short
- Focused on collecting payments rather than managing embedded accounts or payouts
- Does not mention Colombia or Bre-B support, so it is not a match for Colombian operations
- Pricing:
- Pricing is not published on the site.
See more comparisons in Finance & Accounting alternatives.
FAQ
Questions about Mono alternatives
What is Mono best known for?
According to its site, Mono centralizes how Colombian companies move money, from collection to payment, through one integration. Its listed features include Bre-B participation, white-label wallets and Visa cards with the client's brand.
Which alternative is best for a company selling across many countries?
Stripe and Adyen are the closest fits for global operations. Stripe covers many currencies and payment methods alongside billing and card issuing. Adyen covers 150+ currencies and 200+ local payment methods through one platform.
Which alternative is best for a Colombian merchant that only needs to accept online payments?
Wompi fits this case. It offers payment links, a payment button and online card payments, and is backed by the Bancolombia ecosystem. It does not describe bulk payouts or white-label wallets the way Mono does.
Do any of these alternatives cover Bre-B?
None of the entries on this page describe Bre-B support. Mono's site presents Bre-B as one of its core features, so compare that point directly with any provider you are considering.
Is pricing comparable across these providers?
Not directly. Stripe publishes a standard domestic card rate of 2.9% + 30¢, while most other entries do not publish prices. Mono's pricing is not shown on its site either, so request written quotes from each provider before comparing costs.
Last updated November 8, 2026.