Munify alternatives
8 products compared · Updated November 13, 2026
The short answer
Stripe suits SaaS and subscription businesses that need online checkout and recurring billing. Payoneer suits marketplaces and e-commerce sellers that need to pay or get paid across many countries. Airwallex suits growing global businesses that want multi-currency accounts, corporate cards and accounting sync in one platform.
Your shortlist, at a glance
Read the comparisons ↓- WWiseFrom 0.23% + fixed feeIndividuals and businesses that send and spend money across many countries and currencies, including relocators and frequent senders
 RevolutNot publishedIndividuals and freelancers who want one app for daily banking, multi-currency spending and investing
 PayoneerFrom 1.2% + fees by coMarketplaces and e-commerce sellers that need to pay or get paid across many countries
- AAirwallexFree to $12/user/moGrowing global businesses in the US that need multi-currency accounts, corporate cards and accounting sync in one platform
- RRemitlyNot publishedIndividuals sending money home and small businesses paying contractors in many countries that need bank, wallet or cash payout options
 PayPalNot publishedConsumers and US-based shoppers who want checkout, peer payments and rewards in one app
 StripeFrom 2.9% + 30¢SaaS and subscription businesses that need online checkout, recurring billing, and dispute handling across many payment methods
- NNiumNot publishedFintechs, banks and platforms that need to embed cross-border payouts and card programs into their own product.
About Munify and its alternatives
Munify is a cross-border neobank for the Middle East. According to its site, it offers multi-currency accounts, virtual cards, invoicing, and send and receive payments, powered by stablecoins and blockchain rails. It states that businesses can open a US account without residency or a US address, and it lists coverage in the United Arab Emirates, India, Egypt, Europe, the United States and England.
When comparing alternatives, weigh the pricing structure first, since some providers publish per-transaction rates while others keep pricing private. Check which countries and currencies each product covers, especially for the corridors you use. Look at integrations with your accounting software, the quality of support, and any contract terms or minimums before you commit.
Explore the alternatives
- WFrom 0.23% + fixed fee
1.Wise
Best for: Individuals and businesses that send and spend money across many countries and currencies, including relocators and frequent senders
- Pricing
- From 0.23% + fixed fee
- Category
- Other
Wise is an international account for holding, converting, sending and spending money in many currencies. Someone would pick it over Munify when they want broad country coverage and local account details in many currencies, or when they mainly need transfers and a multi-currency card rather than a business account built around the Middle East.
Where it is strong
- Account details in 22 currencies, so you can receive like a local.
- Transfers and conversions use the mid-market exchange rate, with fees shown upfront.
- Works with 150+ countries and 40 currencies, a wider footprint than Munify's Middle East focus.
Where it falls short
- Receiving USD or GBP by Swift carries a fixed fee per payment.
- ATM withdrawals beyond 250 USD a month in a calendar month carry a fee plus a percentage.
- Pricing:
- In the United States, sending money starts from 0.23% depending on currency, the Multi-Currency Card has no subscription fee and costs 9 USD to get, and holding money is free.
- Not published
2.Revolut
Best for: Individuals and freelancers who want one app for daily banking, multi-currency spending and investing
- Pricing
- Not published
- Category
- Finance & Accounting
Revolut is a consumer and personal-finance app that offers multi-currency accounts, savings, investing and virtual cards in one place. Someone would pick it over Munify if they want a mainstream banking app with stock and ETF trading and savings plans, rather than a platform built around cross-border business payments and stablecoin rails.
Where it is strong
- Holds up to 36 currencies in app and spends in 150+ currencies
- Sends money to 160+ countries
- Offers 5,000+ stocks and ETFs for investing alongside banking
Where it falls short
- The site focuses on personal banking, with less emphasis on business invoicing and payouts than Munify
- Some features and savings rates depend on plan type and region, and investing carries capital risk
- Pricing:
- Pricing is not published on the site.
- From 1.2% + fees by co
3.Payoneer
Best for: Marketplaces and e-commerce sellers that need to pay or get paid across many countries
- Pricing
- From 1.2% + fees by co
- Category
- Finance & Accounting
Payoneer is a cross-border payments platform for businesses, marketplaces, and freelancers, covering receiving and sending payments in 190+ countries and 70+ currencies, plus corporate cards and workforce payments. Someone would pick it over Munify when they need broad country coverage, mass marketplace payouts, or a payments setup that already works with platforms like Fiverr or Wish.
Where it is strong
- Coverage across 190+ countries and territories and 70+ currencies
- Mass payouts and integrations suited to marketplaces at scale
- Corporate cards, workforce onboarding, and working capital in one platform
Where it falls short
- Fees vary widely by corridor and payment method, which makes costs harder to predict
- Some fixed fees and minimums apply in certain countries
- Pricing:
- Pricing is published by corridor and payment method, with receiving from a credit card up to 3.99% + 0.49 USD, sending to a bank account in a different currency typically 1.2% to 4%, and an annual card fee of 29.95 USD.
- AFree to $12/user/mo
4.Airwallex
Best for: Growing global businesses in the US that need multi-currency accounts, corporate cards and accounting sync in one platform
- Pricing
- Free to $12/user/mo
- Category
- Other
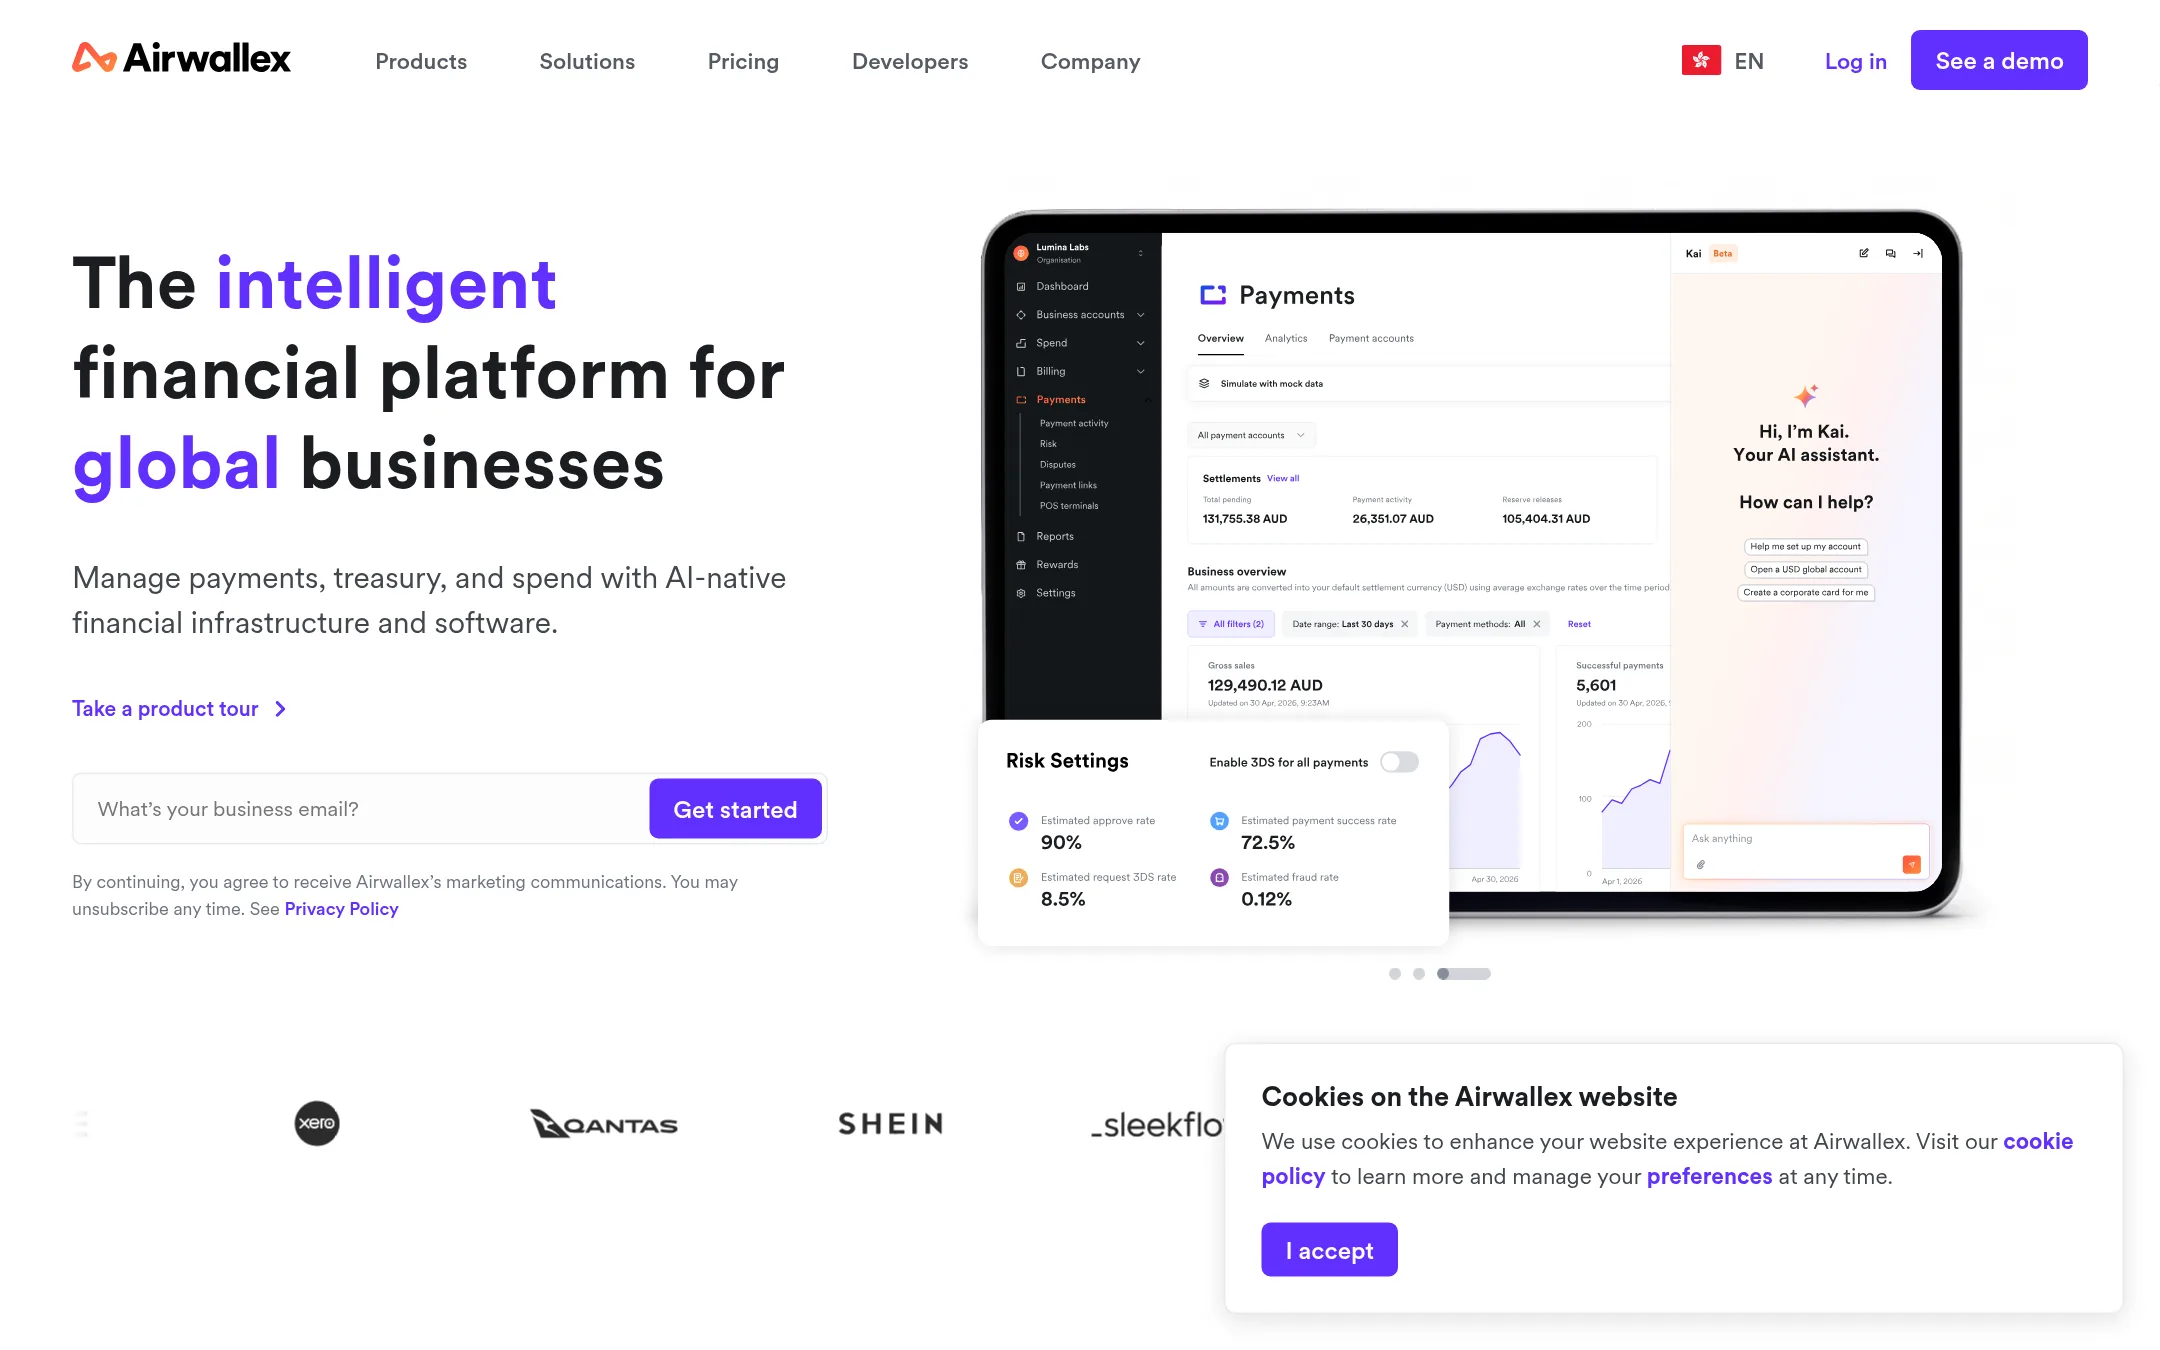
Airwallex is a global financial platform that combines business accounts, FX and transfers, corporate cards, expense management, payments and billing. A team would pick it over Munify when it needs deep accounting integrations with Xero, QuickBooks, NetSuite or Dynamics 365, a broad set of local payment methods for online checkout, or spend controls and approval workflows for a larger finance team.
Where it is strong
- Business accounts in 20+ currencies with transfers to 120+ countries
- Syncs bank feeds, expenses and bills with Xero, QuickBooks, NetSuite and Dynamics 365
- Accepts 160+ local payment methods for online payments
Where it falls short
- Advanced spend approvals and budgeting sit on the paid Grow tier and above
- Some features such as the accounting hub and budget tracking are listed as coming soon
- Pricing:
- In the United States, the Explore plan is free with no monthly per-user fee, the Grow plan is $12 per user per month plus a platform fee based on team size, and Enterprise pricing is custom.
- RNot published
5.Remitly
Best for: Individuals sending money home and small businesses paying contractors in many countries that need bank, wallet or cash payout options
- Pricing
- Not published
- Category
- Other
Remitly is a consumer and small-business money transfer service covering over 175 countries, with options to send to bank accounts, mobile wallets or cash pickup. Someone would pick Remitly over Munify when the main need is sending money to family or paying vendors in a wide range of destination countries, especially where cash pickup or mobile wallet delivery matters.
Where it is strong
- Coverage in over 175 countries with more than 100 currencies
- Delivery to bank accounts, mobile wallets or cash pickup in 130+ countries
- Support available in 18 languages
Where it falls short
- Sending is available from a limited list of origin countries, and the list does not include the UAE, Egypt or India
- The site describes its business product as paying contractors and vendors, not as a full multi-currency account with virtual cards
- Pricing:
- Pricing is not published on the site.
- Not published
6.PayPal
Best for: Consumers and US-based shoppers who want checkout, peer payments and rewards in one app
- Pricing
- Not published
- Category
- Finance & Accounting
PayPal is a consumer and small-merchant wallet for paying friends, checking out online, and earning cash back. Someone would pick it over Munify when the need is everyday spending, checkout on other sites, or rewards from brands, rather than running a multi-currency business account for cross-border payments.
Where it is strong
- Pay in 4 and monthly financing options, with a PayPal Credit Card for larger purchases
- Cash back offers from named brands and a debit card with category rewards
- Send, request and pool money with friends from the same app
Where it falls short
- Its homepage focuses on US consumers, with no multi-currency business account described
- Cross-border business payments and receiving USD without a US address are not covered on the page
- Pricing:
- Pricing is not published on the site.
- From 2.9% + 30¢
7.Stripe
Best for: SaaS and subscription businesses that need online checkout, recurring billing, and dispute handling across many payment methods
- Pricing
- From 2.9% + 30¢
- Category
- Finance & Accounting
Stripe is financial infrastructure for businesses that want to accept payments, run subscriptions, and embed payments into their own product. Teams choose it over Munify when their main need is online checkout, recurring billing, or payments built into a software platform, rather than a cross-border account for holding and moving multiple currencies.
Where it is strong
- Accepts 135+ currencies and payment methods, including digital wallets and local options.
- Covers billing models such as subscriptions and usage-based pricing.
- Offers APIs and prebuilt tools that let developers embed payments in their own platform.
Where it falls short
- Its account and money-movement features are built around payments, not a multi-currency neobank for holding balances.
- Per-transaction fees add up for businesses with many small payments.
- Pricing:
- The standard rate for domestic cards is 2.9% + 30¢ per successful transaction, with higher rates for international cards and currency conversion, and custom pricing is available for larger accounts.
- NNot published
8.Nium
Best for: Fintechs, banks and platforms that need to embed cross-border payouts and card programs into their own product.
- Pricing
- Not published
- Category
- Other
Nium is a cross-border payments infrastructure company aimed mainly at banks, fintechs, payroll providers, marketplaces and platforms that want to embed global payouts, multi-currency accounts and card programs through its own integration. Someone would pick Nium over Munify when they are building a product for many users or a platform that pays people worldwide, rather than managing their own business or personal money in one app.
Where it is strong
- Payouts to 190+ countries in local currencies and methods.
- Multi-currency accounts covering 100+ currencies, with conversion across 2,000+ currency pairs.
- Physical and virtual card programs in 30+ markets, plus stablecoin cards and stablecoin payouts.
Where it falls short
- Built as infrastructure for businesses, so it is not a direct consumer or freelancer app like Munify.
- The site lists a Nium for SMB offering, but the main product set is aimed at enterprises and platforms.
- Pricing:
- Pricing is not published on the site.
See more comparisons in Finance & Accounting alternatives.
FAQ
Questions about Munify alternatives
Which alternative is best for a SaaS business that mainly needs to collect subscription payments?
Stripe is built for online checkout, recurring billing, and dispute handling across many payment methods. Its standard domestic card rate is 2.9% plus 30 cents per successful transaction, with higher rates for international cards and currency conversion. It is a stronger fit than Munify when payments are the core need rather than a multi-currency account.
Which option covers the most countries for paying or receiving money?
Payoneer covers 190+ countries and territories and 70+ currencies, and suits marketplaces that run payouts at scale. Nium also offers payouts to 190+ countries, but it is aimed at fintechs and platforms that embed payments into their own product. Fees on Payoneer vary by corridor and payment method, so costs are harder to predict.
Which alternative works best for a growing business that wants accounting integrations and corporate cards?
Airwallex combines business accounts in 20+ currencies, corporate cards, and expense management, and syncs with Xero, QuickBooks, NetSuite and Dynamics 365. Its Explore plan is free with no monthly per-user fee, while the Grow plan costs $12 per user per month plus a platform fee. Advanced spend approvals sit on the paid tiers.
Which option is better for individuals who want everyday banking and investing in one app?
Revolut suits individuals and freelancers who want one app for daily banking, multi-currency spending and investing. It holds up to 36 currencies, spends in 150+ currencies, and offers 5,000+ stocks and ETFs. Investing carries capital risk, and some features depend on plan type and region.
Which alternative is best for sending money home to family, including cash pickup?
Remitly covers over 175 countries and can deliver to bank accounts, mobile wallets or cash pickup in 130+ countries. It is built for personal transfers and paying contractors. Its origin-country list does not include the UAE, Egypt or India, so check eligibility before choosing it.
Last updated November 13, 2026.