nCino alternatives
12 products compared · Updated November 1, 2026
The short answer
For community banks and credit unions, Bankjoy and Q2 are the strongest nCino alternatives, with Bankjoy excelling in member-facing digital banking and Q2 offering a broader platform with built-in fraud detection. For a full banking stack that includes core processing and payments, Jack Henry is the best fit. Salesforce suits teams needing a general-purpose CRM with AI, not banking-specific loan origination.
Your shortlist, at a glance
Read the comparisons ↓ SalesforceCustom quoteTeams that want a flexible CRM platform with AI agents and deep integrations across many business functions.
 TemenosNot publishedBanks and credit unions that need a complete core banking system with digital and payments capabilities, rather than a point solution for commercial lending.
- FFiserv Digital BankingNot publishedFinancial institutions and enterprises that need banking technology plus global payments and merchant acquiring in one vendor.
 Jack HenryNot publishedCommunity banks and credit unions that want a cloud-native platform to unify core banking, digital services, and payments while transitioning gradually.
Q2Not publishedBanks and credit unions that want a single platform for digital banking, fraud detection, and commercial onboarding rather than a dedicated loan origination system.
 MambuNot publishedFintechs and banks that want to assemble a custom cloud banking stack with flexible product configuration.
- BBackbaseNot publishedBanks and financial institutions that want to unify frontline banking operations across multiple segments.
- FFinastraSee websiteFinancial technology solutions
- SSAPNot publishedLarge enterprises that need an integrated ERP with AI-driven automation across finance, supply chain, and HR, not just banking workflows.
- OOracle Cloud HPCNot publishedEngineering and research teams that need high-performance compute clusters on Oracle Cloud infrastructure.
 FIS Digital BankingNot publishedBanks and financial institutions that want core banking, payments, and treasury in one vendor.
 BankjoyNot publishedCommunity banks and credit unions in the US that want a modern digital banking platform with online account opening and loan applications.
About nCino and its alternatives
nCino is a cloud platform for financial services, known for its loan origination and client onboarding workflows. It is used by banks to manage the lending lifecycle and customer relationships.
When comparing alternatives, weigh pricing structure, since most vendors do not publish prices and require sales conversations. Also consider regional focus, integration depth, support models, and whether you need a dedicated lending tool or a broader banking platform.
Explore the alternatives
- Custom quote
1.Salesforce
Best for: Teams that want a flexible CRM platform with AI agents and deep integrations across many business functions.
- Pricing
- Custom quote
- Category
- Customer Support
Salesforce is a general-purpose CRM platform with AI agents, data tools, and industry-specific clouds. Choose it over nCino if you need a broader system that covers sales, service, marketing, and commerce, not just banking workflows.
Where it is strong
- Strong AI agent capabilities (Agentforce) for automating customer interactions.
- Large ecosystem of apps and integrations via AgentExchange and MuleSoft.
- Industry-specific clouds, including financial services.
Where it falls short
- Pricing is opaque and requires sales engagement.
- Not purpose-built for banking origination or loan lifecycle management like nCino.
- Pricing:
- Pricing is not published on the site. Contact sales for quotes.
- Switching from nCino:
- Moving from nCino to Salesforce means rebuilding banking-specific workflows and integrations, as Salesforce lacks nCino's prebuilt loan origination and portfolio management tools.
- Not published
2.Temenos
Best for: Banks and credit unions that need a complete core banking system with digital and payments capabilities, rather than a point solution for commercial lending.
- Pricing
- Not published
- Category
- Finance & Accounting
Temenos is a full banking platform that covers core banking, digital channels, payments, wealth, and financial crime. Choose it over nCino when you need to replace or modernize the entire banking stack, not just the loan origination and client onboarding pieces.
Where it is strong
- Trusted by over 950 banks globally
- Covers core, digital, payments, wealth, and compliance in one platform
- Cloud-native and AI-driven, with SaaS deployment options
Where it falls short
- Pricing is not transparent. Likely enterprise-level contracts
- Heavier and more complex than nCino if you only need lending workflow
- Pricing:
- Pricing is not published on the site.
- Switching from nCino:
- Moving from nCino to Temenos means replacing your core banking system, which is a major multi-year project involving data migration, process redesign, and staff training.
- FNot published
3.Fiserv Digital Banking
Best for: Financial institutions and enterprises that need banking technology plus global payments and merchant acquiring in one vendor.
- Pricing
- Not published
- Category
- Other
Fiserv Digital Banking is a broad fintech and payments platform covering banking, merchant acquiring, billing, and point-of-sale. Choose it over nCino if you need a full banking and commerce stack rather than a loan origination and digital banking platform focused on financial services workflows. It suits institutions that want payments and merchant services alongside core banking operations.
Where it is strong
- Global payments reach into 190+ countries with local methods
- Covers banking, merchant acquiring, and point-of-sale in one platform
- Backs 70% of leading brands and reaches 100% of U.S. households
Where it falls short
- No published pricing, so budgeting requires a sales call
- Broader scope than nCino, so loan origination depth may be thinner
- Pricing:
- Pricing is not published on the site.
- Not published
4.Jack Henry
Best for: Community banks and credit unions that want a cloud-native platform to unify core banking, digital services, and payments while transitioning gradually.
- Pricing
- Not published
- Category
- Finance & Accounting
Jack Henry provides a broad technology ecosystem for community banks, credit unions, and fintechs, covering core processing, digital banking, payments, and lending. Choose it over nCino if you need a full-stack platform that goes beyond loan origination to include core banking and payments, especially for a gradual transition from legacy systems.
Where it is strong
- Cloud-native platform built with Google Cloud, offering high uptime and scalability.
- Covers core, digital banking, payments, and lending in one ecosystem.
- Designed for gradual transition, so you can keep your existing core while moving over time.
Where it falls short
- Pricing is not public, likely requiring a custom quote.
- Primarily targets community and regional institutions, not large global banks.
- Pricing:
- Pricing is not published on the site.
- Switching from nCino:
- Moving from nCino to Jack Henry involves adopting a broader platform, but its gradual transition design lets you keep your current core while integrating Jack Henry services over time.
- Not published
5.Q2
Best for: Banks and credit unions that want a single platform for digital banking, fraud detection, and commercial onboarding rather than a dedicated loan origination system.
- Pricing
- Not published
- Category
- Finance & Accounting
Q2 is a digital banking platform for banks and credit unions, covering consumer, small business, and commercial banking with built-in fraud protection. Choose it over nCino if your priority is the full digital banking experience for account holders, not just the back-office loan origination workflow that nCino focuses on.
Where it is strong
- Covers consumer, SMB, and commercial banking in one platform.
- Includes fraud detection and AI monitoring across channels.
- Claims 25% higher deposit and loan growth for clients.
Where it falls short
- No public pricing, so budgeting requires a sales conversation.
- Built for financial institutions, so it may be overkill for non-bank lenders.
- Pricing:
- Pricing is not published on the site.
- Not published
6.Mambu
Best for: Fintechs and banks that want to assemble a custom cloud banking stack with flexible product configuration.
- Pricing
- Not published
- Category
- Finance & Accounting
Mambu is a composable cloud banking platform that lets lenders and banks assemble their own stack from modular components. You would choose it over nCino if you need to build a custom lending or deposit product from scratch rather than adopt a pre-built end-to-end banking suite.
Where it is strong
- Composable architecture lets you pick and integrate only the modules you need
- Designed for launching new lending and deposit products quickly
- Strong API-first approach suits developer-led teams
Where it falls short
- Requires more integration and build effort than a turnkey suite like nCino
- Less out-of-the-box coverage for traditional commercial lending workflows
- Pricing:
- Pricing is not published on the site.
- BNot published
7.Backbase
Best for: Banks and financial institutions that want to unify frontline banking operations across multiple segments.
- Pricing
- Not published
- Category
- Other
Backbase is an AI-native banking operating system for the whole frontline. It covers small business, commercial, private banking, and wealth management. Choose it over nCino if you need a broader banking OS rather than a focused loan origination platform.
Where it is strong
- Covers multiple banking segments in one platform
- AI-native design for frontline workflows
- Includes implementation and managed hosting services
Where it falls short
- Pricing is not public
- No loan origination specifics mentioned on the homepage
- Pricing:
- Pricing is not published on the site.
- FSee website
8.Finastra
Finance & Accounting
A lending and credit management solution that competes in loan origination and portfolio management.
- SNot published
9.SAP
Best for: Large enterprises that need an integrated ERP with AI-driven automation across finance, supply chain, and HR, not just banking workflows.
- Pricing
- Not published
- Category
- Productivity & Project Management
SAP is a full enterprise resource planning suite covering finance, supply chain, HR, and customer experience, with AI agents embedded across those functions. You would choose it over nCino if you need a broad operational backbone for a large company rather than a dedicated banking platform. It suits organizations already standardized on SAP or those replacing multiple legacy systems at once.
Where it is strong
- Covers finance, supply chain, HR, and customer experience in one suite
- AI agents and workflows are built into core processes
- Large partner ecosystem for implementation and extensions
Where it falls short
- No banking-specific loan origination or commercial lending features
- Implementation is typically a major multi-year project
- Pricing:
- Pricing is not published on the site.
- ONot published
10.Oracle Cloud HPC
Best for: Engineering and research teams that need high-performance compute clusters on Oracle Cloud infrastructure.
- Pricing
- Not published
- Category
- Developer Tools
Oracle Cloud HPC provides high-performance computing infrastructure for compute-intensive workloads like simulations, modeling, and data processing. Choose it instead of nCino when you need raw cloud compute power for engineering or scientific tasks, not a financial services platform. It suits teams that already run on Oracle or need bare-metal performance for specialized workloads.
Where it is strong
- Bare-metal and cluster options for heavy compute
- Tight integration with the broader Oracle ecosystem
- Global data center footprint for low-latency workloads
Where it falls short
- No financial services features like loan origination or CRM
- Oracle's sales-led model means no self-serve pricing or trial
- Pricing:
- Pricing is not published on the site.
- Not published
11.FIS Digital Banking
Best for: Banks and financial institutions that want core banking, payments, and treasury in one vendor.
- Pricing
- Not published
- Category
- Finance & Accounting
FIS Digital Banking is a large fintech platform covering core banking, payments, treasury, and investment operations. Choose it over nCino if you need a broader money lifecycle platform rather than a focused loan origination and CRM system.
Where it is strong
- Covers the full money lifecycle from deposits to payments to investments
- Strong security and compliance reputation
- Includes analytics and modernization tools for banks
Where it falls short
- Pricing is not transparent and requires a quote
- Platform is broad but not specialized for loan origination like nCino
- Pricing:
- Pricing is not published on the site. The linked pricing page is for Worldpay card processing and shows indicative quotes based on annual turnover and average transaction value.
- Not published
12.Bankjoy
Best for: Community banks and credit unions in the US that want a modern digital banking platform with online account opening and loan applications.
- Pricing
- Not published
- Category
- Finance & Accounting
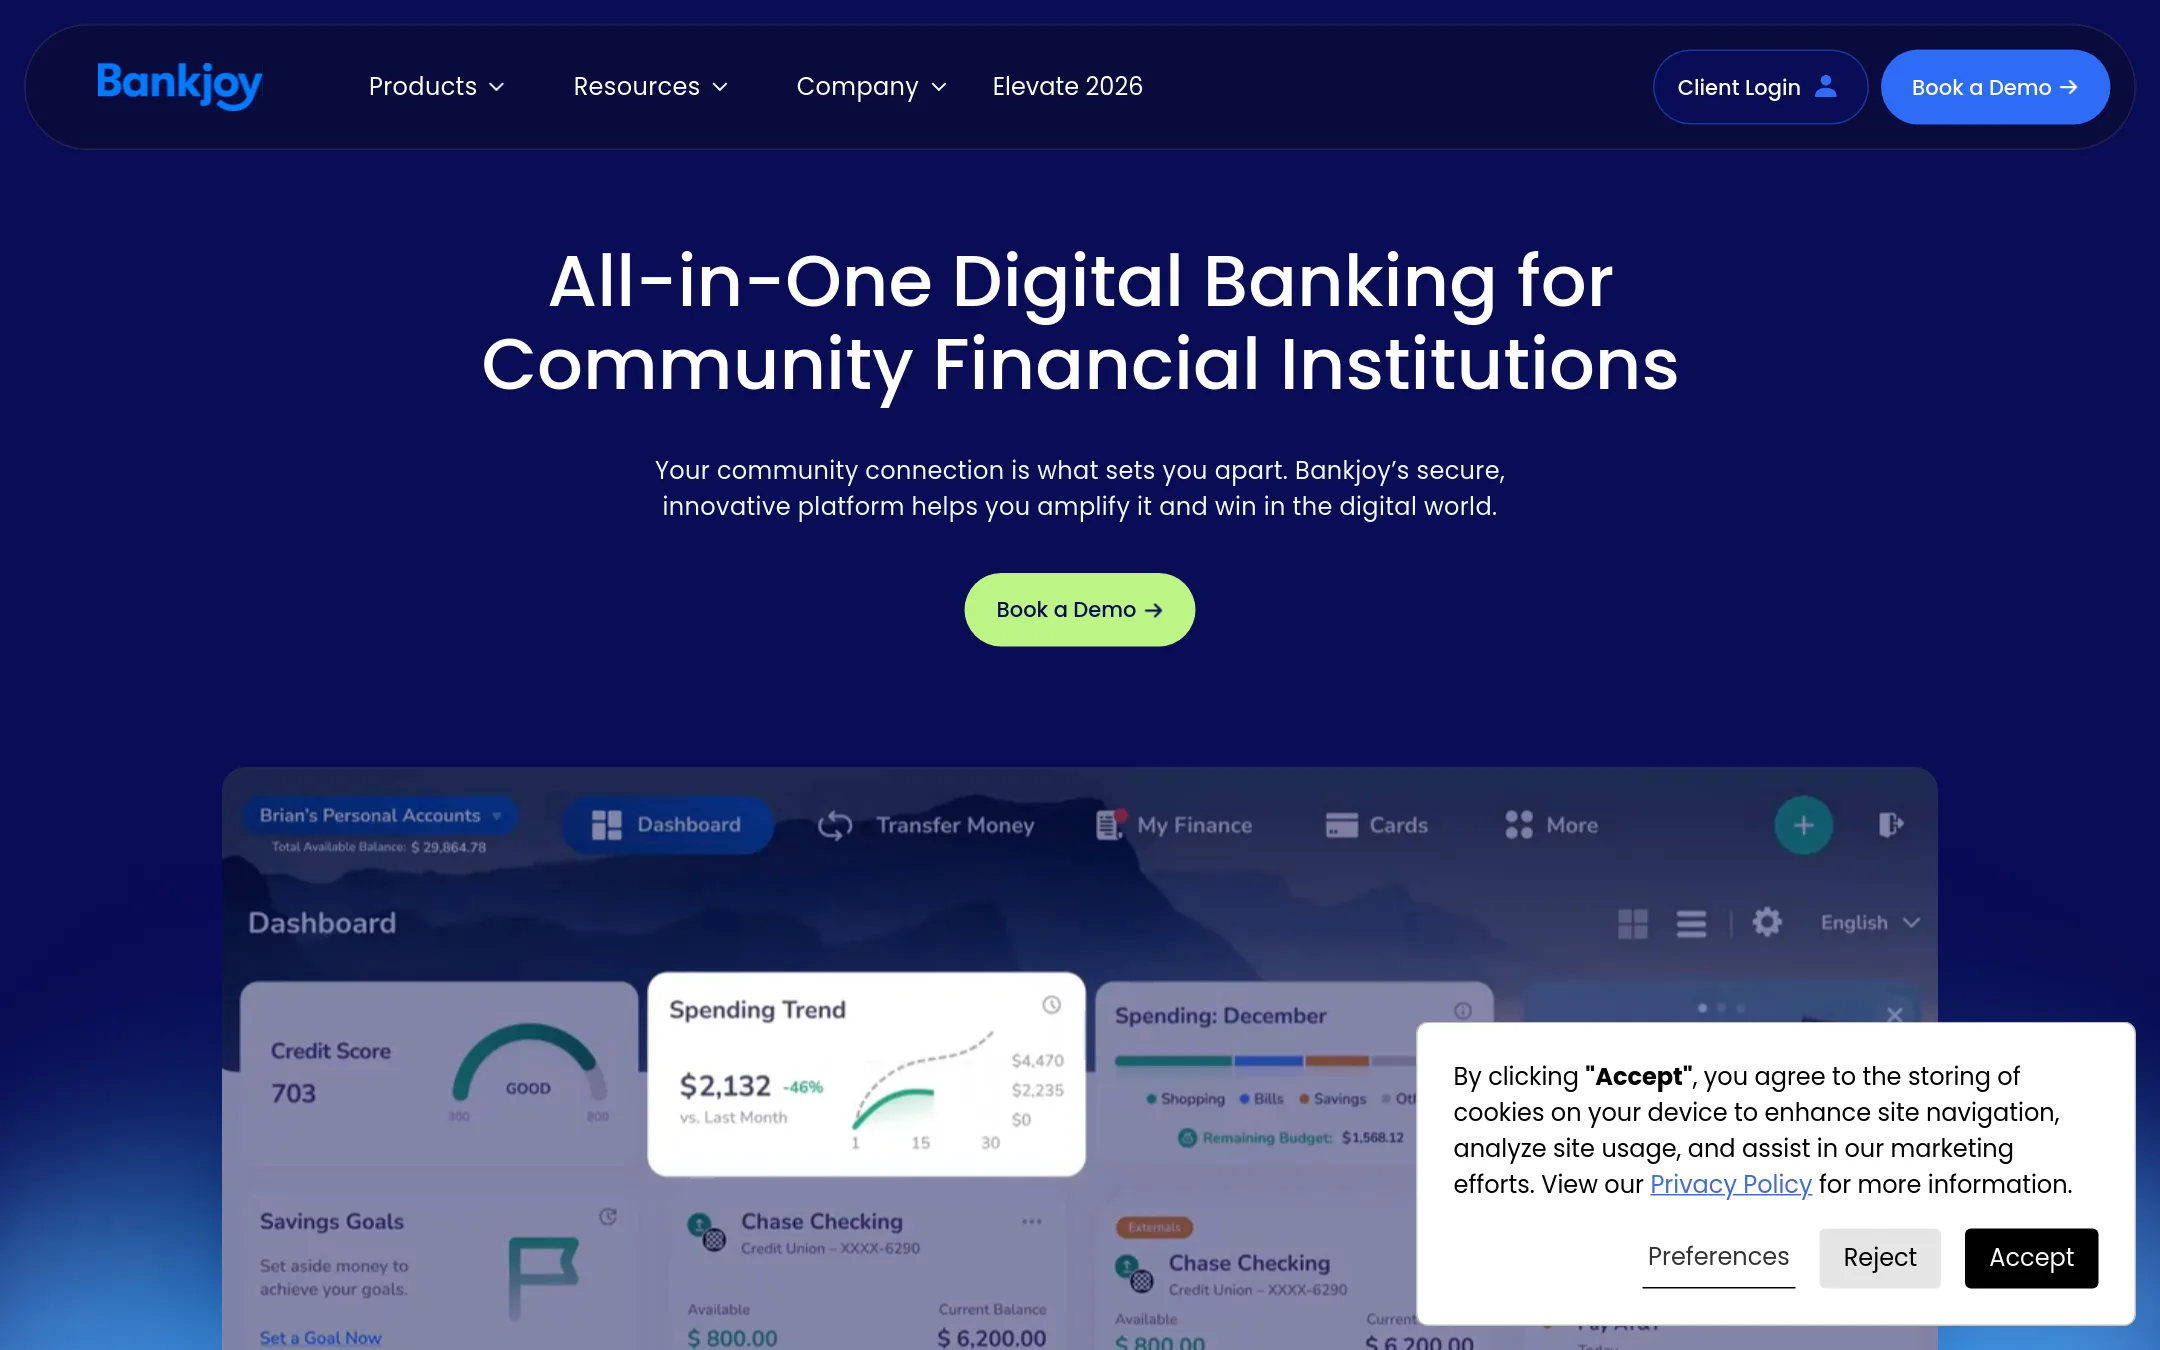
Bankjoy is a digital banking platform for community banks and credit unions, covering consumer and business banking, account opening, loan applications, and fraud prevention. Choose it over nCino if you are a smaller institution that needs an end-to-end member-facing digital experience rather than nCino's broader enterprise banking suite.
Where it is strong
- Built specifically for community banks and credit unions
- Includes online account opening and loan applications
- Offers fraud prevention tools like FraudSense
Where it falls short
- Pricing not disclosed publicly
- May lack nCino's broader commercial lending and portfolio management features
- Pricing:
- Pricing is not published on the site.
See more comparisons in Finance & Accounting alternatives.
FAQ
Questions about nCino alternatives
What is the main difference between nCino and these alternatives?
nCino focuses on loan origination and client onboarding for financial institutions. Many alternatives, like Bankjoy and Q2, cover the full digital banking experience for account holders, while others like Jack Henry and Temenos provide a complete banking stack including core processing.
Are these alternatives cheaper than nCino?
Most alternatives do not publish pricing, so you cannot compare costs upfront. You will need to contact sales for quotes, and pricing likely depends on your institution's size and the modules you need.
Which alternative is best for a small community bank?
Bankjoy is built specifically for community banks and credit unions, offering digital banking, account opening, and loan applications. Jack Henry also targets community institutions and allows a gradual transition from legacy systems.
Can I use these alternatives for commercial lending?
Some alternatives, like Q2 and Backbase, cover commercial banking but may not have the same depth in loan origination as nCino. Temenos and Jack Henry offer broader lending capabilities as part of their full banking platforms.
Do these alternatives integrate with existing core systems?
Jack Henry is designed for gradual transition, so you can keep your existing core while moving over time. Mambu offers a composable architecture with APIs for custom integrations, while others like Salesforce rely on a large ecosystem of apps and connectors.
Last updated November 1, 2026.