Synapse alternatives
12 products compared · Updated November 1, 2026
The short answer
For founders comparing Synapse alternatives, the strongest options are Stripe for broad payments and subscriptions, Treasury Prime for multi-bank embedded banking, and Unit for a full-stack US banking platform with managed compliance. Stripe suits internet businesses of any size, Treasury Prime fits fintechs needing bank flexibility, and Unit is best for US fintech teams wanting deposits, cards, and lending on one platform.
Your shortlist, at a glance
Read the comparisons ↓ PlaidNot publishedFintech apps and platforms in the U.S. that need bank account linking, transaction data, or payment initiation.
 Stripe2.9% + 30¢Internet businesses of any size that want to accept payments, manage subscriptions, and embed financial services without building their own infrastructure.
- DDwollaCustom quotePlatforms and enterprises in the US that embed high-volume ACH or real-time bank payments into their product and need predictable status reporting.
 MarqetaNot publishedFintechs and enterprises that need to issue cards at scale and want a partner to handle bank relationships, compliance, and operations.
- UUnitNot publishedFintech teams in the US that need deposit accounts, ACH, card issuing, and lending on one platform with managed compliance.
 Treasury PrimeNot publishedFintechs and banks that want multi-bank redundancy and a marketplace to match with sponsor banks, rather than a single-bank integration.
 ColumnSee websiteThe platform bank built for scale
DecentroNot publishedIndian fintechs and businesses that need banking APIs for payments, verification, and other financial services.
 IncreaseNot publishedUS-focused fintechs and platforms that need direct bank partnerships and full control over payment rails and compliance.
 ModernbancSee websiteAccounting software that works for you
 Rocket.ChatCustom quoteGovernment and defense teams that require sovereign, air-gapped, or SCIF-ready communications with Matrix and XMPP federation.
UlauncherSee websiteApplication launcher for Linux with fuzzy search and extensions
About Synapse and its alternatives
Synapse is a platform for financial infrastructure, providing APIs to build banking, payments, and card issuing into your products. It is known for its banking-as-a-service capabilities, connecting fintechs to partner banks and payment rails.
When comparing alternatives, weigh pricing structure (many are custom, not public), geographic focus (US-only vs. global), integration complexity, and the level of program management and compliance support included. Also consider contract terms, as some platforms require long-term commitments or enterprise sales.
Explore the alternatives
- Not published
1.Plaid
Best for: Fintech apps and platforms in the U.S. that need bank account linking, transaction data, or payment initiation.
- Pricing
- Not published
- Category
- Finance & Accounting
Plaid connects apps to users' bank accounts for payments, identity verification, and financial data access. Choose it instead of Synapse when you need to link external bank accounts or pull transaction data, not build your own banking infrastructure.
Where it is strong
- Access to 12,000 financial institutions across 20 countries
- Free sandbox testing and 200 live API calls per product
- Products for auth, balance, identity, transactions, and payments
Where it falls short
- Pricing requires contacting sales for most products
- Limited to data connectivity, not a full banking-as-a-service platform
- Pricing:
- Pricing is not published on the site. Plans are Pay as You Go, Growth, and Custom, with product-specific fees.
- 2.9% + 30¢
2.Stripe
Best for: Internet businesses of any size that want to accept payments, manage subscriptions, and embed financial services without building their own infrastructure.
- Pricing
- 2.9% + 30¢
- Category
- Finance & Accounting
Stripe is a broad payments and financial infrastructure platform, covering online and in-person payments, billing, card issuing, and money movement. Choose it over Synapse if you need a widely adopted, self-serve payments stack with global reach and extensive documentation.
Where it is strong
- Supports 135+ currencies and payment methods globally.
- Processed $1.9T in payments volume in 2025 with high uptime.
- Offers pre-built UIs, no-code tools, and extensive APIs for fast integration.
Where it falls short
- Pricing for many features is custom and not publicly listed.
- Not a full banking platform. Lacks some program management capabilities Synapse offers.
- Pricing:
- Stripe charges 2.9% + 30¢ per successful transaction for domestic cards, with custom pricing for volume and additional features.
- Switching from Synapse:
- Moving from Synapse to Stripe involves re-implementing payment flows and migrating any stored customer and transaction data, but Stripe provides migration guides and consulting support.
- DCustom quote
3.Dwolla
Best for: Platforms and enterprises in the US that embed high-volume ACH or real-time bank payments into their product and need predictable status reporting.
- Pricing
- Custom quote
- Category
- Other
Dwolla is a bank payment infrastructure API for ACH, Same Day ACH, and real-time rails (RTP and FedNow). Choose it over Synapse when you need a single integration for high-volume bank transfers with standardized status tracking and exception handling, especially in regulated industries like real estate, lending, or insurance.
Where it is strong
- Single API for ACH, Same Day ACH, and real-time payments (RTP, FedNow).
- Tokenization protects sensitive bank account data.
- Guided implementation and responsive customer support mentioned by customers.
Where it falls short
- Pricing is custom only, no self-serve tiers.
- Focus is on bank transfers. No card issuing or credit products like Synapse offers.
- Pricing:
- Pricing is not published on the site. It is custom-tailored to transaction volume, rails, and integration needs.
- Switching from Synapse:
- Moving from Synapse means re-building your payment integration around Dwolla's API, but the standardized status and exception handling can simplify reconciliation.
- Not published
4.Marqeta
Best for: Fintechs and enterprises that need to issue cards at scale and want a partner to handle bank relationships, compliance, and operations.
- Pricing
- Not published
- Category
- Finance & Accounting
Marqeta is a card issuing and payment processing platform for companies that need to launch and scale debit, credit, or prepaid card programs. Choose it over Synapse when you need enterprise-grade infrastructure with high transaction volume, global reach, and hands-on program management support.
Where it is strong
- 99.99% platform uptime in 2025
- Certified to operate in 40+ countries
- Supports debit, prepaid, and credit credentials on one platform
Where it falls short
- Pricing is not public, likely custom for enterprise deals
- May be more complex than needed for simple card programs
- Pricing:
- Pricing is not published on the site.
- Switching from Synapse:
- Moving from Synapse to Marqeta would involve reconfiguring your card programs and integrating with their APIs, but the platform is designed to support growth and international expansion.
- UNot published
5.Unit
Best for: Fintech teams in the US that need deposit accounts, ACH, card issuing, and lending on one platform with managed compliance.
- Pricing
- Not published
- Category
- Other
Unit is a full-stack financial infrastructure platform that lets you build banking, payments, card issuing, and lending into your product. You would choose it over Synapse if you want a single native ledger with direct access to the Federal Reserve, card networks, and bank partners, plus program management for compliance and fraud.
Where it is strong
- Direct access to Federal Reserve, card networks, and bank partners
- Includes program management for compliance, fraud, disputes, and support
- Offers managed solutions like banking and bill pay in one line of code
Where it falls short
- Pricing is not public, so you must contact sales for a quote
- Primarily US-focused, with bank partners and FDIC coverage limited to the US
- Pricing:
- Pricing is not published on the site.
- Not published
6.Treasury Prime
Best for: Fintechs and banks that want multi-bank redundancy and a marketplace to match with sponsor banks, rather than a single-bank integration.
- Pricing
- Not published
- Category
- Finance & Accounting
Treasury Prime is an embedded banking platform that connects fintechs to a network of 20+ banks through a single API. Choose it over Synapse if you want to avoid being locked to one sponsor bank and need the ability to move programs across banks as risk appetites change.
Where it is strong
- Access to 20+ banks through one API and one marketplace submission
- Public sandbox and REST APIs for quick evaluation and development
- Built-in program vetting and audit trails for bank compliance
Where it falls short
- Pricing not disclosed, likely custom and enterprise-oriented
- Network approach may be overkill for simple single-bank use cases
- Pricing:
- Pricing is not published on the site.
- See website
7.Column
Finance & Accounting
The platform bank built for scale
- Not published
8.Decentro
Best for: Indian fintechs and businesses that need banking APIs for payments, verification, and other financial services.
- Pricing
- Not published
- Category
- Finance & Accounting
Decentro is an API platform for banking integrations focused on India and APAC. If you need to connect to Indian banks for payments, verification, or other financial services, Decentro offers plug-and-play APIs and SDKs. Choose it over Synapse when your core market is India and you want a local partner.
Where it is strong
- Plug-and-play APIs and SDKs for faster integration
- Trusted by 2000+ Indian businesses
- Focused on India and APAC banking integrations
Where it falls short
- Pricing not publicly listed
- Limited to India and APAC region, not global
- Pricing:
- Pricing is not published on the site.
- Not published
9.Increase
Best for: US-focused fintechs and platforms that need direct bank partnerships and full control over payment rails and compliance.
- Pricing
- Not published
- Category
- Finance & Accounting
Increase is an API-first bank that provides direct access to US payment rails, card issuing, and bank accounts. Choose it over Synapse if you need a direct bank partnership with transparent, programmatic compliance and bare-metal payments infrastructure.
Where it is strong
- Direct access to all major US payment rails without third-party vendors.
- Composable primitives for accounts, cards, and compliance workflows.
- Transparent APIs with full network data on every transaction.
Where it falls short
- Pricing is not public. Requires contacting sales.
- Only US banking rails and partner banks. No international coverage mentioned.
- Pricing:
- Pricing is not published on the site.
- See website
10.Modernbanc
Finance & Accounting
Accounting software that works for you
- Custom quote
11.Rocket.Chat
Best for: Government and defense teams that require sovereign, air-gapped, or SCIF-ready communications with Matrix and XMPP federation.
- Pricing
- Custom quote
- Category
- Communication & Collaboration
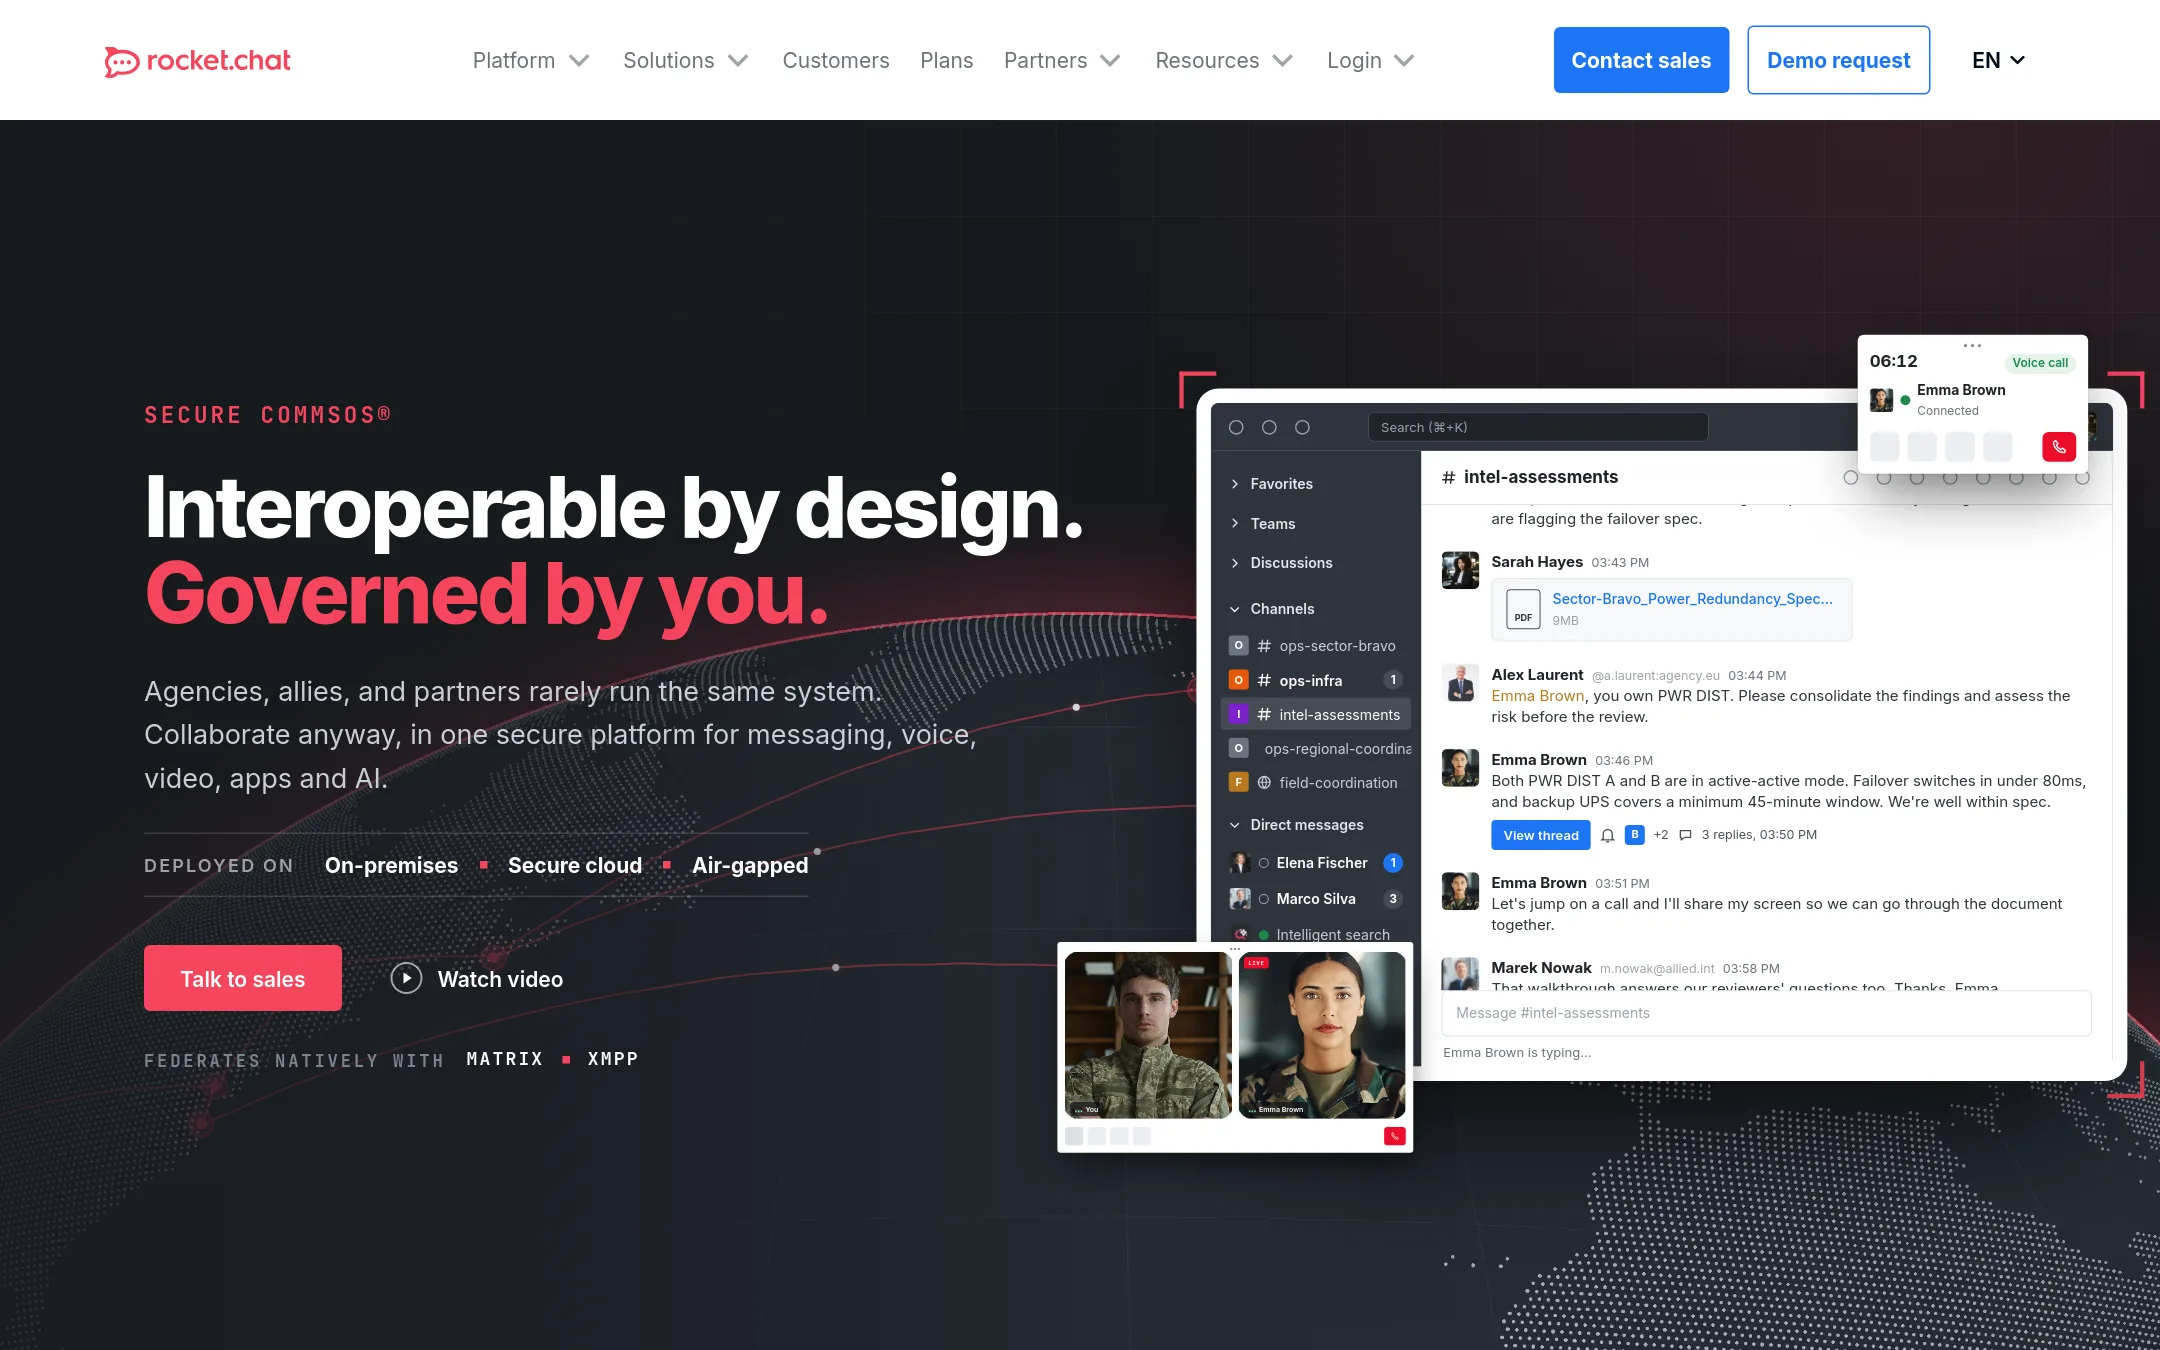
Rocket.Chat is a secure communication platform for messaging, voice, and video, built for organizations that need full control over their data. Choose it instead of Synapse if you are in defense, government, or critical infrastructure and need self-hosted or air-gapped deployment with federation.
Where it is strong
- Self-hosted, air-gapped, or sovereign cloud deployment options
- Native Matrix and XMPP federation for inter-agency collaboration
- Post-quantum encryption and Zero Trust security up to IL6
Where it falls short
- Pricing is not transparent. Requires contacting sales
- Focused on secure communications, not financial infrastructure like Synapse
- Pricing:
- Pricing is not published on the site. Plans are listed as Commercial, Government, and Defense with custom quotes.
- See website
12.Ulauncher
Productivity & Project Management
Application launcher for Linux with fuzzy search and extensions
See more comparisons in Finance & Accounting alternatives.
FAQ
Questions about Synapse alternatives
What is the best alternative to Synapse for a startup that needs to accept payments quickly?
Stripe is the strongest choice for startups needing to accept payments fast. It offers a self-serve setup, extensive documentation, and supports 135+ currencies. Pricing is transparent at 2.9% + 30¢ per transaction.
Which alternative is best for a fintech that wants to avoid being locked into a single sponsor bank?
Treasury Prime is designed for multi-bank redundancy, giving you access to 20+ banks through one API. This lets you move programs across banks as risk appetites change. It is ideal for fintechs that need flexibility in bank partnerships.
Are there alternatives with transparent, published pricing?
Most alternatives, including Brex, Cashfree, Treasury Prime, Increase, Decentro, Rocket.Chat, Plaid, Marqeta, Dwolla, and Unit, do not publish pricing and require contacting sales. Stripe is the only one with a clear per-transaction rate listed.
Which alternative is best for a company focused on the Indian market?
Cashfree Payments is the top choice for Indian businesses, supporting 180+ payment methods including UPI and offering instant settlements. Decentro is also India-focused but has no published pricing. Both require contacting sales for details.
What should I consider when choosing between these alternatives?
Consider your geographic focus, whether you need card issuing or just payments, and the level of compliance support you require. Also check if the platform offers program management, as some like Unit and Marqeta include it. Finally, evaluate contract terms, as many require enterprise sales and custom pricing.
Last updated November 1, 2026.