
Tala alternatives
12 products compared · Updated November 2, 2026
The short answer
The strongest Tala alternatives are Branch, CredoLab, and Upstart. Branch suits teams building consumer finance apps in Nigeria or India, CredoLab suits lenders in emerging markets adding behavioral scoring, and Upstart suits US borrowers or lenders seeking AI underwriting.
Your shortlist, at a glance
Read the comparisons ↓ BranchNot publishedTeams building consumer-facing mobile finance apps in Nigeria or India that need loans plus payments and savings in one product.
- JJumoNot publishedTeams that already have a relationship with Jumo and don't need to evaluate it from public information.
- LLenddoSee websiteOther
- CCredoLabFrom $4,485/yrLenders in emerging markets who want to add behavioral scoring to their current risk models and increase approval rates without overhauling their stack.
- FFidoNot publishedIndividuals in Ghana, Uganda, or South Africa who need quick personal loans from their phone.
 ApurataNot publishedPeruvian merchants and consumers who want fast, small personal loans or in-store financing through the Acuotaz product.
 AvantNot publishedU.S. consumers with fair credit who want an online personal loan or credit card application.
- OOpaySee websiteSecure, fast banking with free transfers, daily interest, and zero-fee debit cards.
 OppLoansNot publishedU.S. consumers with thin credit files who need a $500–$5,000 personal loan and want to build credit history.
- PPaystackSee websiteModern payments infrastructure for Africa.
 PiggyVestSee websiteThe Better Way To Save & Invest Online
 Possible FinanceNot publishedUS-based individuals who need quick cash advances or small loans and want to build credit without late fees
About Tala and its alternatives
Tala is an AI-native credit infrastructure company for thin-file borrowers in emerging markets. It uses data from over $10B in lending performance across 15 million customers to offer credit, savings, and other financial services through a mobile app.
When comparing alternatives, weigh pricing structure (published vs. contact sales), geographic coverage (US-only vs. emerging markets), integration options (APIs vs. consumer apps), and contract terms like origination fees or prepayment penalties. Some products are full platforms, others are point solutions, so match the tool to your specific need.
Explore the alternatives
- Not published
1.Branch
Best for: Teams building consumer-facing mobile finance apps in Nigeria or India that need loans plus payments and savings in one product.
- Pricing
- Not published
- Category
- Finance & Accounting
Branch is a consumer finance app offering loans, transfers, bill pay, and savings in Africa and India. Choose it instead of Tala if you want a full mobile wallet with a debit card, not just credit infrastructure.
Where it is strong
- Over 100 million downloads across Africa and India
- Includes a debit card in Nigeria with no ATM withdrawal charges
- Offers savings and investment products with high yields
Where it falls short
- Debit card only available in Nigeria so far
- No API or developer tools mentioned on the site
- Pricing:
- Pricing is not published on the site.
- JNot published
2.Jumo
Best for: Teams that already have a relationship with Jumo and don't need to evaluate it from public information.
- Pricing
- Not published
- Category
- Other
Jumo's website is currently unreachable, so there is no public information about what the product does or its pricing. You would only consider it if you already have direct knowledge of Jumo from elsewhere, since the site provides no usable details.
Where it is strong
- No public site means no marketing noise to wade through.
- You can focus on direct conversations with the vendor.
- No pricing pages to misinterpret.
Where it falls short
- The website is down, so you cannot verify features or roadmap.
- No public pricing or documentation to compare with Tala.
- Pricing:
- Pricing is not published on the site.
- LSee website
3.Lenddo
Other
Uses alternative data and AI to score and lend to thin-file borrowers globally.
- CFrom $4,485/yr
4.CredoLab
Best for: Lenders in emerging markets who want to add behavioral scoring to their current risk models and increase approval rates without overhauling their stack.
- Pricing
- From $4,485/yr
- Category
- Other
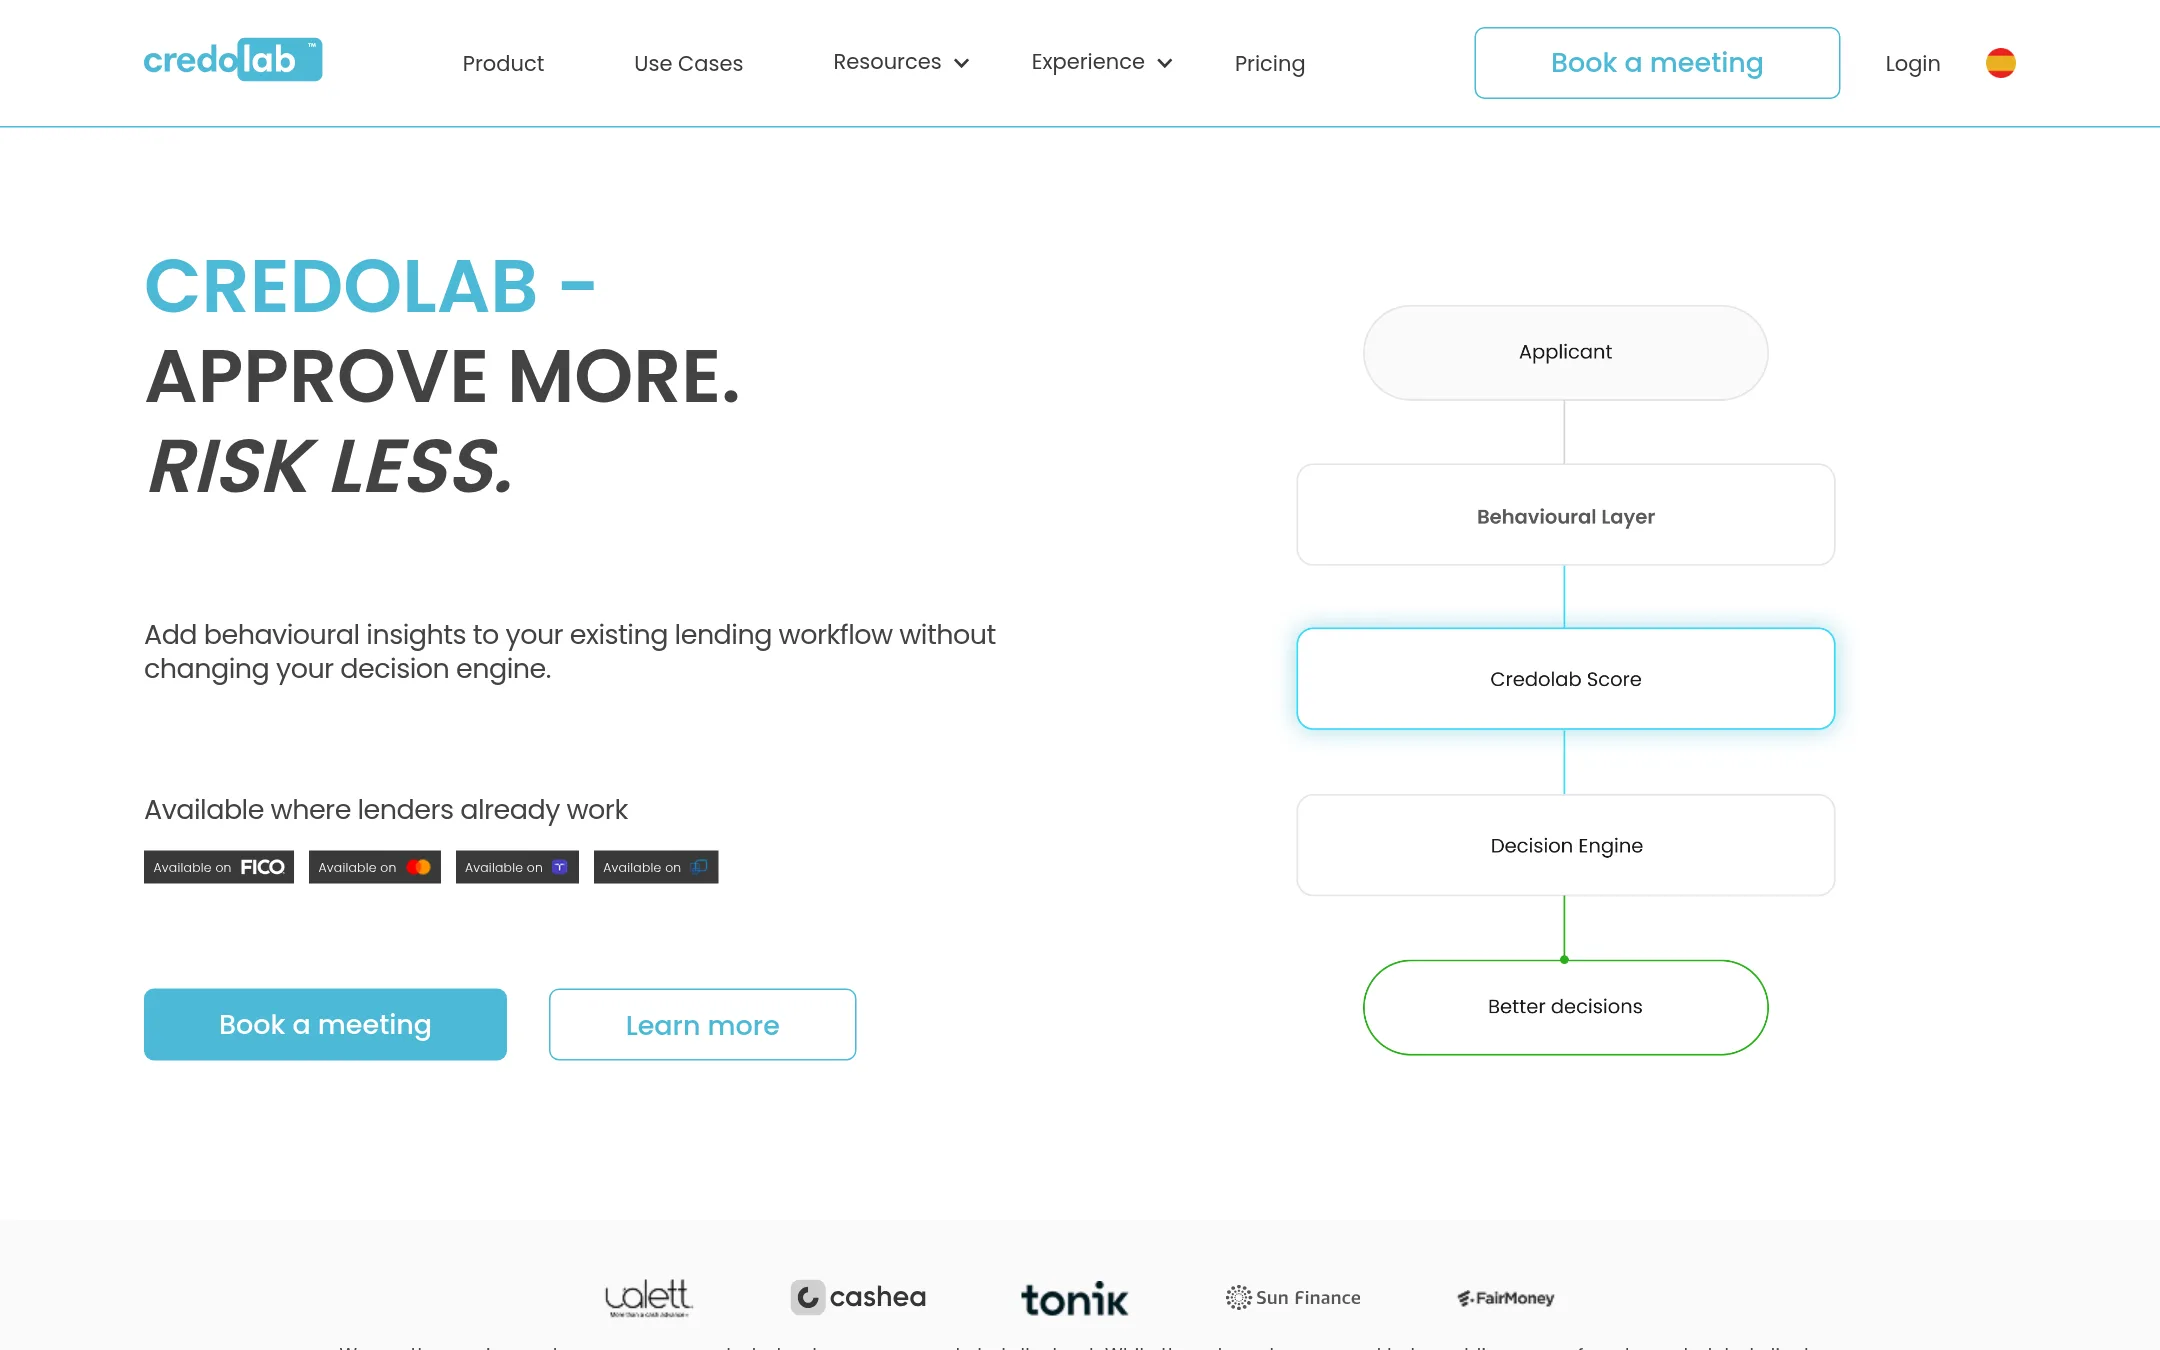
CredoLab provides behavioral credit scoring based on alternative data, helping lenders approve more thin-file and no-file applicants without changing their decision engine. Choose CredoLab over Tala if you need a modular scoring layer that integrates with your existing lending workflow, rather than a full credit infrastructure platform.
Where it is strong
- Boosts predictive power by up to 45% and approvals by up to 32%.
- Works across 50+ countries with locally calibrated models.
- ISO/IEC 27001 certified with privacy-compliant data collection.
Where it falls short
- Pricing for the full Credo Score plan requires contacting sales.
- No consumer-facing app. It's a B2B scoring service only.
- Pricing:
- Pricing is not published on the site. Plans start at $4,485/year for up to 100k uploads (Credo Lite) and $7,485/year for up to 100k uploads (Credo One), with Credo Score available on contact.
- Switching from Tala:
- Switching from Tala to CredoLab means integrating a scoring API into your existing lending system, not replacing your entire credit infrastructure.
- FNot published
5.Fido
Best for: Individuals in Ghana, Uganda, or South Africa who need quick personal loans from their phone.
- Pricing
- Not published
- Category
- Other
Fido is a consumer loan app for Ghana, Uganda, and South Africa that gives instant loans after identity verification and a Fido Score. Choose it over Tala if you want a straightforward loan app rather than credit infrastructure for building your own lending product.
Where it is strong
- Instant loans after selfie and Ghana card verification
- Fido Score unlocks better loan options
- Available in Ghana, Uganda, and South Africa
Where it falls short
- No published pricing or fee schedule
- Not a B2B credit infrastructure platform like Tala
- Pricing:
- Pricing is not published on the site.
- Not published
6.Apurata
Best for: Peruvian merchants and consumers who want fast, small personal loans or in-store financing through the Acuotaz product.
- Pricing
- Not published
- Category
- Finance & Accounting
Apurata is a Peruvian point-of-sale financing platform that gives consumers instant credit decisions and disburses loans in as little as 29 minutes. Choose it instead of Tala if you need a local, regulated lender focused on Peru's middle class, not a global AI credit infrastructure for emerging markets.
Where it is strong
- Loans from S/100 to S/5,000 with approval in minutes
- Disbursement to bank accounts in up to 29 minutes
- Payments accepted at BCP, BBVA, and Interbank agents
Where it falls short
- Only operates in Peru
- Maximum TCEA can reach 2849%, so costs can be very high
- Pricing:
- Pricing is not published on the site.
- Not published
7.Avant
Best for: U.S. consumers with fair credit who want an online personal loan or credit card application.
- Pricing
- Not published
- Category
- Finance & Accounting
Avant offers personal loans and credit cards to consumers in the U.S. who may not qualify for traditional bank products. Choose Avant instead of Tala if you need a straightforward consumer lending product rather than AI credit infrastructure for emerging markets.
Where it is strong
- Simple online application for personal loans and credit cards.
- Designed for borrowers with less-than-perfect credit.
- Fast decision process directly on the website.
Where it falls short
- No pricing details published, so costs are unclear upfront.
- Limited to consumer lending, not a full credit infrastructure platform.
- Pricing:
- Pricing is not published on the site.
- OSee website
8.Opay
Finance & Accounting
Secure, fast banking with free transfers, daily interest, and zero-fee debit cards.
- Not published
9.OppLoans
Best for: U.S. consumers with thin credit files who need a $500–$5,000 personal loan and want to build credit history.
- Pricing
- Not published
- Category
- Finance & Accounting
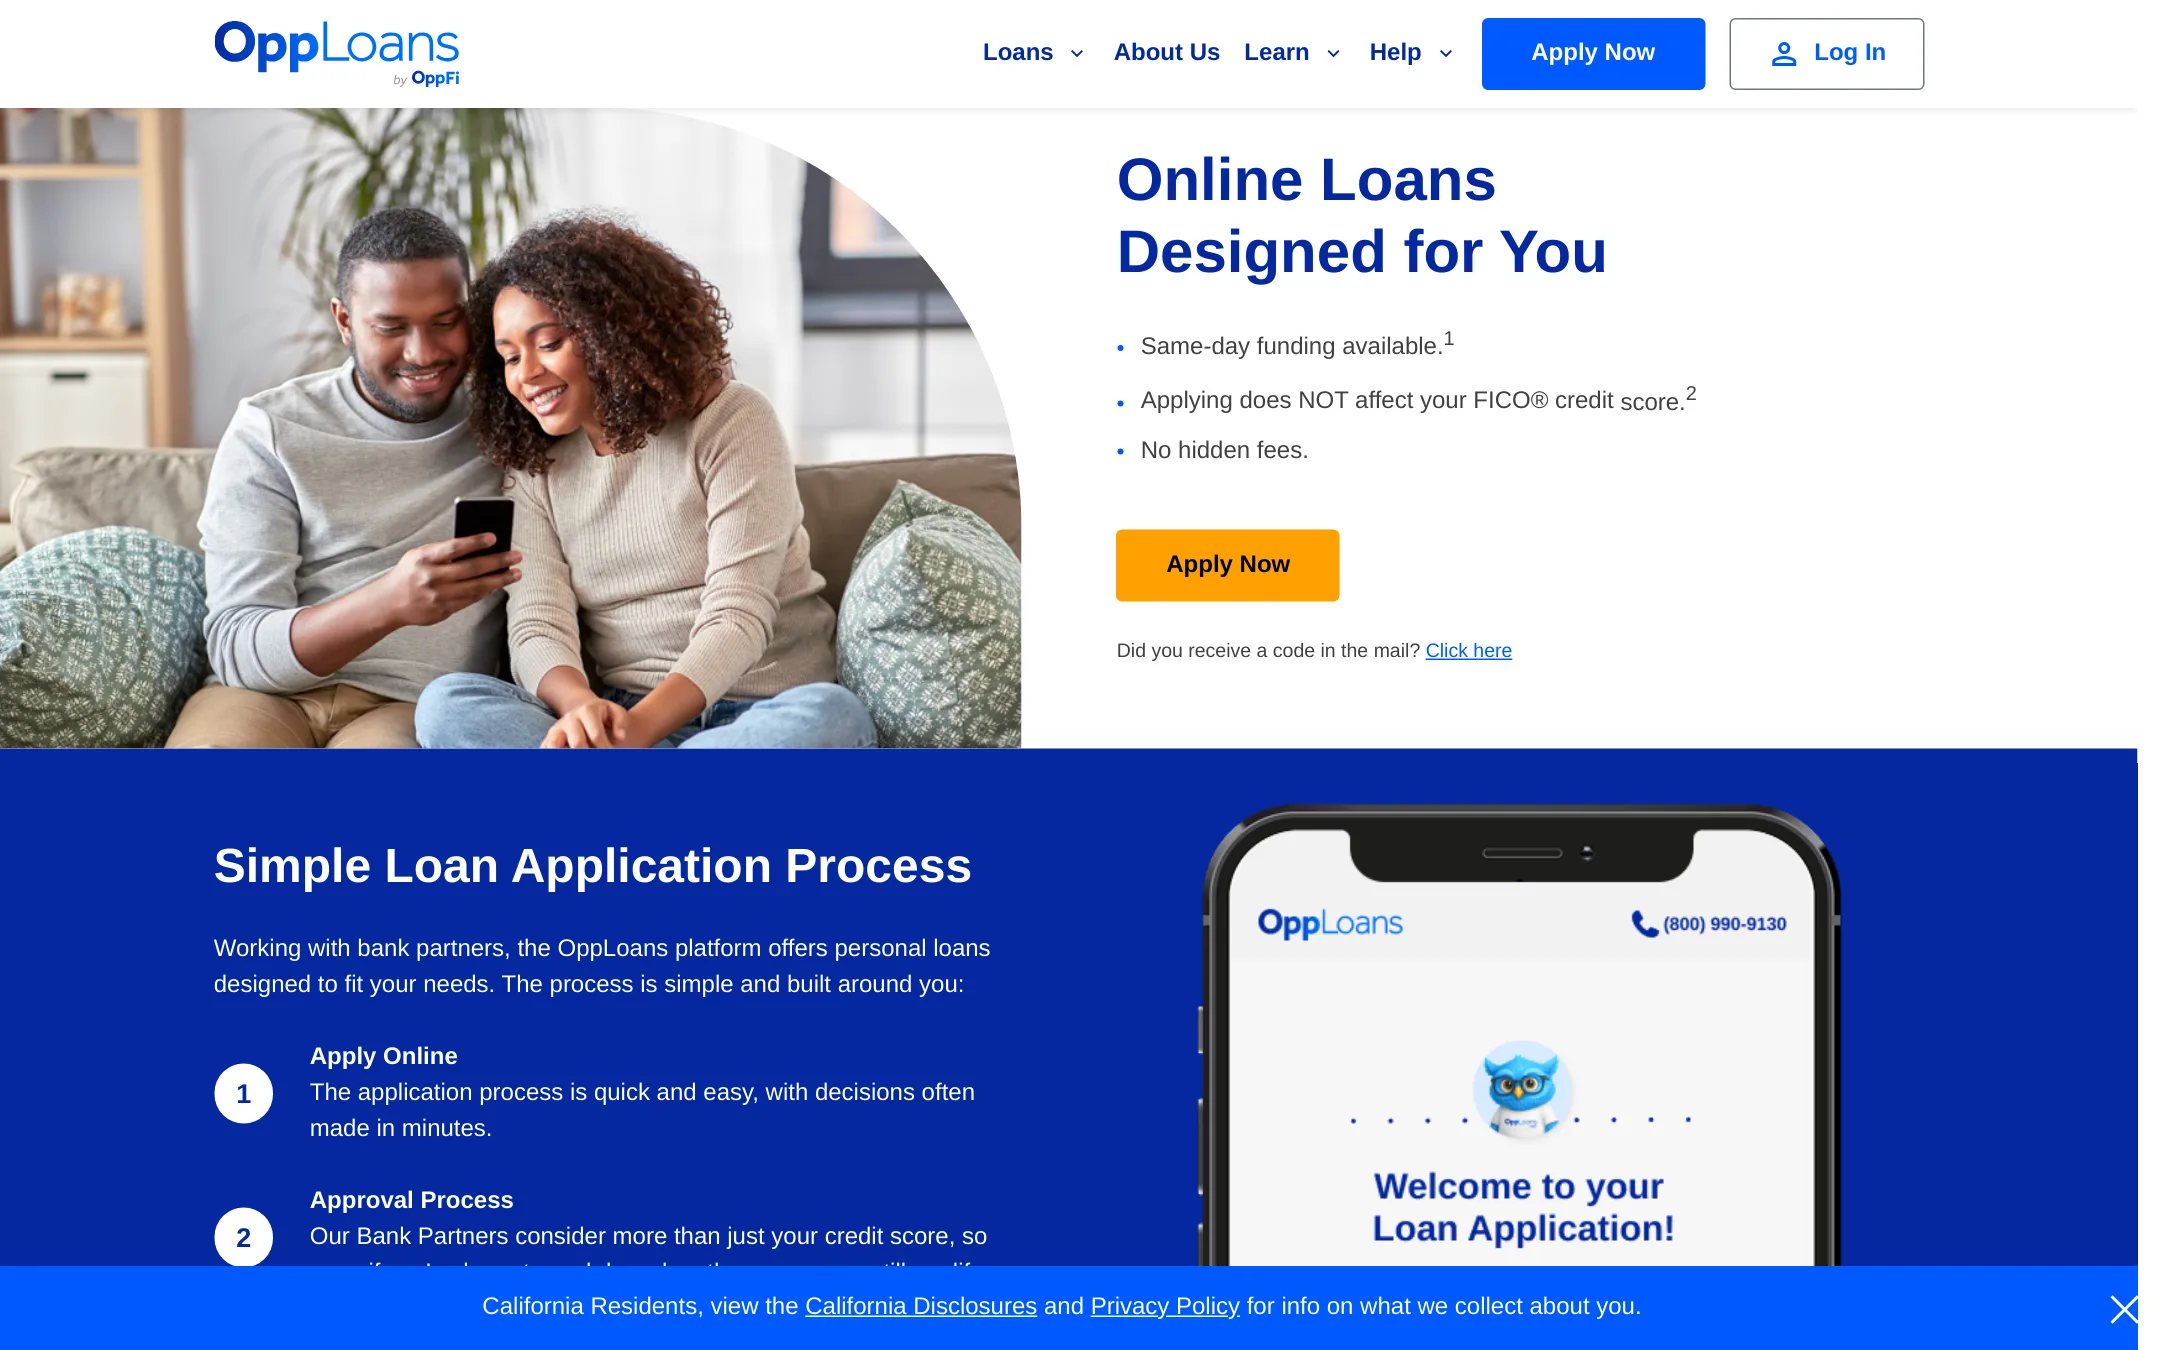
OppLoans is a direct-to-consumer personal loan platform for U.S. borrowers with limited credit history. Choose it instead of Tala if you need a straightforward personal loan with same-day funding and credit bureau reporting, rather than AI credit infrastructure for emerging markets.
Where it is strong
- Same-day funding if approved
- No origination or prepayment fees from bank partners
- Reports payments to all three major credit bureaus
Where it falls short
- Loan amounts limited to $500–$5,000
- Only available in certain U.S. states
- Pricing:
- Pricing is not published on the site.
- PSee website
10.Paystack
Finance & Accounting
Modern payments infrastructure for Africa.
- See website
11.PiggyVest
Finance & Accounting
The Better Way To Save & Invest Online
- Not published
12.Possible Finance
Best for: US-based individuals who need quick cash advances or small loans and want to build credit without late fees
- Pricing
- Not published
- Category
- Finance & Accounting
Possible Finance gives US customers instant cash advances and loans up to $500 with no late fees and credit-building options. Choose it instead of Tala if you need a straightforward consumer app for short-term cash in the US, not AI credit infrastructure for emerging markets.
Where it is strong
- No late fees or penalty fees
- Move payments up to 29 days out with no rescheduling fee
- Build credit history with loan repayments
Where it falls short
- Max loan amount is $500, which may be too small for larger needs
- First advances average $85, so initial access is limited
- Pricing:
- Pricing is not published on the site.
See more comparisons in Finance & Accounting alternatives.
FAQ
Questions about Tala alternatives
What is the best Tala alternative for emerging markets?
Branch is a strong choice for consumer finance in Africa and India, offering loans, transfers, bill pay, and savings. CredoLab is better for lenders who want to add behavioral scoring to their existing risk models across 50+ countries.
Which alternative is best for US borrowers?
Upstart is ideal for US borrowers with some credit history, offering fixed-rate personal loans with APRs from 6.3% to 35.99%. Rocket Loans also works for those with a FICO score of 640 or higher, with same-day funding.
Are there alternatives with published pricing?
Most alternatives do not publish pricing on their sites. CredoLab is an exception, with plans starting at $4,485/year for up to 100k uploads. Rocket Loans discloses APR ranges and origination fees.
Which alternative is best for building a lending product?
CredoLab provides a modular scoring layer that integrates with your existing decision engine, boosting approvals by up to 32%. Upstart offers an AI underwriting platform for US lenders, but it is not designed for emerging markets.
What are the main differences between Tala and these alternatives?
Tala is AI credit infrastructure for thin-file borrowers in emerging markets, while most alternatives are consumer loan apps or US-focused lenders. CredoLab is the closest B2B infrastructure option, but it only provides scoring, not a full platform.
Last updated November 2, 2026.