12 Best Banking Platforms in 2026
Updated October 16, 2026
The short answer
The best banking platforms are Increase for fintechs needing direct access to US payment rails, Column for developers wanting programmable banking infrastructure, and Temenos for established banks modernizing core systems. Increase suits fintechs building custom banking products, Column suits fintechs and financial institutions needing real-time payments and card issuing, and Temenos suits large banks needing end-to-end modernization.
The shortlist, at a glance
Read the comparisons ↓ IncreaseNot publishedFintechs and platforms that need direct access to multiple US payment rails and want to build custom banking products without pre-funding requirements.
DecentroNot publishedFintech startups and businesses in India or APAC that need to launch payment or banking products quickly without building integrations from scratch.
 TemenosNot publishedEstablished banks and credit unions that need to modernize core banking, digital channels, payments, and wealth management on one platform.
 BBVA MexicoNot publishedMexican individuals and small businesses that want a traditional bank with a strong mobile app and branch network.
 ColumnNot publishedFintechs and financial institutions that need programmable banking infrastructure, from real-time payments to card issuing and lending.
 NombaNot publishedNigerian small businesses, freelancers, and corporate teams that need fast account opening, multi-currency wallets, and integrated payment collection.
 PrelimNot publishedBanks and credit unions that need digital account opening across multiple channels and want to automate maintenance workflows.
 TrussNot publishedConstruction companies that need to collect payments faster, pay subcontractors quickly, and manage crew spending without monthly fees.
 ArcFrom free, Premium paiStartups that want to earn yield on idle cash, access debt financing, and automate financial analysis in one platform.
 Elevate (formerly Bloom)Not publishedFreelancers and remote workers outside the US who need a USD account to get paid from international platforms.
 PayCaddyNot publishedLatin American companies, from banks to crypto exchanges, that want to launch branded Mastercard card programs quickly without rebuilding their core systems.
 GreyNot publishedRemote workers and digital nomads who need a multi-currency account with no maintenance fees and global payment capabilities.
About Banking Platforms
Banking platforms are software systems that let businesses move, store, and lend money programmatically. They connect to payment networks like ACH, wire, and card schemes, and often include ledgers, account management, and compliance tools. The job they do is to replace manual banking processes with automated, API-driven workflows.
The products on this list differ in approach, scale, and pricing model. Some, like Increase and Column, are API-first banks built for developers. Others, like Temenos and Prelim, serve established banks and credit unions. Regional platforms like Decentro, Nomba, and PayCaddy focus on specific geographies. Pricing models vary from published tiers, as with Arc, to custom quotes, as with most others.
The 12 best Banking Platforms, compared
- Not published
1.Increase
Best for: Fintechs and platforms that need direct access to multiple US payment rails and want to build custom banking products without pre-funding requirements.
- Pricing
- Not published
- Category
- Finance & Accounting
Increase is an API-first bank built for technology companies that need to move, store, and lend money programmatically. It connects directly to the Federal Reserve, Visa, and other networks without third-party vendors, giving you bare-metal access to ACH, wires, RTP, and card issuing. The team includes former Stripe and Visa engineers, and customers like Ramp and Check process billions of dollars through the platform.
Where it is strong
- Direct connections to FedACH, Fedwire, RTP, and FedNow
- Visa card issuance with real-time authorizations
- Immutable ledger and settlement tracking built in
Where it falls short
- Pricing is not published, so you must contact sales
- Requires engineering effort to integrate APIs and manage compliance
- Pricing:
- Pricing is not published on the site.
- Not published
2.Decentro
Best for: Fintech startups and businesses in India or APAC that need to launch payment or banking products quickly without building integrations from scratch.
- Pricing
- Not published
- Category
- Finance & Accounting
Decentro is an API platform that connects businesses to banking and payment systems across India and APAC, with support for 90+ currencies and payouts to 190+ countries. It offers plug-and-play modules like ledgers, multi-currency accounts, and escrow, which you can test in a sandbox before going live. Trusted by over 2,000 businesses, it reduces capex and opex by 90% and speeds up integration timelines.
Where it is strong
- Supports 90+ currencies and payouts to 190+ countries
- Includes ledgers, multi-currency accounts, and escrow workflows
- Sandbox testing and SDKs speed up launch
Where it falls short
- Pricing is not listed, so you must contact sales for quotes
- Focus on India and APAC may not suit teams needing global coverage beyond those regions
- Pricing:
- Pricing is not published on the site.
- Not published
3.Temenos
Best for: Established banks and credit unions that need to modernize core banking, digital channels, payments, and wealth management on one platform.
- Pricing
- Not published
- Category
- Finance & Accounting
Temenos is a cloud-native banking platform used by over 950 banks for core banking, digital banking, payments, and wealth management. It covers the full stack from core systems to financial crime mitigation, and offers SaaS deployment for modernization. Its credibility comes from being named a Leader in Gartner's 2026 Magic Quadrant for Retail Core Banking Systems in Europe.
Where it is strong
- End-to-end coverage: core, digital, payments, wealth, and financial crime mitigation
- Cloud-native and SaaS deployment options for faster modernization
- Trusted by 950+ banks, with Gartner Leader recognition in Europe
Where it falls short
- Pricing is not public, so budgeting requires a sales conversation
- May be more than smaller fintechs or startups need, given its enterprise focus
- Pricing:
- Pricing is not published on the site.
- Not published
4.BBVA Mexico
Best for: Mexican individuals and small businesses that want a traditional bank with a strong mobile app and branch network.
- Pricing
- Not published
- Category
- Finance & Accounting
BBVA Mexico is a full-service bank offering credit cards, loans, savings, investments, insurance, and payroll services for individuals, SMEs, and businesses. Its digital app lets you open accounts, pay bills, and manage money from your phone, with branch and phone support when you need it.
Where it is strong
- Open accounts and manage money from the mobile app
- Wide range of products: credit cards, loans, insurance, payroll
- 24/7 digital channels plus branch and phone support
Where it falls short
- Pricing and fees are not disclosed on the website
- Branch hours are limited on weekends and some locations
- Pricing:
- Pricing is not published on the site.
- Not published
5.Column
Best for: Fintechs and financial institutions that need programmable banking infrastructure, from real-time payments to card issuing and lending.
- Pricing
- Not published
- Category
- Finance & Accounting
Column is a nationally chartered bank built from the ground up for developers, with its own core, ledger, and direct connections to the Federal Reserve, TCH, and Swift. It moves hundreds of billions monthly with 99.999% uptime and is the top issuer of real-time payments in the US, making it a credible backbone for fintechs and financial institutions.
Where it is strong
- Direct connections to Federal Reserve, TCH, and Swift without middleware
- Programmable FDIC-insured accounts with disposable account numbers
- Built-in lending tools including loan origination and debt financing
Where it falls short
- Pricing not disclosed, likely custom for enterprise deals
- Requires engineering resources to integrate and build on
- Pricing:
- Pricing is not published on the site.
- Not published
6.Nomba
Best for: Nigerian small businesses, freelancers, and corporate teams that need fast account opening, multi-currency wallets, and integrated payment collection.
- Pricing
- Not published
- Category
- Finance & Accounting
Nomba is a business banking and payments platform for Nigerian companies, offering NGN and USD wallets, POS terminals, online checkout, and instant transfers. It is licensed by the Central Bank of Nigeria and deposits are NDIC-insured, and it is used by over 600,000 businesses. Accounts open in under three minutes with no setup fees.
Where it is strong
- Open an account in under 3 minutes with no setup fees
- NDIC-insured deposits and CBN licensing
- 24/7 human customer support
Where it falls short
- Pricing details are not stated on the site
- Primarily focused on Nigerian businesses, so may not suit teams outside Nigeria
- Pricing:
- Pricing is not published on the site.
- Not published
7.Prelim
Best for: Banks and credit unions that need digital account opening across multiple channels and want to automate maintenance workflows.
- Pricing
- Not published
- Category
- Finance & Accounting
Prelim is software for banks and credit unions to open accounts digitally across online, mobile, and in-branch channels. It handles consumer, business, and commercial onboarding, plus account maintenance, with real-time bidirectional core integrations and a workflow builder. With over 50 banking integrations, it's a credible pick for institutions wanting to reduce paperwork and speed up account opening.
Where it is strong
- Handles consumer, business, and commercial onboarding in one platform
- Real-time bidirectional core integrations with 50+ banking systems
- Workflow builder for custom approval chains and document generation
Where it falls short
- Pricing not listed, so budgeting requires a sales call
- No self-service option. Implementation likely needs vendor support
- Pricing:
- Pricing is not published on the site.
- Not published
8.Truss
Best for: Construction companies that need to collect payments faster, pay subcontractors quickly, and manage crew spending without monthly fees.
- Pricing
- Not published
- Category
- Finance & Accounting
Truss is a banking platform built specifically for construction companies. It lets contractors accept ACH and card payments online, pay subcontractors with instant fund access, and issue unlimited staff cards with rewards. The service has no monthly fees or minimums, includes free check service and ACH transfers, and offers enhanced FDIC insurance.
Where it is strong
- No monthly fees or minimums
- Free ACH transfers and check service
- Unlimited staff cards with spending limits
Where it falls short
- Pricing details not published
- May not suit businesses outside construction
- Pricing:
- Pricing is not published on the site.
- From free, Premium pai
9.Arc
Best for: Startups that want to earn yield on idle cash, access debt financing, and automate financial analysis in one platform.
- Pricing
- From free, Premium pai
- Category
- Finance & Accounting
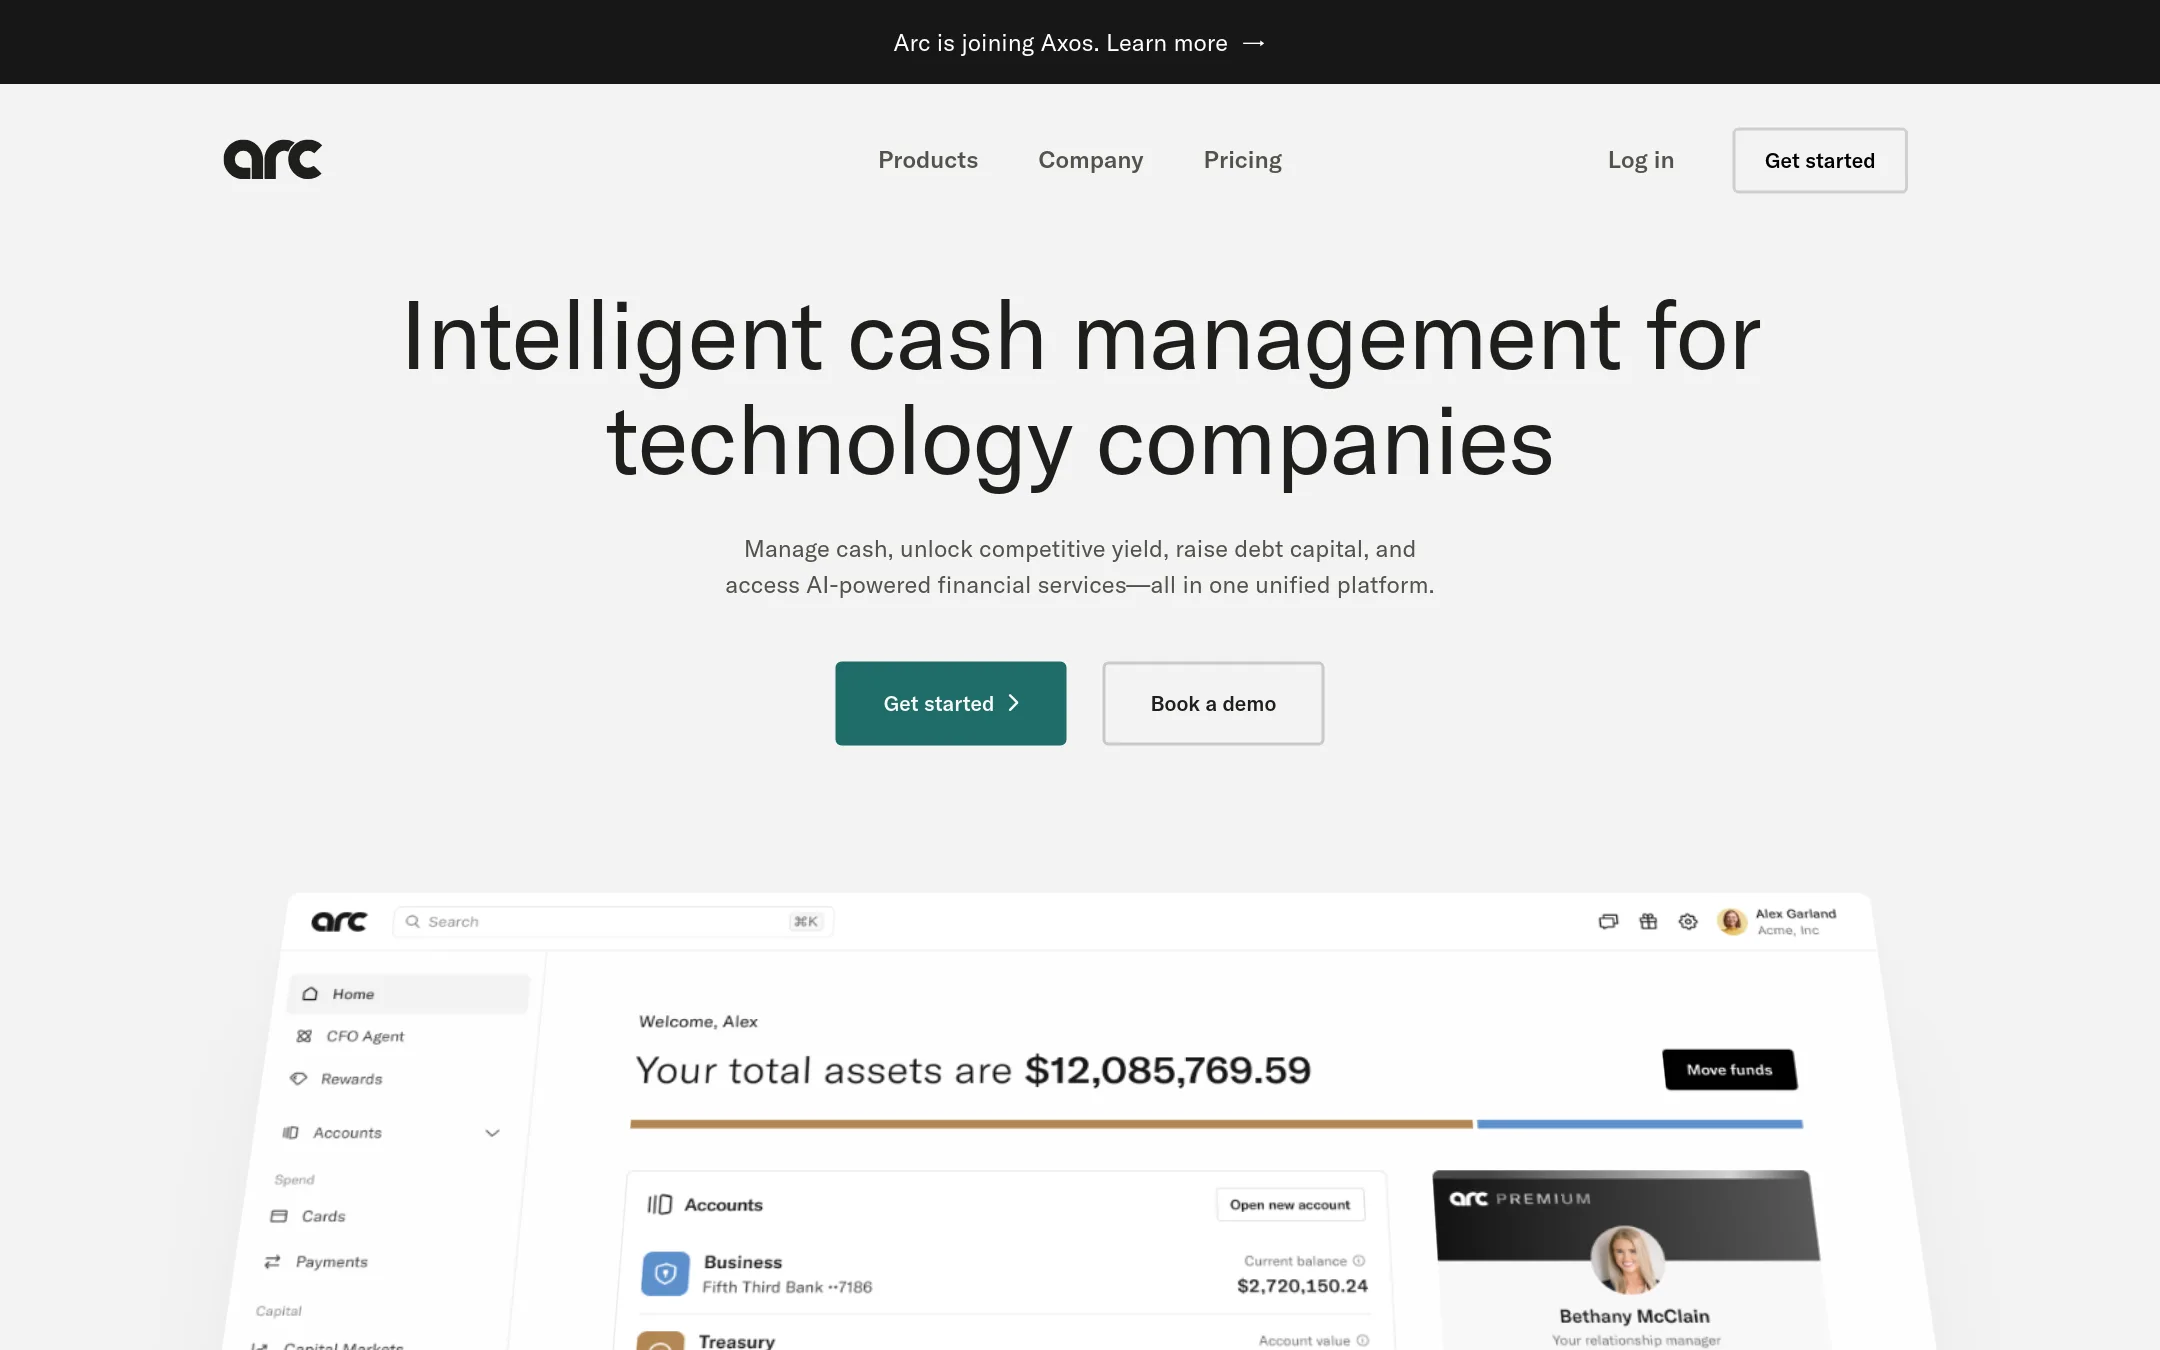
Arc combines cash management, yield on idle cash, and debt capital raising in one platform. It offers automated T-Bill laddering and an AI-powered CFO Agent for real-time analysis, making it a credible pick for startups that want to manage finances without minimums or usage-based fees.
Where it is strong
- Up to 3.96% net yield on idle cash
- Access to 200+ lender network for debt financing
- AI-powered CFO Agent for automated reporting
Where it falls short
- Higher yield tiers require annual paid membership
- Not for non-tech companies or those needing traditional bank branches
- Pricing:
- Pricing has three tiers: Essentials, Premium, and Enterprise. Essentials offers up to 3.51% net yield and 1.0% cashback. Premium offers up to 3.91% net yield and 1.5% cashback. Enterprise has custom fixed pricing and 2.0% cashback. No minimums or usage-based f
- Not published
10.Elevate (formerly Bloom)
Best for: Freelancers and remote workers outside the US who need a USD account to get paid from international platforms.
- Pricing
- Not published
- Category
- Finance & Accounting
Elevate gives non-US residents a US-based USD account to receive, send, and hold money. It works with platforms like Upwork, Deel, and Fiverr, and charges no fees for receiving income. Banking services come from FDIC-insured Merchants Commercial Bank, with deposits covered up to $250K.
Where it is strong
- No fees for receiving income
- Instant USD account after approval
- FDIC insurance up to $250K
Where it falls short
- Pricing details are not listed on the site
- Not a bank itself, so some banking features may be limited
- Pricing:
- Pricing is not published on the site.
- Not published
11.PayCaddy
Best for: Latin American companies, from banks to crypto exchanges, that want to launch branded Mastercard card programs quickly without rebuilding their core systems.
- Pricing
- Not published
- Category
- Finance & Accounting
PayCaddy is an API-based platform that lets Latin American companies launch card issuing programs and financial products. It serves banks, fintechs, crypto exchanges, retailers, lenders, and marketplaces, with both API-first integration for technical teams and a no-code whitelabel option for others. It supports Mastercard products with dedicated ICA and BIN sponsorship, and can issue virtual cards in 24 hours and physical cards in 30 days across 6+ countries.
Where it is strong
- API-first integration with RESTful API, webhooks, and sandbox environment
- No-code whitelabel dashboard with drag-and-drop config and managed compliance
- Dedicated ICA and BIN sponsorship for full brand ownership on Mastercard network
Where it falls short
- Pricing is not disclosed, so cost comparison is difficult
- Focus is on card issuing, not broader banking services like accounts or lending
- Pricing:
- Pricing is not published on the site.
- Not published
12.Grey
Best for: Remote workers and digital nomads who need a multi-currency account with no maintenance fees and global payment capabilities.
- Pricing
- Not published
- Category
- Finance & Accounting
Grey gives remote workers and digital nomads a multi-currency account with a global IBAN, zero account and card maintenance fees, and competitive exchange rates. It is regulated by FINTRAC and FinCEN, and banking services come from licensed partners, so you get a credible way to send, spend, and convert money worldwide.
Where it is strong
- Zero account and card maintenance fees
- Multi-currency account with global IBAN
- Regulated by FINTRAC and FinCEN
Where it falls short
- Pricing details are not listed on the site
- Not a bank. Banking services rely on licensed partners
- Pricing:
- Pricing is not published on the site.
How to choose Banking Platforms
Pricing structure matters. Most platforms do not publish pricing, so you must contact sales. Arc is the exception with three published tiers. If you need predictable costs, look for platforms with transparent pricing or be prepared for sales conversations.
Consider who the platform is built for. Increase and Column are for engineering teams that want to build custom products. Temenos and Prelim are for established banks. Truss is for construction companies. Choose a platform that matches your technical capacity and industry.
Integrations are critical. Prelim integrates with 50+ core banking systems. Decentro supports 90+ currencies and payouts to 190+ countries. PayCaddy offers Mastercard card issuing with dedicated ICA and BIN sponsorship. Verify that the platform connects to the networks and services you need.
Data and compliance are non-negotiable. Column is a nationally chartered bank with FDIC-insured accounts. Nomba is licensed by the Central Bank of Nigeria with NDIC-insured deposits. Elevate uses FDIC-insured Merchants Commercial Bank. Check the regulatory status and insurance coverage of each platform.
Support and contract terms vary. Nomba offers 24/7 human support. Prelim requires vendor support for implementation. Some platforms have no monthly fees, like Truss. Others require annual paid membership for higher yield tiers, like Arc. Understand the support model and contract flexibility before committing.
FAQ
Questions about Banking Platforms
What are banking platforms?
Banking platforms are software systems that let businesses move, store, and lend money programmatically. They connect to payment networks and include ledgers, account management, and compliance tools. They replace manual banking processes with automated, API-driven workflows.
How do banking platforms charge?
Most platforms do not publish pricing and require a sales conversation. Arc is an exception with three published tiers: Essentials, Premium, and Enterprise. Some platforms, like Truss, have no monthly fees or minimums. Always confirm pricing details before committing.
What should I look for in a banking platform?
Look for pricing structure, who the platform is built for, integrations, data and compliance, and support. For example, Prelim integrates with 50+ core systems, while Nomba is CBN-licensed with NDIC insurance. Choose a platform that matches your technical capacity and industry.
Can I use these platforms if I'm not a bank?
Yes, many platforms are built for non-banks. Increase and Column serve fintechs. Arc serves startups. Elevate serves freelancers. Some platforms, like Temenos, are for established banks. Check the best_for line to see who each platform suits.
Are these platforms safe and regulated?
Regulation varies. Column is a nationally chartered bank with FDIC-insured accounts. Nomba is licensed by the Central Bank of Nigeria with NDIC-insured deposits. Elevate uses FDIC-insured Merchants Commercial Bank. Always verify the regulatory status and insurance coverage of each platform.
Last updated October 16, 2026.